Your cart is currently empty!
Category: Uncategorized
-
Top 7 Lenders for Land Loans for Bad Credit in 2026
Top 7 Lenders for Land Loans for Bad Credit in 2026
Last updated: 2026-10-16
Finding a place to call your own becomes significantly harder when your credit score doesn’t tell a glowing story. If you are eyeing a piece of dirt for a future home or a weekend getaway, you know that traditional banks often slam the door shut on anyone with a bruised credit history. It feels like you are stuck in a rut, staring at beautiful acreage you simply cannot touch.
Securing financing for raw land is a different beast entirely compared to standard mortgages. Lenders view undeveloped property as a higher risk, which usually means they demand more collateral or higher interest rates. This ranking highlights options for those navigating the tricky waters of low credit, helping you distinguish between flexible lenders and those with strict requirements.
- FastLendGo
- AgWest
- USDA Rural Development
- Farm Credit
- AmeriCash Loans
- Sound Credit Union
- GreendayOnline
Evaluating Land Financing for Challenging Credit Profiles
To build this list, we scrutinized every lender based on their willingness to work with non-traditional borrowers. We looked at whether they offered specialized programs for rural development or if they functioned as marketplace facilitators. It is not just about who says yes, but how much it costs you to get that “yes” in the end.
We also prioritized accessibility and the specific types of land use supported by each institution. Some lenders focus on agricultural needs, while others are geared toward residential housing sites for low-income families. This distinction is vital because a farmer’s needs are worlds apart from a family looking to build a modest home in a rural community.
Lender Name Loan Amounts Credit Requirements Funding Speed Specialty FastLendGo $500 – $5,000+ Bad Credit Welcome Quick Access Personal Financing AgWest See site Subject to approval See site Agricultural Equipment/Land USDA Rural Development See site Low-to-moderate income focus See site Housing Site Development Farm Credit See site Reliable/Consistent Credit See site Agricultural Producers AmeriCash Loans See site Good credit not needed Instant decision Short Term Cash Sound Credit Union See site See site See site Commercial & Residential GreendayOnline $100 – $5,000 No Credit Check options Same day Emergency Cash 1. FastLendGo
FastLendGo operates as a versatile partner for those needing quick access to cash. They focus heavily on personal financing solutions, making them a flexible option for smaller, immediate financial needs that might arise during your land acquisition process. If you need a quick bridge to cover unexpected costs, they are a strong contender. (fastlendgo.com)
This lender is particularly suited for individuals who need to navigate various credit tiers, from great to bad. They offer a streamlined way to compare local options, which can save a lot of time during a stressful move or renovation. It is a digital-first approach designed for speed and simplicity.
Pros:
- Covers a wide range of credit scores, including bad credit.
- Offers quick access to cash for various needs.
- User-friendly online comparison tool.
Cons:
- Primarily focused on personal loans rather than large-scale land mortgages.
2. AgWest
AgWest is a specialized player in the agricultural space, bringing decades of experience to the table. They are not just about loans; they are deeply embedded in the machinery and service side of farming. This makes them a natural fit for someone looking to combine land acquisition with heavy equipment needs.
If you are a producer looking to expand your footprint, AgWest understands the nuances of the industry. Their deep roots in the agricultural sector mean they speak your language, whether you are discussing tractors or land use. They serve the hardworking folks who need real help and fast service.
Pros:
- Extensive experience in the agricultural equipment and land industry.
- Comprehensive service including parts and maintenance.
- Strong presence in regional agricultural markets.
Cons:
- May be more specialized toward agricultural needs rather than general residential land.
3. USDA Rural Development
The USDA is a heavyweight when it comes to supporting rural economies and families. Their programs, specifically Section 523 and Section 524, are designed to help low- and moderate-income families purchase and develop housing sites. This is a game-changer for those who want to build a home but lack massive capital.
These loans are not just about buying dirt; they are about building communities. By focusing on housing site development, the USDA helps bridge the gap between a dream and a physical foundation. It is a mission-driven approach to rural revitalization that benefits the entire local ecosystem.
Pros:
- Targeted support for low-to-moderate income families.
- Focuses on long-term community development.
- Government-backed stability.
Cons:
- Eligibility criteria can be quite strict regarding income and location.
4. Farm Credit
Farm Credit stands as a nationwide network of customer-owned cooperatives. They are dedicated to supporting the backbone of the country: farmers, ranchers, and rural businesses. If you are looking for reliable and consistent credit to fuel your agricultural ambitions, this is a cornerstone institution.
Because they are cooperatives, they are inherently focused on the success of their members. They support a massive number of producers across all fifty states. This scale allows them to offer specialized knowledge that a standard urban bank simply cannot match when dealing with rural infrastructure.
Pros:
- Nationwide reach with local expertise.
- Cooperative structure prioritizes member needs.
- Deep understanding of agricultural and rural business cycles.
Cons:
- Often requires a strong connection to the agricultural industry.
5. AmeriCash Loans
AmeriCash is built for momentum, focusing on short-term cash advances for those who need money today. Their application process is designed to be fast and simple, which is a lifesaver when you are facing an immediate financial hurdle. They do not require a perfect credit score to get started.
The process involves a marketplace model where your information is reviewed by lenders instantly. This can be incredibly efficient if you are looking for a quick decision. It is a highly streamlined way to find a lender who is willing to work with your specific situation.
Pros:
- Fast application and instant decision making.
- No requirement for good credit.
- Simple and secure online marketplace.
Cons:
- Typically geared toward short-term needs rather than long-term land financing.
6. Sound Credit Union
Sound Credit Union offers a comprehensive suite of services that makes them a one-stop shop for many. From home loans to commercial real estate, they cover almost every angle of personal and business finance. Their variety makes them a versatile choice for someone with complex financial goals.
They provide everything from basic checking to specialized business accounts and investment services. This breadth of service is ideal for a borrower who might need a land loan now but will eventually need auto loans or retirement planning. They are a traditional, stable choice for many.
Pros:
- Wide variety of loan products (Auto, RV, Boat, Business).
- Offers both personal and commercial banking.
- Comprehensive financial services under one roof.
Cons:
- May have more traditional credit requirements than specialized bad credit lenders.
7. GreendayOnline
When you are in a pinch and need emergency cash, GreendayOnline is a fast-acting option. They specialize in small payday loans that can be used for any purpose. Their primary advantage is the speed at which you can receive funds, sometimes as soon as the same day.
They are explicitly welcoming to those with bad credit, offering loans ranging from $100 to $5,000. This makes them a go-to for small, immediate expenses that might occur while you are managing a larger, more complex financial project like a land purchase.
Pros:
- Very fast approvals and quick funding.
- Explicitly accepts bad credit.
- Flexible loan amounts for various emergencies.
Cons:
- High-speed, short-term loans often come with significantly higher costs.
Navigating the Path to Land Ownership
Choosing the right lender is a marathon, not a sprint. If you are looking for a long-term mortgage for a residential lot, a credit union or a government-backed program like the USDA might be your best bet. They offer the stability needed for a decades-long commitment to a property.
However, if you are a farmer or someone looking to purchase equipment alongside land, specialized agricultural lenders like AgWest or Farm Credit will understand your cash flow better than anyone else. They know that your income might be seasonal, and they can work with that reality.
One common mistake is ignoring the fine print on short-term loans. While lenders like GreendayOnline or AmeriCash are lifesavers in an emergency, using them to fund a major land purchase can become an expensive trap. Always ensure your repayment plan matches the type of debt you are taking on.
Finally, remember that transparency is your best friend. Always ask about the total cost of borrowing, including any hidden fees or prepayment penalties. Being clear about your financial situation from day one will save you from a mountain of headaches down the road.
-
Top 5 Lenders for Bad Credit Loans in North Carolina: 2026 Rankings
Top 5 Lenders for Bad Credit Loans in North Carolina: 2026 Rankings
Last updated: 2026-10-16
Trying to balance your books in North Carolina can feel like trekking through a dense swamp when your credit score isn’t exactly stellar. Many residents find themselves facing unexpected car repairs, like a sudden transmission failure in Raleigh, or urgent medical bills from a trip to an urgent care center in Charlotte. These unexpected costs require immediate cash to keep life moving forward without a hitch.
These financial shocks can derail a monthly budget in a single afternoon. Suddenly, families find themselves scrambling to cover essential costs like rent or electricity. It is a stressful position to be in when the money you set aside for groceries is suddenly needed for a utility bill.
Finding the right lender involves more than just glancing at the interest rate. You have to weigh speed and accessibility against the total cost of borrowing. A loan with a lower interest rate might seem attractive on paper, but if it takes ten business days to fund, it won’t help you if the power company is threatening to shut off your electricity tomorrow.
On the flip side, a “quick cash” option might provide the speed you need, but it could carry an APR that makes the total repayment much higher than you expected. This list clarifies which options might suit your specific situation during uncertain times. It helps you weigh the trade-offs between immediate liquidity and long-term affordability.
- FastLendGo
- Addition Financial
- PaydayPact
- Credit Human
- LoanStart
Evaluating Financial Assistance Across the Tar Heel State
The selection process for this ranking focused on how easily a borrower can secure funds when their credit history is less than perfect. We looked at the ease of the application process and the speed of funding. We also considered the flexibility offered to those with subprime scores.
We specifically scrutinized the user experience for ease of use. We noted whether applications could be completed on a smartphone while waiting in line at a clinic, or if they required a desktop computer and a pile of scanned documents. Convenience often dictates whether a lender is actually helpful in a crisis.
In North Carolina, high interest rates are a common side effect of easy approval. Because the risk to the lender is higher when a borrower has a low credit score, the price of that risk is reflected in the APR. Therefore, the ranking prioritizes lenders that provide clear pathways for those who might have been turned away by traditional big-box banks earlier in the week.
We looked for transparency in every option. We wanted to know: does the lender show the total repayment amount upfront, or do you only find out after you have signed the digital agreement? Knowing the final number before you commit is essential for anyone trying to manage a tight budget.
Lender Name Loan Amounts Credit Requirements Funding Speed Terms FastLendGo $500 – $5,000 Bad Credit / Fair Credit Same day or next business day see site Addition Financial see site see site see site see site PaydayPact see site Guaranteed approval online see site see site Credit Human As little as $500 No credit review see site Up to 72 months LoanStart Up to $40,000 see site see site see site Ranking the Best Options for North Carolina Borrowers
1. FastLendGo
FastLendGo works well for those needing quick cash to cover immediate emergencies. Whether it is a sudden dental bill or a necessary auto repair, this service focuses on getting money into your hands without the usual mountain of paperwork. The streamlined digital interface is built for the modern consumer who needs to solve a problem in minutes rather than days. (fastlendgo.com)
This option is particularly suited for individuals who need specific amounts. You might need a $500 loan for a grocery bill gap or a $2,000 personal loan to fix a leaking roof. It caters to a wide spectrum of credit profiles, from those with bad credit due to a recent medical emergency to those with fair credit looking to build a better financial standing through consistent on-time repayments.
Pros:
- Offers various loan sizes from $500 to $5,000.
- Fast funding, potentially arriving the same day.
- No minimum credit score required to qualify.
Cons:
- Limited to specific smaller loan amounts.
2. Addition Financial
Addition Financial focuses on comprehensive banking needs beyond just quick cash injections. They offer a suite of products including checking accounts, credit cards, and mortgages. This makes them a more traditional choice for those looking to build a long-term relationship with a financial institution rather than just finding a one-off solution.
For members looking to grow their assets, they provide savings options and competitive rates. It is a solid choice if you want a stable institution rather than just a quick fix for an immediate financial crisis. If your goal is to move away from the high-interest cycle and toward traditional banking, this is a logical step.
Pros:
- Diverse range of banking products.
- Potential for earning through referrals.
- Comprehensive financial services.
Cons:
- May require more extensive documentation than quick-cash lenders.
3. PaydayPact
PaydayPact acts as a highly accessible digital portal for those facing rejection elsewhere. Their online system is designed to be secure and user-friendly. You can apply from any device, whether you are on a phone while commuting on a bus in Durham or on a laptop at home. This accessibility is crucial for people who may not have a fixed desk or a printer for paperwork.
The primary draw here is the promise of guaranteed approval online. This is a lifeline for someone who needs certainty in a moment of financial chaos. When you are facing a late fee on a rent payment, knowing you will get a “yes” or “no” immediately can significantly reduce the psychological stress of the situation.
Pros:
- High accessibility via mobile devices.
- Secure online application process.
- Focused on guaranteed approval.
Cons:
- High interest rates are common with this type of model.
4. Credit Human
Credit Human offers a more structured approach to borrowing with fixed rates. They provide a safety net for those who need to borrow as little as $500, but want the stability of a set repayment schedule. Because the rates are fixed, you won’t have to worry about your monthly payment changing unexpectedly due to market fluctuations.
One of their standout features is the ability to borrow without a traditional credit review. This makes them a very strong contender for anyone in North Carolina who is tired of being judged solely by a three-digit number on a screen. They may look at your broader financial stability, making them an excellent option for those who have had a temporary setback but are otherwise reliable.
Pros:
- Flexible repayment options up to 72 months.
- No credit review required for some products.
- Fixed rates provide predictability.
Cons:
- Terms can be long, leading to more total interest paid.
5. LoanStart
LoanStart functions as a matching service that connects borrowers with a network of affiliate lenders. Instead of looking at one single bucket of money, you are looking at a wide net of potential partners that might fit your specific needs. This is helpful because “one size does not fit all” in the lending world; what works for a student might not work for a small business owner.
This is the heavy hitter for those who need larger sums, with the potential to access up to $40,000. It is a great option for those who have maxed out credit cards and need a larger, structured installment loan to consolidate debt. By rolling several high-interest credit card balances into one larger loan, you can simplify your monthly finances and potentially save hundreds of dollars in interest over time.
Pros:
- Potential for high loan amounts up to $40,000.
- Free service that does not affect your credit score.
- Connects you to a wide network of partners.
Cons:
- You are at the mercy of the affiliate lender’s specific terms.
Comparing Loan Types: Quick Cash vs. Installment Loans
Understanding the difference between loan types is vital for North Carolina residents trying to manage their debt. Most lenders fall into one of two categories: Short-term/High-interest or Long-term/Installment loans. Choosing the wrong one can lead to a cycle of borrowing that is difficult to break.
Feature Short-Term Loans Installment Loans Typical Duration Days to a few months 12 to 72 months Interest Rates Very High (Often 300%+) Moderate to High (10% – 36%) Best Use Case Immediate emergencies (e.g., a $200 utility bill) Debt consolidation or large repairs (e.g., a $3,000 car engine) Repayment Structure Lump sum or frequent small payments Fixed monthly installments If you are facing a one-time expense that will be cleared by your next paycheck, a short-term loan might be the fastest path. However, if the amount you need is larger than your next two paychecks combined, an installment loan is a much safer way to avoid a “debt trap.”
Strategies for Managing Debt After Borrowing
Securing funds is only the first step; the second, and often more difficult, step is managing the repayment. Many North Carolina residents find themselves in a position where they have successfully resolved their immediate crisis but are now burdened by the new loan. To avoid this, consider these three proactive steps:
- Automate Your Payments: Set up automatic transfers from your checking account to the lender the day after you receive your paycheck. This ensures you never miss a payment, which is crucial for protecting your credit score.
- Prioritize High-Interest Debt: If you have multiple loans, use the “avalanche method.” This involves paying the minimum on all loans but putting every extra dollar toward the loan with the highest interest rate first. This mathematically minimizes the total amount of interest you pay over time.
- Negotiate with Creditors: If you are borrowing because you cannot pay a medical bill or a utility bill, call the provider *before* you take out a loan. Many companies have hardship programs or can offer a payment plan that is much cheaper than the interest rate on a quick-cash loan.
Avoiding Common Pitfalls When Borrowing
When you are in a pinch, it is easy to sign a contract without reading the fine print. Always look for the “total cost of credit,” which tells you exactly how much you will have paid back by the end of the loan term. For example, a $1,000 loan with a high interest rate might require you to pay back $1,500 over six months. That $500 difference is the “cost” of the convenience.
Avoid the trap of taking out a loan just to pay off another high-interest debt unless the new loan has a significantly lower rate. If you are using a high-interest payday loan to pay off a credit card, you are effectively moving the debt from one expensive bucket to an even more expensive one. If you find yourself constantly cycling through short-term loans, you might be stuck in a debt spiral that is hard to escape. This is often a sign that the underlying budget needs restructuring rather than more credit.
Lastly, verify the legitimacy of the lender before providing any sensitive information. While the digital age makes borrowing easy, it also makes it simple for bad actors to mimic real companies. Scammers often use aggressive language, like “You have been pre-approved! Act now or lose the offer!” to pressure you into giving up your Social Security number or bank login details. Always use official, secure websites to protect your identity and your wallet. Look for the “https://” in the URL and ensure the site has a padlock icon in the address bar before entering any personal data.
-
Top 6 Lenders for Postal Employees Seeking Loans with Bad Credit in 2026
Top 6 Lenders for Postal Employees Seeking Loans with Bad Credit in 2026
Last updated: 2026-10-16
Money problems rarely wait for a convenient time. For many postal workers, financial stress arrives in the form of a sudden transmission failure or an unexpected dental bill. These emergencies don’t care that your federal paycheck won’t arrive for another week. You need cash now to keep your life moving, but the timing is almost always wrong.
Large banks tend to be rigid. They rely on automated systems that flag a single missed payment or a low credit score, often ignoring the reality of your situation. If you work for the USPS, you have a level of job security that most private-sector employees can only dream of. You need a lender that sees that stability, rather than just a single number in a database.
The goal is to find a provider that looks at your actual ability to pay back a loan. This list highlights options that prioritize your employment stability over a perfect credit history. We’ve narrowed down the best paths for those who need quick cash without the traditional banking headaches.
- FastLendGo
- USPS Federal Credit Union
- BeneMoney
- NetCredit
- Hearth
- OneAZ Credit Union
How We Evaluated Financial Options for Postal Workers
We didn’t just pick names off a list. Each option was measured by how well it fits the specific lifestyle of postal staff. We looked for specialized programs designed for government employees, but we also checked general market players that offer flexible rules for people with less-than-perfect scores. We looked past the surface-level interest rates to see what the repayment structures actually look like.
Speed matters when your car is sitting in the driveway waiting for a part. Waiting two weeks for a bank’s decision is not an option during an emergency. We prioritized lenders that offer fast digital applications and, where possible, same-day or next-day funding. We also checked to see if the application process would ding your FICO score before you even see an offer.
A “hard pull” on your credit can drop your score by several points. This can hurt you if you plan to apply for a mortgage or an auto loan soon. Because of that, we favored lenders that use “soft pulls” for their initial eligibility checks. It’s a small detail that makes a massive difference in your long-term financial health.
Comparison of Leading Loan Providers
Lender Name Loan Amounts Credit Requirements Funding Speed Key Feature FastLendGo See site Bad/Fair Credit Quick Access Personal financing solutions USPS Federal Credit Union Up to $15,000 Member-based See site Rates as low as 4.75% APR BeneMoney See site No credit check Fast access Employer-offered benefits NetCredit Up to $10,000 Advanced algorithms Same-day funding available* Credit check won’t affect score Hearth See site See site See site Information and advice OneAZ Credit Union See site See site See site Financial coaching available Ranking the Best Lenders for Postal Employees
Your immediate goal dictates which lender you should pick. Are you trying to escape a mountain of high-interest debt, or do you just need a bridge to cover one weird expense this month? We’ve broken down the top contenders based on how they serve your specific needs.
1. FastLendGo
FastLendGo works well for those who need to compare local options quickly during a tight spot. They cover a wide range of needs, from a small $500 emergency loan to larger $5,000 personal financing solutions. This versatility helps if you aren’t sure exactly how much you’ll need to get through the month.
This is a solid choice for the postal worker who wants to bypass traditional bank hurdles. Whether you are facing auto repairs or a sudden dental bill, they focus on getting you a decision without unnecessary delays. Unlike banks that demand years of tax returns, FastLendGo looks at the broader context of your finances to provide relief.
Pros:
- Covers a wide range of loan amounts from $500 to $5,000.
- Specifically caters to bad, fair, and great credit scores.
- Offers specialized financing for specific needs like auto or dental.
- Terms and rates are not explicitly detailed for all credit tiers.
2. USPS Federal Credit Union
Since this institution is dedicated to the postal community, they understand your lifestyle and financial patterns. They offer everything from auto loans to flexible personal loans. Because they are member-owned, their interests align with yours rather than with outside shareholders looking for quick profits.
The community-centric approach often leads to rates as low as 4.75% APR. If you want long-term stability rather than a quick fix, this is a premier choice for managing larger debts or home equity. Consolidating high-interest credit card debt into a single, lower-interest monthly payment here is often the smartest mathematical move you can make.
Pros:
- Specifically serves the USPS community.
- Extremely competitive rates starting at 4.75% APR.
- Offers diverse products like HELOC and Visa credit cards.
- Membership is required to access the best rates.
3. BeneMoney
BeneMoney is different because it is tied directly to your job. It acts as a financial safety net offered through your employer, much like your health insurance. This model leverages your existing relationship with the USPS to help mitigate the stress of sudden expenses.
There are no credit checks, which makes this a lifesaver if you can’t qualify for traditional loans. It helps manage cash flow so a sudden $300 repair doesn’t derail your entire monthly budget. This is a great way to avoid the “payday-to-payday” trap that keeps so many people stuck in debt cycles.
Pros:
- No credit checks required to access funds.
- Reduces workplace financial stress significantly.
- Access to free credit counseling.
- Availability depends entirely on your specific employer.
4. NetCredit
NetCredit doesn’t use a “one-size-fits-all” approach. They use advanced algorithms to look past just a single credit score. They know a number in a database doesn’t tell the whole story of your reliability. By looking at a wider array of data, they can offer inclusive terms to people who might be rejected elsewhere.
This is a strong option if you need same-day funding and want to check eligibility without hitting your FICO score. They offer a streamlined digital experience for personal loans up to $10,000. You can see your potential terms in minutes, which is helpful for comparing offers before you commit to anything.
Pros:
- Checking eligibility does not affect your FICO score.
- Same-day funding is available for many users.
- Personalized underwriting through advanced technology.
- Maximum loan amount is capped at $10,000.
5. Hearth
Hearth works more like a knowledge hub than a direct lender for cash. It is a massive resource for anyone looking for advice on energy-saving equipment or home-related financial decisions. It bridges the gap between needing money and knowing exactly what you should spend it on.
For a postal worker looking to improve home efficiency, this is an invaluable tool. It provides the context needed to make informed decisions about large household investments. If you’re considering a new HVAC system to lower utility bills, Hearth can help you weigh the upfront cost against long-term savings.
Pros:
- Extensive forums and community advice.
- Useful calculators for home and energy projects.
- Focuses on efficient and responsible energy use.
- Not a direct source for quick cash personal loans.
6. OneAZ Credit Union
OneAZ is a full-service credit union that takes a holistic approach to banking. They offer financial coaching, which makes them a great partner if you want to fix your credit while seeking a loan. They don’t just hand you money and walk away; they provide tools to help you stay out of debt.
They offer everything from high-yield savings accounts to personal loans. For those in the Southwest, they provide a localized touch that national banks can’t match. Their coaching programs address the root causes of debt, like budgeting issues or high credit utilization, rather than just treating the symptom.
Pros:
- Offers financial coaching to help improve credit.
- High-yield savings options available.
- Strong community focus and local presence.
- May have more stringent requirements than specialized bad-credit lenders.
Strategic Steps for Managing Debt as a Postal Worker
Securing a loan is only half the battle; managing it is what determines your financial health. To ensure a temporary loan doesn’t become a permanent weight, try this approach:
- Assess the “Cost of Capital”: Look at the APR, not just the monthly payment. A $500 loan with a $50 monthly payment sounds easy, but if that loan lasts 24 months, you have paid $1,200 for a $500 emergency. Always ask how much total interest you will pay over the life of the loan.
- Analyze Your Budget Buffer: Use your latest USPS pay stub to calculate your disposable income after rent, food, and utilities. Your new loan payment should ideally represent no more than 10-15% of your take-home pay to avoid a debt cycle.
- Automate Repayments: Once you have the funds, set up automatic transfers. This prevents late fees and helps build a consistent history of on-time payments, which is the biggest factor in improving your credit score.
- Evaluate Consolidation vs. New Debt: If you are paying off credit cards, ensure the new interest rate is significantly lower. If it’s an emergency loan, make sure it is a one-off event rather than a recurring symptom of a larger budgeting issue.
Avoiding Common Financial Pitfalls
Read the fine print before you sign anything. A small monthly payment might look tempting, but if the term is too long, you could end up paying double the original amount in interest. Ensure the payment fits comfortably within your current salary, especially if you’re in a probationary period or expecting changes in overtime hours.
Don’t rush into the first offer just because you are in a hurry. Taking an extra hour to compare rates between a credit union and an online lender can save you hundreds of dollars. Always verify that the lender is legitimate and has a record of serving government employees. Look for FDIC or NCUA insurance to ensure your personal information is protected.
Be wary of predatory lenders who promise “guaranteed” approval. Legitimate lenders, even flexible ones like FastLendGo or NetCredit, still perform due diligence to ensure you can repay the debt. If a lender asks for an upfront fee before releasing your loan, walk away immediately. That is the hallmark of a scam.
-
The 6 Best Lenders for RV Financing Ranked for 2026
The 6 Best Lenders for RV Financing Ranked for 2026
Last updated: 2026-10-16
Hitting the open road in a luxury motorhome or a cozy travel trailer is a dream for many. However, the sticker price of a modern recreational vehicle can often feel like a mountain too high to climb without the right financial partner. Unlike a standard passenger car, an RV is often a hybrid asset—part vehicle, part home, and part lifestyle investment. Because of this dual nature, the financing landscape is significantly more complex than traditional auto lending.
Finding a lender that understands the nuances of lifestyle vehicles is essential. Whether you are looking for a second home on wheels or a weekend camper, the right financing determines how much freedom you actually enjoy once the engine starts. A high-interest rate or an inflexible repayment schedule can quickly turn a dream vacation into a financial burden that keeps you parked in your driveway instead of exploring the national parks.
- FastLendGo
- My Financing USA
- Southeast Financial
- GreatRVLoan
- GadCapital
- Manhattan Bank
How We Evaluated the Top RV Financing Options
Selecting a lender isn’t just about chasing the lowest interest rate. It involves looking at the speed of the approval process, the flexibility of the terms, and whether the company handles various types of credit profiles. A lender that is great for a luxury coach might be terrible for a used camper van. For example, a lender specializing in high-end diesel pushers may require a massive down payment and proof of significant liquid assets, whereas a lender focused on used trailers might prioritize collateral value and secondary market stability.
Our evaluation framework looked at several critical dimensions:
- Loan Structure: Does the lender offer fixed-rate loans (which provide stability) or variable rates (which might start lower but can increase)?
- Asset Versatility: Can they finance a new Class A motorhome, a used pop-up camper, or even a specialized recreational asset like a boat or jet ski?
- Speed of Funding: How quickly can the funds be disbursed once the deal is struck at the dealership?
- Credit Inclusivity: Does the lender have pathways for those with a “thin” credit file or those recovering from past financial setbacks?
This ranking considers a wide spectrum of needs, from high-income individuals seeking personal loans to those battling credit challenges. We looked at specialized brokers, traditional credit unions, and digital-first lenders to ensure a diverse list that covers every traveler’s specific financial situation.
Lender Name Loan Types Credit Requirements Special Features FastLendGo Personal Loans Good to Bad Credit Quick access to cash My Financing USA RV and Boat Loans Good and Bad Credit Nationwide search Southeast Financial Various Vehicle Loans See site Credit Union benefits GreatRVLoan New, Used, Private Party Challenged Credit Terms up to 20 years GadCapital Payday/Short-term No Credit Check Instant installments Manhattan Bank Personal & Business See site FDIC-Insured The Top-Rated RV Financing Lenders for 2026
1. FastLendGo
FastLendGo functions as a versatile bridge for those who need immediate liquidity. While they offer specialized personal loans, their ability to cater to various credit tiers makes them a standout for quick financial needs. This is particularly useful for the “impulse buyer” who finds a perfect used camper at a private sale and needs to secure funds before the seller moves on to the next person. (fastlendgo.com)
This lender is particularly suited for individuals who need to bridge a gap in funds for smaller expenses. They offer a range of solutions from $500 up to larger personal loan amounts for high-income earners. Because these are often unsecured personal loans, they do not require you to use the RV itself as collateral, which can be a significant advantage if you want to keep your recreational vehicle separate from your primary debt obligations.
Pros:- Covers a wide range of credit scores from bad to great.
- Offers quick access to cash for various needs.
- Specialized options for high-income individuals.
- Focuses more on personal loans than dedicated RV-specific structured financing.
2. My Financing USA
If your heart is set on a specific boat or a massive fifth wheel, My Financing USA acts as a dedicated navigator. They specialize in searching nationwide to find the best programs for your specific lifestyle vehicle. They don’t just look at one bank’s catalog; they scan the landscape to match your profile with the most appropriate lender.
They are a powerhouse for those looking at diverse recreational assets. From camper vans to yachts and even jet skis, their scope is impressively broad, making them a one-stop shop for water and land enthusiasts alike. This breadth is essential for the lifestyle traveler who may own a motorhome for the highways and a boat for the coast, wanting to consolidate their recreational financing efforts through a single, expert source.
Pros:- Extensive variety including boats, RVs, and even jet skis.
- Nationwide search for the best possible programs.
- Specific options for both good and bad credit.
- The breadth of products may lead to more complex application processes.
3. Southeast Financial
As a full-service credit union, Southeast Financial provides a stable, member-focused environment. They offer a comprehensive suite of services that extend far beyond just vehicle loans, including mortgages and wealth management. This makes them an excellent choice for someone who wants to centralize their entire financial life—from their primary mortgage to their weekend adventure vehicle—under one roof.
This is an ideal choice for the established traveler who wants their financing tied to a broader banking relationship. Their membership-based structure often provides a different level of personalized service and community-oriented benefits. Because credit unions are non-profit entities, they often return value to their members in the form of lower interest rates on loans or higher yields on savings accounts compared to traditional commercial banks.
Pros:- Comprehensive financial services from insurance to wealth management.
- Credit union structure offers member-centric benefits.
- Wide array of loan products including auto and home.
- Membership requirements may limit availability to certain groups.
4. GreatRVLoan
GreatRVLoan is a specialized West Coast brokerage that has been navigating the RV financing landscape since 2002. They understand that a recreational vehicle is more than a machine; it is a way to achieve a dream. Their tenure in the market gives them an edge in understanding how depreciation rates on different RV models affect loan approval and interest rates.
They excel in complex scenarios, such as out-of-state purchases or private party transactions. Many traditional lenders shy away from “private party” sales—where you buy a camper from an individual rather than a dealership—because of the increased risk and lack of standardized paperwork. GreatRVLoan, however, has established workflows to handle these transactions, making them a vital resource for the savvy used-market buyer.
Pros:- Expertise in specialized scenarios like private party sales.
- Extremely flexible terms reaching up to 20 years.
- Handles challenged credit programs effectively.
- As a brokerage, they may act as an intermediary rather than the direct lender.
5. GadCapital
Sometimes, financial emergencies don’t wait for a scheduled payment. GadCapital focuses on the immediate, providing high-speed installment and payday loans for those facing urgent, short-term cash needs. This might include sudden repair costs for a rig that has broken down in the middle of a trip, or unexpected taxes that must be paid before a seasonal camping trip can begin.
This lender is designed for speed and accessibility, specifically targeting those who might struggle to find traditional bank support. They offer a direct route to cash through a simple, digital-first application process. While these are not long-term financing solutions for purchasing a multi-thousand-dollar motorhome, they serve as a vital liquidity tool for the unexpected costs of the RV lifestyle.
Pros:- Designed for immediate, urgent financial needs.
- No credit check options available for quick access.
- Simple online application for fast results.
- High-speed, short-term loans often come with higher costs.
6. Manhattan Bank
Manhattan Bank offers the security of a traditional, FDIC-insured institution. They provide a structured environment for those seeking personal or business loans through established, regulated banking channels. This is a primary choice for entrepreneurs who want to finance a luxury RV through their business entity as a tax-deductible business expense.
This is the best fit for the conservative borrower who prioritizes the safety and stability of a regulated bank. They focus on providing loans for “every occasion” within a professional, secure framework. While they may not have the “flashy” digital interfaces of a fintech startup, their institutional stability offers peace of mind that their long-term financial standing is backed by a massive, regulated entity.
Pros:- FDIC-insured, offering high levels of security and trust.
- Established, professional banking environment.
- Versatile personal and business loan options.
- Traditional banking processes can be slower than fintech competitors.
Key Factors to Consider Before Signing Your RV Loan
Securing a loan is only the first half of the equation; managing it is the second. Because RVs are depreciating assets—meaning they lose value over time—it is crucial to understand how your loan’s structure interacts with the vehicle’s value.
Understanding Depreciation and “Upside-Down” Loans
One of the greatest risks in RV financing is becoming “upside-down” or “underwater” on your loan. This happens when the amount you owe on the loan is greater than the actual market value of the RV. This is particularly common with new, high-end motorhomes that experience a sharp drop in value the moment they are driven off the lot. To mitigate this, aim for a significant down payment (20% is often recommended) to ensure you have equity in your vehicle from day one.
The Total Cost of Ownership (TCO) Equation
When calculating your budget, do not just look at the monthly loan payment. A realistic budget must include the following “hidden” costs of RV ownership:
Expense Category Typical Monthly Impact Notes Insurance $100 – $300+ Specialized RV insurance is different from auto insurance. Storage Fees $50 – $200 Necessary if you don’t have driveway space. Maintenance $100 – $500 Includes oil changes, tire rotations, and roof inspections. Campground Fees Variable Can range from $30 (primitive) to $150+ (resort). Navigating the Path to Your New Rig
The road to ownership is often paved with many different financial choices. Before signing any paperwork, it is vital to look beyond the monthly payment and examine the total cost of the loan over its entire lifespan. A $500 monthly payment might look manageable, but if that payment is spread over 20 years at a high interest rate, you could end up paying for the RV twice in total interest costs.
Avoid the trap of only looking at the immediate approval. A quick approval might come at a steep interest rate cost that bites you later. Always ask about prepayment penalties, as these can prevent you from paying off your RV early to save money. If you come into a windfall or receive a tax refund, you want the freedom to reduce your principal without being penalized by the lender.
Lastly, ensure your documentation is ready to go. Whether you are dealing with a specialized broker or a massive bank, having your income verification (W-2s, recent pay stubs, or tax returns for self-employed individuals) and credit history ready can turn a weeks-long process into a matter of days. Preparation is the difference between securing the perfect rig and seeing it sold to someone else while you’re still waiting on a credit check.
-
Top 5 Lenders for Bad Credit Loans in Virginia: 2026 Rankings
Top 5 Lenders for Bad Credit Loans in Virginia: 2026 Rankings
Last updated: 2026-10-16
Managing money in Virginia can feel like walking through a thick fog, particularly when your credit score isn’t cooperating. Many residents face mounting bills or sudden car repairs, searching for a lifeline that doesn’t include a lecture from a bank manager. Whether you live in the busy suburbs of Northern Virginia or the quiet stretches of the Shenandoah Valley, cash needs often arrive without warning.
Waiting weeks for a national bank to approve a loan isn’t always an option when life hits hard. When you need a way forward, the goal is finding speed and clarity. This ranking looks at who actually gets money into your hands quickly and which platforms offer transparent paths for those with less-than-perfect financial histories.
We looked at how different lending models work, from peer-to-peer networks to traditional credit unions, to map out your options. We wanted to find out which services actually deliver when the pressure is on.
- OppLoans
- JetzLoan
- Flexxbuy
- Prosper
- OneAZ Credit Union
Evaluating Financial Assistance Options Across the Commonwealth
Speed is a massive factor here. Most people seeking these loans are facing immediate, pressing needs. A lender that takes a week to process an application is useless during a real-world emergency, like a sudden medical bill or a broken-down car needed for work. We tracked how quickly funds move from the moment of approval to your checking account.
We also watched how applications affect your credit score. “Credit shopping” can be a dangerous game. If every lender you talk to performs a “hard pull,” your FICO score can drop before you even commit to a loan. We looked for providers that allow for “soft pulls” so you can check rates without hurting your standing.
Finally, we checked the range of loan amounts. We wanted to ensure the list covers everything from a $500 quick fix to a $100,000 major purchase. This ensures you find something suitable whether you are filling a tiny gap or tackling a large debt.
Lender Name Loan Amounts Funding Speed Credit Impact (Inquiry) OppLoans $500 – $5,000 Same-day available No impact to FICO JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull Flexxbuy Up to $100,000 Next business day See site Prosper $2,000 – $50,000 See site No impact to credit OneAZ Credit Union See site See site See site Understanding the Different Types of Lending Models
Before picking a provider, it helps to understand why their requirements differ. Not all loans are created equal. Knowing which category of lender you are dealing with can prevent nasty surprises during the application process.
Traditional Banking vs. Specialized Online Lenders
Traditional banks usually demand a high FICO score and a long history of steady income. They offer low interest rates, but they are notoriously rigid. If your score dipped because of medical debt or a period of unemployment, a traditional bank might reject you instantly.
Specialized online lenders often look at alternative data. They might check your banking history, employment status, or even how you pay your utilities to determine your creditworthiness. This makes them much easier to access for Virginians with “thin” credit files.
Peer-to-Peer (P2P) Lending Explained
Platforms like Prosper use a crowdsourced model. Instead of borrowing from a bank’s own capital, you are borrowing from a pool of individual investors. This changes the risk profile. Investors might take a slightly higher risk to get a higher return, which opens doors for borrowers who wouldn’t qualify at a standard institution.
This model often leads to more competitive interest rates than predatory payday lenders. However, you still need a baseline level of financial stability to qualify. It’s a middle ground between big banks and high-interest lenders.
Point-of-Sale and High-Ticket Financing
Some financing is tied specifically to a purchase. This happens often when you are at a large retailer or a specialized service provider. Rather than getting cash in your bank account, the lender pays the merchant directly, and you pay the lender back in installments.
This is often the easiest way to acquire a large asset without a massive upfront cash payment. It simplifies the process by cutting out the extra step of managing the cash yourself.
The Best Lenders for Bad Credit Loans in Virginia
1. OppLoans
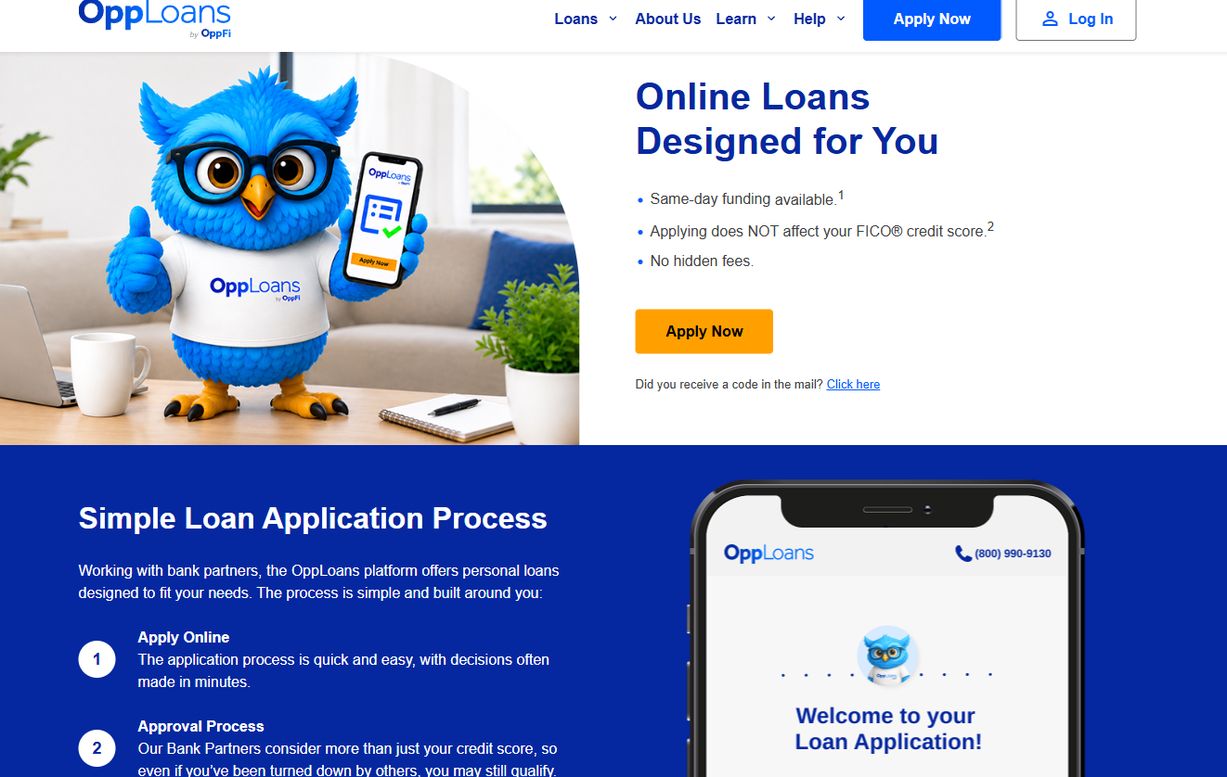
This platform helps those who feel they have hit a dead end with mainstream banks. By working with various bank partners, they look beyond just the numbers on a credit report to find a way to say yes to Virginia residents. They are a solid choice for people with “bruised” credit—meaning you have a history of late payments but are currently managing things responsibly.
It is a great choice if you need a small amount to cover a quick gap, like an unexpected utility bill or a grocery expense. Because the application is fast, decisions often happen within minutes. This makes it a reliable tool for urgent situations.
The digital interface is easy to use. You can upload necessary documents via your smartphone, which is vital if you can’t visit a physical branch during business hours.
Pros:
- Same-day funding is available for approved applicants.
- The application process does not affect your FICO score.
- Decisions are made quickly, often in a matter of minutes.
Cons:
- Loan amounts are capped at a relatively low $5,000.
2. JetzLoan
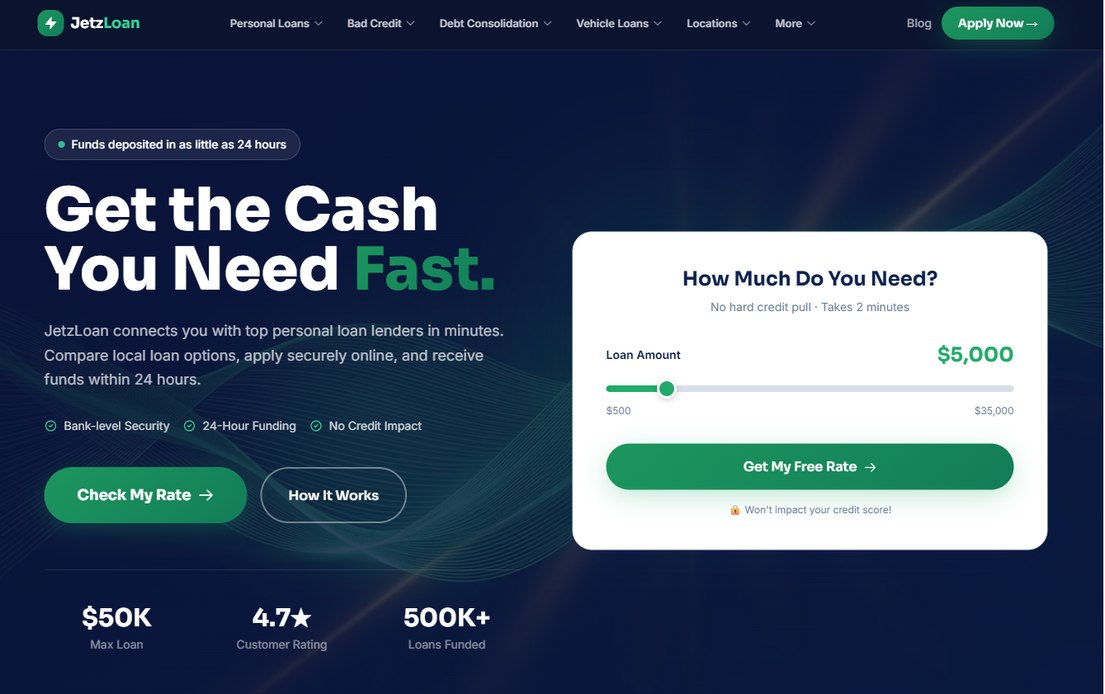
If you need a larger sum to consolidate debt or fix a vehicle, this service provides a connection to top lenders. They try to make the experience feel less like a chore and more like a streamlined digital transaction. JetzLoan acts as an aggregator, scanning a network of lenders to find the one most likely to approve your specific credit profile.
The platform is built for speed, targeting a 24-hour window for funds to land in your account. This is a strong contender for those who need significant cash but cannot wait for traditional underwriting. If your car’s transmission fails, you need that money to get back to work immediately. A 24-hour turnaround can be the difference between keeping your job and losing your transportation.
Pros:
- Can provide much larger loans, up to $35,000.
- High customer rating with over 500,000 loans funded.
- No hard credit pull to check your initial rate.
Cons:
- The process requires a simple form that may still require sensitive info.
3. Flexxbuy
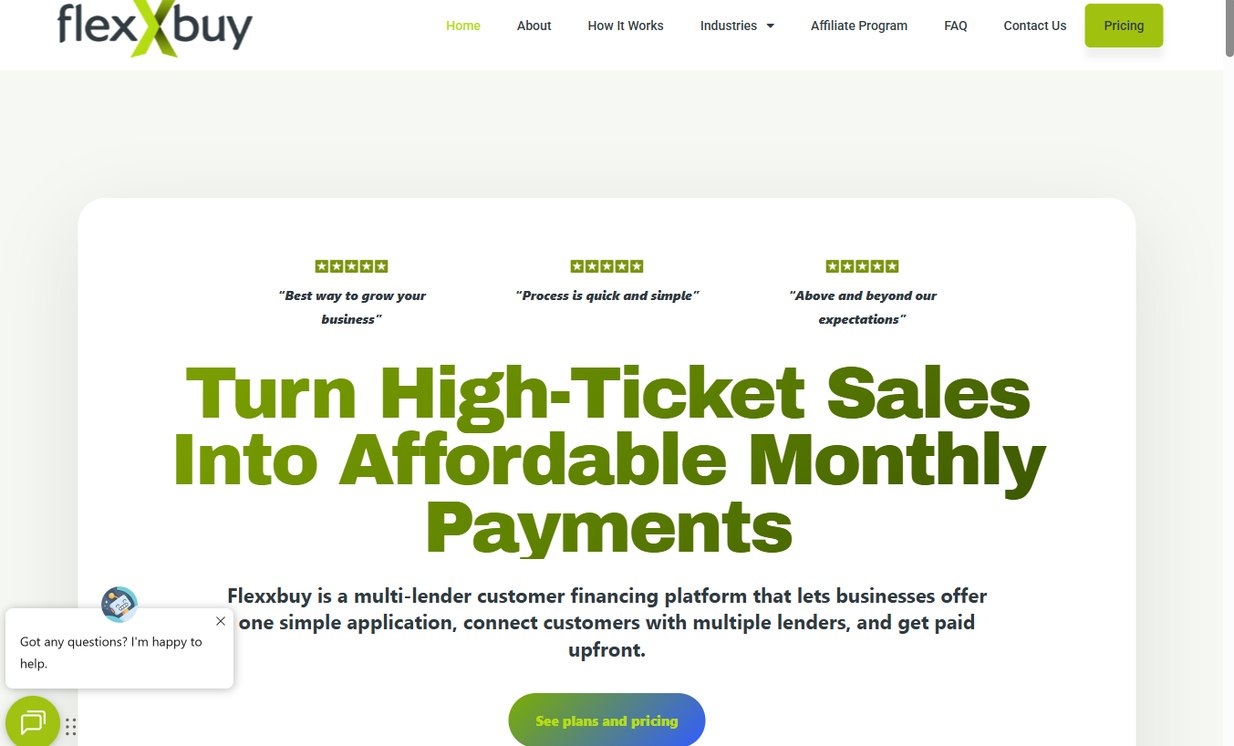
This is not your typical personal loan provider; it is a multi-lender platform designed for high-ticket sales. It functions as a link between businesses and customers who want to pay for expensive items through installments. You will frequently see this used for home improvements, major appliances, or high-end electronics.
It is a unique option if you are looking to finance a major purchase rather than just covering a monthly bill. Instead of receiving a lump sum of cash, you use this to complete a specific, high-value transaction. By connecting customers with over 35 different lenders, it maximizes your chances of finding a fit, often with terms much better than a standard credit card.
Pros:
- Extremely high loan amounts reaching up to $100,000.
- Fast decisions that can lead to next-day funding.
- A wide variety of lenders to choose from.
Cons:
- Primarily focused on high-ticket customer financing.
4. Prosper
Prosper operates in the peer-to-peer space, which follows different rules than a standard bank. This can be a breath of fresh air for those looking for personal loans with more flexibility. Because the money comes from individual investors rather than a corporate reserve, the approval criteria can be more nuanced than the “yes/no” algorithms used by big banks.
It works best for individuals needing medium-to-large loans, ranging from $2,000 up to $50,000. This makes it a primary candidate for debt consolidation. You can take several high-interest credit card balances and roll them into one single, manageable monthly payment.
The ability to see a rate in just one minute allows for quick comparison shopping. You can check your options without any immediate damage to your credit, making it easy to compare your current debt to a potential new loan.
Pros:
- Offers a wide range of loan amounts for various needs.
- The rate check has no impact on your credit score.
- Highly rated by financial comparison sites.
Cons:
- The minimum loan amount starts at $2,000.
5. OneAZ Credit Union
Credit unions offer a community-focused alternative to the massive national lenders. While often tied to specific regions, they provide a more personalized experience that can be vital when managing complex financial situations. Because they are member-owned cooperatives, their primary goal is to serve members rather than maximize profits for shareholders.
This is a solid choice if you prefer a traditional, stable institution over a purely digital platform. If you have a complicated situation—perhaps a recent change in employment—you can often sit down with a loan officer to explain your circumstances.
They offer various products, including savings accounts and financial coaching. This can help long-term stability by giving you the tools to avoid needing a loan in the future.
Pros:
- Offers diverse financial products like savings and coaching.
- Provides a more personal, community-oriented banking experience.
- Potentially higher interest rates on savings accounts.
Cons:
- May require more traditional application steps than instant lenders.
Navigating Your Loan Options Wisely
Before signing anything, you must understand the total cost of the money you are borrowing. Interest rates vary wildly. A $5,000 loan with a 24% interest rate paid over 36 months will cost you significantly more than a $5,000 loan with a 12% rate paid over 12 months. Always check for hidden fees like origination fees or prepayment penalties.
Another pitfall is borrowing more than you actually need. It is easy to get excited by a large sum of cash, but every dollar borrowed must be repaid with interest. This is especially dangerous if the loan is for “lifestyle” expenses rather than “needs.” Use these loans to solve a specific problem, like an emergency car repair, not to fund a lifestyle you cannot afford.
Finally, remember that a loan is a temporary fix if your underlying habits don’t change. If you are constantly relying on short-term loans to cover monthly living, you likely have a structural budget deficit. Use the time provided by the loan to stabilize your budget, build an emergency fund, or improve your credit score. This turns a quick injection of cash into a stepping stone toward real financial freedom.
-
The 6 Best Lenders for Bad Credit Loans in Louisiana for 2026
The 6 Best Lenders for Bad Credit Loans in Louisiana for 2026
Last updated: 2026-10-16
Trying to sort out your finances in Louisiana can feel like driving through a thick bayou fog without your headlights on. Many people here deal with credit scores that simply don’t show who they really are or their actual ability to pay back a loan. When a sudden car repair or an unexpected medical bill lands on your kitchen table, you need clear answers, not more confusion.
Whether you live in the busy streets of New Orleans or a quiet parish further inland, the pressure of money is a shared struggle for many hard-working Louisianans. Finding a lender that understands the reality of a low credit score is the first move toward getting back on your feet. This list looks at everything from local credit unions to digital lenders.
Each option offers a different route. You might need a quick cash infusion to get through the month or a long-term plan to consolidate nagging debts. Getting the right choice requires looking past the initial interest rate. You have to dig into the fine print of the terms, the conditions, and those repayment schedules.
- FastLendGo
- Coastline Credit Union
- LightStream
- United Finance
- Addition Fi
- GadCapital
How Louisiana Borrowers Are Evaluated
Picking a lender isn’t just a race to see who says yes the fastest. In the Pelican State, lenders look at several things, such as how steady your income is and your debt-to-income ratio. Credit scores are a big part of the puzzle, but they aren’t the only tool in the kit. Some lenders care more about your ability to pay them back through steady work.
For instance, a lender might ask for your last three months of bank statements to verify a consistent pattern of deposits. This can often carry more weight than a single dip in your FICO score caused by a one-time medical bill. Speed also matters when you are facing an emergency. If your car transmission dies on a Friday and you need to get to work by Monday, a two-week approval process might as well be a decade away.
We looked at these providers based on how accessible they are for people with less-than-perfect credit, how much they lend, and how fast they move from application to cash in hand. When you compare them, keep an eye on the “Total Cost of Borrowing.” This includes the interest rate along with any origination fees or administrative costs that might pop up during the closing process.
Lender Name Loan Amounts Interest Rates Funding Speed Credit Requirements FastLendGo $500 – $5,000+ see site see site Bad/Fair Credit Coastline Credit Union see site see site see site see site LightStream see site 9.99% – 24.94% APR Next day Excellent Credit United Finance Up to $20,000 see site see site see site Addition Fi see site see site see site see site GadCapital $100 – $5,000+ see site Instant No Credit Check Top-Rated Options for Louisiana Residents
1. FastLendGo
FastLendGo provides a way forward for people who might feel ignored by the big national banks. They specialize in various personal financing solutions, specifically for those who have a less-than-stellar credit history. Their digital-first approach aims to make the comparison process simple for local borrowers. You don’t have to drive from parish to parish to hunt for a specialist. You can evaluate your options right from your living room. (fastlendgo.com)
If you are facing a dental emergency or need to fix a leak in your roof, they offer several specialized loan types. Their platform handles everything from small $500 loans to larger $5,000 requests. It is built for people who need to move quickly without drowning in a mountain of paperwork. This makes them a useful tool for filling the gap between a sudden crisis and your next paycheck.
Pros:- Specializes in bad credit and fair credit loans.
- Offers specific loans for auto repairs and dental work.
- User-friendly online comparison tool.
- Lacks the personalized community feel of a local credit union.
2. Coastline Credit Union
Credit unions are often the hidden gems of the financial world. Coastline Credit Union offers a more traditional, community-focused banking experience. For Louisianans who prefer a lender that feels like a neighbor rather than a faceless corporation, this is a strong contender. Because credit unions are member-owned cooperatives, their main goal is service rather than maximizing profit for shareholders. This often leads to more flexible terms for members.
They provide a variety of solutions, including standard loans and online banking features. While they might have stricter requirements than a payday lender, the relationship you build with a credit union can be incredibly helpful for your long-term financial health. If you maintain a steady relationship with them, you might find it easier to secure a mortgage or an auto loan later on, since they have a history of your reliability.
Pros:- Member-focused service model.
- Offers online and mobile banking convenience.
- Potential for better long-term rates through membership.
- May require membership eligibility.
3. LightStream
LightStream is a high-tier option for those who have worked hard to build a stellar credit profile. They aren’t the solution for someone currently in a deep credit hole. However, for those with excellent credit, they are hard to beat. They offer a streamlined application process that respects your time. This is an ideal choice for major life milestones where saving on interest can mean thousands of dollars over the life of the loan.
The platform is versatile, allowing you to fund everything from home remodels to wedding expenses. Their speed is impressive; many users report having funds in their accounts as quickly as the next day. This makes them a favorite for significant, planned life transitions. If you want to consolidate high-interest credit card debt into a single, lower-interest payment, LightStream’s structure is built for that exact purpose.
Pros:- Extremely fast funding, sometimes by the next day.
- Low fixed rates with AutoPay discounts.
- Highly versatile loan purposes.
- Requires excellent credit to access the best rates.
- Not suitable for those with poor credit.
4. United Finance
United Finance is a seasoned veteran in the lending space, having been around since 1922. They bring a level of stability that is hard to find in the modern era of fintech. They offer both personal and auto loans designed to fit into a realistic budget. Their longevity in the market shows they can handle changing economic climates, from the Great Depression to the digital revolution.
Their approach focuses on making personal loans simple and accessible. They provide a dedicated team of friendly lenders to help guide you through the process. This human element is vital if you find digital applications confusing or overwhelming. It is especially helpful for borrowers with complex financial situations, such as self-employment income, that an automated algorithm might automatically reject.
Pros:- Decades of experience and stability.
- Personal loans available up to $20,000.
- Offers auto loans and refinancing options.
- More traditional structure may be slower than digital-only lenders.
5. Addition Fi
Addition Financial operates with a focus on helping members grow their wealth and manage daily banking. They are more than just a lender; they act as a full-service financial partner. From checking accounts to investment options, they aim to be a one-stop shop. This allows members to see their entire financial life in one place, making it easier to track spending and savings habits.
They offer competitive rates and encourage a community-based approach to banking. For those looking to move away from large national banks toward a more personalized experience, Addition Fi provides the tools to save, borrow, and invest in one place. Their ecosystem supports borrowers through various stages of life, from that first car loan to eventual retirement planning.
Pros:- Comprehensive suite of banking and investment services.
- Referral programs to help grow the community.
- Competitive rates for various products.
- Requires becoming a member to access all benefits.
6. GadCapital
When the situation is dire and the clock is ticking, GadCapital is the “break glass in case of emergency” option. They specialize in online payday and installment loans for people with bad credit. They are designed for immediate action when conventional banks say no. This is a niche service for high-urgency situations where a standard three-day approval window is simply too long.
The platform allows for very small, quick loans, starting from as little as $100. If you are facing an urgent emergency—like a utility shut-off notice or an immediate medical co-pay—GadCapital is built to handle that pressure without a lengthy credit check. However, you must be extremely disciplined with repayment to avoid the compounding effects of high interest.
Pros:- No credit checks for certain loan types.
- Instant access to funds for urgent needs.
- Flexible amount ranges from $100 to $5,000+.
- Payday-style loans often come with very high costs.
- Risk of a debt cycle if not managed carefully.
Understanding the Total Cost of Borrowing
Many borrowers make the mistake of only looking at the monthly payment. For example, a $500 loan with a $50 monthly payment sounds affordable. But if that loan lasts for twelve months, you have paid $600 for a $500 loan. That is a 20% increase in cost. Always ask for the “Total Repayment Amount” before you sign anything. This figure tells you exactly how much cash will have left your pocket by the time the debt is settled.
You should also be aware of the difference between APR (Annual Percentage Rate) and the nominal interest rate. The APR includes not just the interest you pay, but also the fees associated with getting the loan, like origination or processing fees. If you are comparing two lenders, the one with the lower APR is almost always the better deal, even if the other has a lower stated interest rate but higher upfront fees.
Steps to Prepare for a Loan Application
To increase your chances of approval and secure the best terms, follow these three preparation steps:
- Audit Your Documents: Gather your most recent pay stubs, W-2 forms, and utility bills. Lenders want to see proof of residency and a consistent stream of income. Having these ready to upload can speed up your approval from days to minutes.
- Check for Errors: Free services like AnnualCreditReport.com allow you to see what is in your file. If there is a mistake—such as a debt that has already been paid being listed as active—dispute it immediately. A single error can be the difference between a 620 score and a 650 score.
- Calculate Your Debt-to-Income (DTI) Ratio: Add up all your monthly debt obligations, like rent, car payments, and credit card minimums, and divide that by your gross monthly income. Most lenders prefer a DTI below 36-43%. Knowing this number helps you understand how much more debt you can realistically afford.
Navigating the Loan Process
Before you sign your name, take a deep breath and look at the fine print. It is easy to get caught up in the excitement of an instant approval, but the total cost of the loan is what matters most in the end. Always check the APR, not just the monthly payment, to see the true cost of borrowing.
One common mistake is ignoring the impact of late payments. Even if a lender is willing to work with your bad credit, a single missed payment can act like a stone in your shoe, causing pain for years to come. Always ensure the monthly installment fits comfortably within your existing budget, leaving room for groceries and rent. A “buffer” in your budget is your best defense against future emergencies.
Another pitfall is the “quick fix” trap. While payday loans like those from GadCapital can save you from a crisis today, they can lead to a mountain of debt tomorrow if you aren’t careful. Use them sparingly and only for true emergencies. If you can, try to build towards more stable, long-term options like credit unions or personal loans from established firms. Building a history of on-time payments is the most effective way to climb out of a credit hole and achieve long-term financial freedom.
-
The Best Lenders for Bad Credit Loans in Arizona: 2026 Top 5 Picks
The Best Lenders for Bad Credit Loans in Arizona: 2026 Top 5 Picks
Last updated: 2026-10-16
Surviving the Arizona heat is one thing, but facing a mountain of unexpected debt is a whole different beast. For many residents, a sudden dental emergency or a broken AC unit in the middle of a Phoenix summer can throw your entire budget into chaos. When your credit score isn’t exactly perfect, finding a lender that looks at your actual situation rather than just a number is essential.
Picking a lender involves more than just glancing at a single interest rate. You have to weigh how fast you get the cash against how much that debt will cost you over time. A low rate sounds great, but if the repayment period is too short, those monthly payments might squeeze your budget tight. On the flip side, a long-term loan might keep payments low but end up costing you thousands extra in total interest.
This list helps Arizona residents find quick relief without falling into predatory traps. We focused on lenders that provide real options for those in a tight spot. Whether you need to fix a car to get to work or cover an urgent repair, the speed of funding can change your financial trajectory.
- LendingPoint
- OneAZ Credit Union
- Arizona Zip Loan
- AmeriCash Loans
- Allegiance Credit Union
Evaluating Financial Options Across the Grand Canyon State
We built this list by looking at how accessible different lending models are for people with less-than-perfect credit. Speed was a major factor. In a state where life moves fast, waiting two weeks for cash isn’t a realistic option. If your car is your only way to get to your job, a three-day delay in funding could mean lost wages or even losing your position entirely.
Transparency matters just as much as the interest rate. A lender might promise a low rate, but if they require a pristine 750 credit score, that rate is essentially a ghost. We looked at the gap between traditional banks, which often demand mountains of paperwork and in-person visits, and digital lenders that process everything on a smartphone in minutes.
The following table gives you a quick look at how these top contenders stack up against each other regarding amounts and speed.
Lender Name Loan Amount Range Funding Speed Credit Requirements LendingPoint $1,000 – $36,500 See site See site OneAZ Credit Union See site See site See site Arizona Zip Loan $1,000 – $35,000 24hrs See site AmeriCash Loans See site Instant decision Good credit not needed Allegiance Credit Union See site See site See site Top Rated Lenders for Arizona Residents
1. LendingPoint
LendingPoint works well for people needing a significant chunk of cash for major life events. Whether you are planning a wedding or trying to consolidate a mountain of credit card debt, their platform handles a variety of needs. They offer different loan purposes to fit almost any financial emergency that pops up.
Since they handle larger sums, they are a popular choice for debt consolidation. This allows you to roll high-interest balances into a single, more manageable monthly payment. It can be a much simpler way to manage your monthly budget.
This lender is a good option if you want to check your eligibility without hurting your credit score. They use a soft credit pull for the initial quote. This means you can see your estimated rate and terms without any impact on your score before you commit to a formal application.
Pros:
- Flexible loan purposes including debt consolidation and travel.
- Check rates without impacting your credit score.
- High maximum loan amount of $36,500.
Cons:
- Specific eligibility requirements may vary.
2. OneAZ Credit Union
OneAZ Credit Union operates with a community-focused mindset that you rarely see at big corporate banks. They tend to focus on helping members reach long-term goals rather than just providing a quick fix. This makes them a solid choice if you want to build a real relationship with your lender.
Because credit unions are member-owned, their primary goal is to serve the community instead of maximizing shareholder profits. Unlike large national banks that treat you like a number on a spreadsheet, OneAZ offers a more personal touch. You might even find better service because they actually want you to succeed.
If you need more than just a one-time loan, they offer wealth management, mortgages, and financial coaching. It is a holistic approach that can help you move from just surviving to finding actual stability. They can help you create a savings plan so the next car repair doesn’t require a loan at all.
Pros:
- Comprehensive financial services and coaching.
- Potential for higher savings growth compared to national averages.
- Community-oriented membership benefits.
Cons:
- Membership requirements may apply.
3. Arizona Zip Loan
Speed is everything when you are dealing with an urgent crisis in Phoenix or Tucson. Arizona Zip Loan aims for an average approval time of just 24 hours. This is perfect for those facing immediate problems, like a broken water heater or a medical bill that needs to be paid right away.
They cater specifically to Arizona families, which gives them a localized feel that national websites often lack. Because they are rooted in the state, they understand the local economic reality. Their service is built to connect people with funds quickly and securely, closing the gap between an emergency and a solution.
Pros:
- Fast 24-hour average approval time.
- High customer rating of 4.9 stars.
- Wide geographic coverage across Arizona cities.
Cons:
- Strictly focused on personal loan structures.
4. AmeriCash Loans
AmeriCash Loans is built for anyone needing momentum right now. Their marketplace model connects you with lenders who are willing to look past a low credit score. It is a streamlined, digital-first approach for people in a rush who don’t want to waste time.
The application is incredibly straightforward. You only need to fill out a simple form to get things moving. You won’t find yourself stuck in complex menus or waiting on hold for an hour just to see if you qualify. It is a fast way to bridge a short-term cash gap.
This model is particularly helpful if you have a limited credit history or if a recent life event caused a temporary dip in your score. It removes the heavy lifting of contacting dozens of different lenders yourself.
Pros:
- Good credit is not a requirement for the marketplace.
- Fast application and instant decision process.
- Simple, secure digital interface.
Cons:
- Final terms are determined by third-party lenders.
5. Allegiance Credit Union
Allegiance Credit Union takes a very human approach to lending. They believe every financial story matters, whether you are buying your first home or rebuilding after a setback. This empathetic stance is a relief for those feeling discouraged by their credit history.
They understand that life is unpredictable and a temporary setback doesn’t have to define your entire financial future. They focus on supporting your well-being through various products. This is a lender for the long haul, helping you borrow smarter over time.
The goal is often to move you toward independence rather than just providing a temporary patch. This is helpful for people looking to graduate from small, high-interest loans to more stable credit lines as their financial health improves.
Pros:
- Mission-driven focus on financial well-being.
- Supportive environment for rebuilding credit.
- Variety of products for different life stages.
Cons:
- Geographic availability may be limited to specific regions.
Understanding the True Cost of Borrowing
Before you sign anything, remember that not all money is created equal. It is easy to get excited about an instant approval, but you must look at the total cost. When comparing two lenders, don’t just look at the interest rate. Look at the total amount you will have paid back by the time the loan is finished.
A 10% interest rate over 60 months is vastly more expensive than a 15% interest rate over 24 months. Always ask for the APR (Annual Percentage Rate) to see the true cost. The APR includes the interest rate plus mandatory fees, like origination or processing costs, which can drive up the actual price of the money.
If you borrow $5,000 but the lender charges a $300 origination fee, you only receive $4,700. However, you are still paying interest on the full $5,000. Understanding this simple math is your first line of defense against expensive debt.
How to Prepare for a Successful Loan Application
To increase your chances of approval and get the lowest rate, you need to be prepared. Even if your credit isn’t perfect, presenting yourself as a responsible borrower makes a difference to lenders. Follow these steps to get ready:
- Gather Documentation Early: Most lenders will want proof of identity, income, and residence. Have digital copies of your driver’s license, recent pay stubs, and a utility bill ready to upload to speed things up.
- Review Your Credit Report: You should know exactly what a lender sees. Check for errors or fraudulent activity that might be dragging your score down. Fixing a single mistaken late payment can sometimes jump your score enough to get a better rate.
- Calculate Your Debt-to-Income (DTI) Ratio: Lenders want to know if you can actually afford more debt. Divide your monthly debt payments by your gross monthly income. A lower ratio makes you a much more attractive candidate.
- Identify Your Specific Need: Be ready to explain exactly why you need the funds. Lenders are more comfortable when the purpose is clear and constructive, like home improvement or debt consolidation.
Avoiding Common Pitfalls in the Lending Process
Avoid the “quick fix” mentality. While a payday loan might solve a problem today, it can create a much larger crisis tomorrow if you aren’t careful. These loans often have extremely high interest rates and short repayment windows. This can force you into a cycle of taking new loans just to pay off old ones.
Make sure your monthly repayment fits comfortably within your existing budget. This prevents a debt cycle that feels impossible to escape. If the payment is a struggle every month, the loan is too big.
Lastly, verify that any lender reaching out is legitimate. Stick to well-known institutions or established marketplaces. Scams are common, especially when people are searching for quick cash. If a deal seems too good to be true, or if they demand upfront fees before releasing your funds, walk away. Legitimate lenders typically take their fees from the loan proceeds themselves.
-
Top 6 Lenders for HVAC AC Financing Options in 2026
Top 6 Lenders for HVAC AC Financing Options in 2026
Last updated: 2026-10-16
When summer heat waves hit or winter chill seeps through the floorboards, a broken HVAC system feels like a sudden emergency. Most homeowners do not have several thousand dollars sitting in a drawer ready to cover a brand-new condenser unit or a furnace replacement. Specialized financing steps in to bridge the gap between a broken unit and a comfortable home.
Choosing the right way to pay for these essential repairs requires looking beyond just the monthly payment. You have to weigh the speed of funding against the long-term cost of interest and the potential impact on your credit score. This list examines various providers to help you find a path that fits your immediate budget and your long-term financial health.
- Hearth
- JetzLoan
- Flexxbuy
- AmeriCash Loans
- Roadrunner Financial
- NetCredit
The Standards for Evaluating HVAC Financing Providers
Finding a lender for home climate control is not like shopping for a car or a small personal loan. HVAC projects are often urgent. If your furnace dies in January, you cannot afford to wait two weeks for a bank to review your paperwork and verify your income.
The comparison below focuses on how quickly funds become available and what kind of credit profile is required to get through the door. Some lenders focus on high-ticket installment loans. Others specialize in quick, short-term advances or lease-to-own models for those with limited credit history. The goal is to match the lender’s strengths to the specific urgency of the repair.
Lender Name Max Loan Amount Funding Speed Credit Requirements Hearth see site see site see site JetzLoan $35,000 As little as 24 hours No hard credit pull Flexxbuy $100,000 Next business day Credit Select (35+ lenders) AmeriCash Loans see site Instant decision Good credit not needed Roadrunner Financial see site Two minutes All credit welcome NetCredit $10,000 Same-day funding available Flexible terms 1. Hearth
Hearth operates as a specialized resource for those looking to optimize their home energy efficiency. While many lenders focus purely on the money, this platform provides a deep well of information regarding wood stoves, pellet stoves, and various energy-saving equipment. It acts as a community hub for those wanting to make responsible, clean, and safe fuel choices.
This is an ideal choice for the homeowner who wants to do their homework before committing to a major installation. Instead of just looking at a loan, you can dive into forums and discussions to understand the long-term benefits of the equipment you are financing. It is a knowledge-first approach to home improvement.
Pros:
- Extensive community forums for technical advice.
- Focus on energy-efficient and sustainable equipment.
- Valuable historical data on various heating fuels.
Cons:
- More of an information and advice resource than a direct lender.
2. JetzLoan
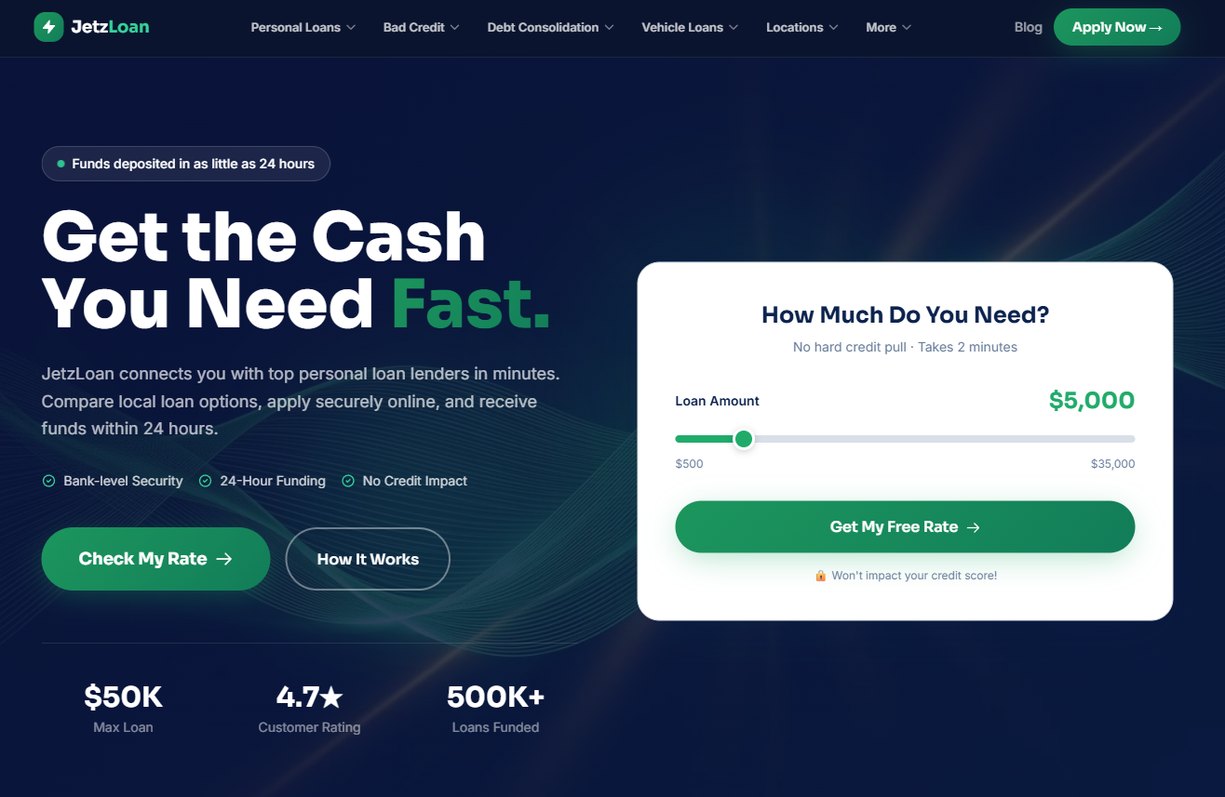
Time is of the essence when your living room feels like a sauna. JetzLoan is built for the person who needs cash in their bank account yesterday. They focus on speed and simplicity, connecting users with top lenders in just a few minutes without the dread of a hard credit pull during the initial phase.
The process is streamlined to prevent the headache of endless paperwork. With the ability to receive funds in as little as 24 hours, it serves as a high-speed bridge for those facing sudden equipment failures. It is a straightforward solution for those who prioritize velocity over complex financial maneuvering.
Pros:
- No hard credit pull during the initial rate check.
- Extremely fast funding, potentially within 24 hours.
- High maximum loan amount of up to $35,000.
Cons:
- The speed of funding may depend on the specific lender matched.
3. Flexxbuy
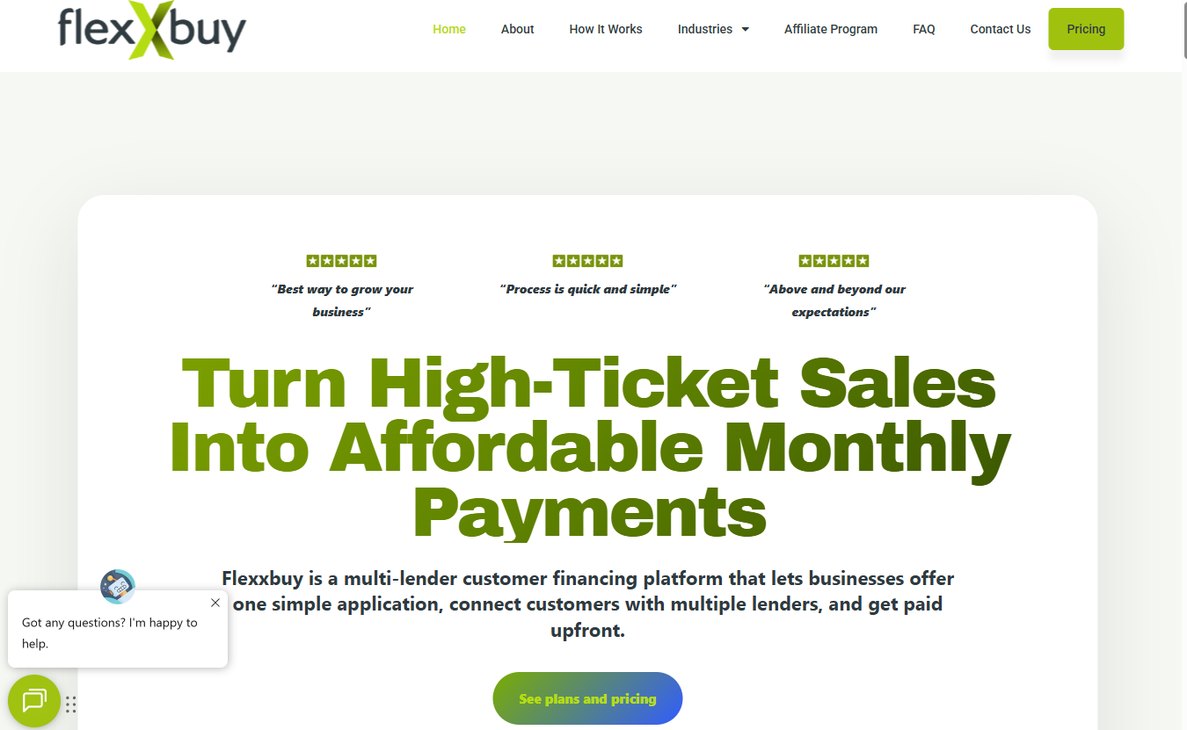
For businesses and contractors installing expensive high-ticket HVAC systems, Flexxbuy offers a sophisticated way to close sales. They act as a multi-lender platform that allows customers to see several options through a single application. This turns a massive, intimidating price tag into manageable monthly installments that are much easier to swallow.
It is a powerful tool for scaling a business by making it easier for customers to say yes to premium equipment. With loan amounts reaching up to $100,000, it handles the heavy lifting for major commercial or residential installations. The speed of decision-making is designed to keep the project moving forward without delay.
Pros:
- High loan limits up to $100,000.
- Decisions are made in seconds.
- Access to a wide network of over 35 lenders.
Cons:
- Primarily designed for businesses to offer to their customers.
4. AmeriCash Loans
Sometimes, the traditional banking route is a closed door. AmeriCash Loans is designed for those who need momentum immediately and might not qualify for standard bank loans. They specialize in short-term cash advances and marketplace lending, making it easier for people to find a lender that fits their specific situation.
The application is built to be simple and secure, moving through a marketplace to find a match. It is a fallback option for those who need to act now but may have a less-than-perfect credit history. While it is a marketplace rather than a single lender, it provides a path to quick decisions.
Pros:
- Instant approval decisions are possible.
- Good credit is not a strict requirement.
- Simple, user-friendly application process.
Cons:
- Terms and requirements are determined by individual lenders in the marketplace.
5. Roadrunner Financial
Roadrunner Financial offers a highly specialized approach to financing, often focusing on various types of vehicle and recreational equipment. However, their “all credit welcome” philosophy makes them a versatile option for those looking for quick, personalized loan offers. They aim to remove the haggling and hassle typically found at the point of sale.
The prequalification process is incredibly fast, taking only about two minutes. This allows you to see what you might qualify for without any commitment or impact on your credit score. It is a low-pressure way to gauge your options before you commit to a major purchase or repair.
Pros:
- No impact on credit score during prequalification.
- Very fast, two-minute process.
- Welcomes all credit scores.
Cons:
- The service is heavily geared toward specific vehicle/recreational types.
6. NetCredit
NetCredit positions itself as a modern alternative to traditional banking, operating under the philosophy that you are more than just a number in a database. They offer personal loans and lines of credit that provide a level of flexibility that many rigid banks simply cannot match. It is a human-centric approach to digital lending.
If you need a loan up to $10,000 to get your AC running again, NetCredit provides a path with the potential for same-day funding. Their use of advanced algorithms allows for a more nuanced view of your ability to repay, which can be a lifesaver for those who fall just outside the standard FICO requirements.
Pros:
- Potential for same-day funding.
- Flexible terms and loan amounts up to $10,000.
- A more nuanced approach to credit assessment.
Cons:
- Loan availability is subject to state-specific regulations and partnerships.
Navigating Your Financing Options
When you are staring at a broken air conditioner in the middle of a heatwave, it is easy to make a rushed decision. Avoid the mistake of signing a lease-to-own agreement without understanding if you would be better off with a traditional loan. While lease-to-own can be easier to get, it is often much more expensive over the life of the agreement.
Always ask for a total cost of ownership breakdown. A low monthly payment might look attractive on the surface, but if the term is 96 months, you could end up paying for the unit three times over. Compare the interest rates across multiple providers and always check for any hidden fees that might sneak into the contract at the last minute.
Another common pitfall is failing to verify the credentials of the contractor alongside the lender. A great financing deal is wasted if the technician installing the unit is not licensed or insured. Ensure that the financing is tied to a reputable professional who provides a clear, written estimate before you sign any loan documents.
-
The 6 Best Lenders for Bad Credit Loans in Pennsylvania for 2026
The 6 Best Lenders for Bad Credit Loans in Pennsylvania for 2026
Last updated: 2026-10-16
Life rarely gives you a heads-up when things go wrong. One minute you are driving through Allentown on a rainy Tuesday, and the next, your transmission gives out completely. Maybe an unexpected ER visit leaves you staring at a medical bill you didn’t see coming, or a sudden Pennsylvania winter sends your heating costs through the roof. These hiccups are stressful enough, but they become a nightmare when a low credit score stands between you and the cash you need to keep the lights on.
When past late payments or high credit card balances have bruised your FICO score, traditional banks often shut their doors. They act more like gatekeepers than helpers, leaving many residents to hunt for alternative lifelines. This is where subprime lending enters the picture, and it requires a sharp eye. You have to be careful, because the goal is to find a solution that doesn’t create a whole new crisis next month.
When you are looking for quick cash, your priorities usually shift. You might stop worrying about finding the absolute lowest interest rate and start focusing simply on finding a lender willing to say yes to your financial history. It is a survival tactic, certainly, but it demands a strategic approach to stay ahead of the curve.
- GadCapital
- FastLendGo
- Credit Human
- GreendayOnline
- Loanz
- OppLoans
Evaluating Lending Options Across the Keystone State
Finding a decent lender in Pennsylvania means looking past the flashy social media ads or the bright neon signs in busy city streets. You need to know how they handle credit checks, how fast the money actually hits your bank account, and what the loan amounts look like when you are in a pinch. A resident in Erie likely has different needs than someone living in Philadelphia.
A commuter might just need a quick loan for an auto repair to get to work. On the other hand, a small business owner might need a bridge loan to cover payroll until the next big contract clears. This ranking looks at the specific needs of people facing these kinds of emergencies. We looked at how quickly funds arrive and whether they offer installment-based options.
Avoiding the debt trap is the real goal. A payday loan that requires full repayment in just fourteen days can easily turn into a cycle of endless renewals. Installment loans are often a better bet because they offer a predictable repayment schedule that fits much better with a standard monthly paycheck. It is the difference between a temporary fix and a long-term struggle.
Lender Name Loan Amounts Credit Requirements Funding Speed GadCapital $100 – $5000+ No Credit Check Instant/Same Day FastLendGo $500 – $5000+ Bad Credit Welcome Quick Access Credit Human From $500 No Credit Review See Site GreendayOnline $100 – $5000 No Hard Credit Check Same Day Loanz $100 – $10000 See Site Quick/Convenient OppLoans See Site Does not affect FICO Same-Day Funding 1. GadCapital
GadCapital acts as a direct lifeline for people facing immediate financial trouble. They offer options that don’t require a traditional credit check, which is perfect for a Pittsburgh resident who needs cash right now to pay an overdue rent bill or an urgent utility charge. Their model moves much faster than the slow, bureaucratic verification processes at big national banks.
The platform handles everything from small $100 advances to larger sums over $5000. This flexibility matters. A $100 loan might cover a tank of gas and a few groceries, while a $5000 loan could fix a major emergency repair. It is a specialized choice for those who need to bypass the long scrutiny of conventional banks and need an instant digital response.
Pros:- No credit checks required for many options
- High maximum loan amounts up to $5000+
- Fast, instant online application process
- High urgency can lead to expensive terms
2. FastLendGo
FastLendGo is a versatile partner for various personal financing needs. They don’t just look at one type of borrower, either. They offer solutions for auto repairs, dental bills, and even roof repairs. This variety makes them a useful starting point for anyone unsure which specific product will fit their situation. (fastlendgo.com)
Whether you need a $500 boost to get to your next paycheck or a $5000 personal loan to consolidate high-interest debts, they aim to make comparing local options simple. This is a great fit for people facing specific household emergencies, like an HVAC unit failing during a humid Pennsylvania summer.
Pros:- Wide variety of loan purposes
- Handles various credit scores from fair to bad
- Streamlined online comparison tool
- Focuses on comparison rather than direct lending
3. Credit Human
If you prefer the stability of a member-owned institution, Credit Human offers a different approach. They provide both secured and unsecured options, allowing members to borrow as little as $500 with more traditional repayment structures. Because they operate as a credit union, they tend to focus more on your ability to repay rather than just a number on a report.
This is a good choice for a long-term planner who wants to build financial health while solving a current problem. Their terms can go up to 72 months, which makes monthly payments much easier to handle on a tight budget. Instead of a massive lump sum due in two weeks, you might pay a small, manageable amount every month to keep your cash flow steady.
Pros:- Member-owned structure supports community values
- Flexible repayment terms up to 72 months
- No credit review on certain products
- Requires membership to access most benefits
4. GreendayOnline
GreendayOnline is built for speed. If you are staring at a pile of bills and need an answer fast, this platform moves through the process in minutes. Their digital interface works well on mobile phones, which is helpful since many people in a pinch might be accessing these services on the go via a smartphone.
They offer installment loans from $100 up to $5000. Because they avoid hard credit checks, you can find out where you stand without hurting your credit score further. This “soft pull” approach lets you see your options before you make a final commitment, which is vital if you are cautious about your financial standing.
Pros:- Fast approval decisions
- No hard credit checks required
- Funds can arrive as soon as the same day
- Strictly online process may lack personal touch
5. Loanz
Loanz focuses on debt consolidation. If your financial struggle comes from juggling too many different monthly payments—like multiple credit cards and a medical bill—this lender helps you pull those into one manageable slice. By consolidating, you trade several chaotic due dates for one single, predictable payment.
With loan amounts up to $10,000, they offer a way to regain some control. It is a strategic choice for someone looking to reorganize their financial future rather than just looking for a quick fix. Instead of just trying to “get by,” you are working toward a more organized life.
Pros:- Strong focus on debt consolidation
- Higher loan limits up to $10,000
- Versatile for weddings, travel, or home improvements
- May require more documentation for higher amounts
6. OppLoans
OppLoans works through a network of bank partners. One of their most useful features is the ability to apply without affecting your FICO score. That is a huge relief for anyone watching their rating closely. Most lenders perform a “hard inquiry” that can drop your score, but OppLoans avoids that during the initial phase.
They offer same-day funding for people in a bind. It is a practical option for a consumer who needs a quick bridge to reach their next paycheck without the stress of a hard inquiry. This makes them a strong choice for short-term gaps that only require a few hundred or a few thousand dollars.
Pros:- Applying does not impact FICO scores
- Same-day funding availability
- Simple and transparent application process
- Approval is based on bank partner criteria
The True Cost of Subprime Borrowing
Check the math before you sign anything. Subprime lending usually carries higher Annual Percentage Rates (APRs) than traditional loans. A 10% APR might be normal for a prime borrower, but subprime rates can be much higher. This isn’t a scam, it’s just a reflection of the risk the lender takes by lending to someone with a history of late payments.
Don’t just look at the monthly payment. If you borrow $1,000 and the payment is $150, it looks affordable. But if you pay that for 12 months, you’ve paid $1,800 total. That $800 difference is the price of convenience. Always use an APR calculator to see the total cost of the loan over its entire life to avoid sticker shock at the end.
How to Apply Safely
To keep your debt manageable and increase your chances of getting approved, follow these steps:
- Identify the Exact Need: Figure out exactly how much you need. Borrowing $2,000 when you only need $1,200 is a mistake that just increases your interest costs.
- Check Your Score First: Use a free service to see your own score. This helps you decide if you need a “no credit check” option or if you can qualify for a cheaper, traditional loan.
- Compare the Total Cost: Look at the “Total Repayment Amount” rather than just the “Monthly Payment” to see the real impact on your wallet.
- Read the Repayment Schedule: Make sure the due dates align with when you get paid. If you get paid on the 1st and 15th, a loan due on the 22nd might cause problems.
- Verify the Lender’s Credentials: Make sure you are on a secure site with “https” and the padlock icon before you enter any sensitive bank details.
Lending in Pennsylvania
Choosing a lender shouldn’t be a whim. While instant cash sounds great, you have to read the fine print. A loan that solves a $500 problem today could become a $5,000 problem next year if you don’t understand the terms. The difference between an installment loan and a payday loan is the difference between a controlled climb and a freefall.
Don’t just focus on how fast the deposit arrives. Check if the lender uses hard or soft credit pulls. If you are already struggling, the last thing you want is another hard inquiry on your report. Too many inquiries in a short time can signal to banks that you are desperate for cash, which can drive your score down even further.
Think about why you need the money. If you are consolidating debt, a long-term installment loan like those from Loanz might be smarter than a high-interest payday advance. Match the tool to the task. Use short-term tools for quick gaps, and use long-term tools for structural financial changes.
-
Top 5 Lenders for Manufactured Home Financing in 2026
Top 5 Lenders for Manufactured Home Financing in 2026
Last updated: 2026-10-16
Finding the right way to pay for a manufactured home can feel like walking through a thick fog. Some people look for the stability of government-backed programs. Others need the quick turnaround of a private lender to secure a specific lot before someone else grabs it. Choosing the wrong path often leads to higher interest rates or unexpected hurdles that complicate your move.
Consider a buyer who secures a low monthly payment on a high-interest personal loan. They might not realize until years later that the total interest paid over five years far exceeds the cost of a traditional mortgage. It is a costly mistake that many avoid by doing their homework early.
What matters most is matching your current financial profile to the right product. Whether you are working to repair a credit score or looking for a quick cash injection for a down payment, the market in 2026 offers various specialized options. Understanding these nuances is the first step toward securing your piece of the American dream.
This requires looking closely at how different lenders view risk. You also need to see how they value collateral and how quickly they can move from application to closing. Every detail counts when you are trying to make a major purchase like this.
- FHA
- MH Communities
- JetzLoan
- Roadrunner Financial
- Yanmar
Evaluating the Current Financing Landscape
Selecting a lender requires looking beyond the monthly payment. You have to assess how quickly funds arrive and what the entry requirements are for your specific credit tier. Some lenders focus on long-term stability through strict underwriting. Others prioritize speed and accessibility for those who might otherwise be denied traditional bank loans.
A consumer with a 620 FICO score might find themselves rejected by a conventional mortgage provider. However, they might be welcomed by a specialized subprime lender that understands the unique depreciation curves of manufactured housing. These specialized lenders see potential where big banks only see risk.
The criteria used for this ranking include loan accessibility, maximum funding limits, and the speed of the approval process. We looked at how these providers handle different credit scenarios, from those with established histories to those facing recent financial setbacks.
We analyzed the delta between “soft” and “hard” credit inquiries, the required documentation for income verification, and the regional availability of certain specialized programs. This ensures a balanced view of who serves the widest range of manufactured housing seekers, from the first-time buyer to the seasoned investor.
Lender Name Max Loan Amount Funding Speed Credit Requirements FHA $350,000 see site 640 FICO MH Communities see site see site see site JetzLoan $50,000 24 hours No hard pull Roadrunner Financial see site see site All credit welcome Yanmar see site see site see site Top-Rated Financing Options
1. FHA
FHA loans are a cornerstone for those looking to secure a manufactured home with a government-backed safety net. These loans help make housing more accessible to Americans by providing structured guidelines and established underwriting standards. Because the Federal Housing Administration insures the lender against loss in the event of default, these loans often carry lower down payment requirements.
They can also offer more forgiving credit standards than conventional loans. This makes them a reliable choice for those who meet specific eligibility criteria. It is a solid path if you want the peace of mind that comes with government oversight.
This option is particularly suited for buyers who have a solid credit foundation but might not qualify for conventional mortgage products. For example, if you have a stable job but have a high debt-to-income ratio due to student loans, an FHA loan might offer the flexibility needed to get approved.
With a minimum FICO score requirement of 640 and a down payment around 10%, it provides a clear roadmap for long-term homeownership. However, remember that FHA loans often require the home to be permanently affixed to a foundation. They must also be located on land owned by the borrower, rather than in a rental park where you only lease the lot.
Pros:
- Established government-backed security
- Maximum loan amounts up to $350,000
- Standardized underwriting processes
Cons:
- Requires a minimum 640 FICO score
- Minimum 10% down payment required
2. MH Communities
MH Communities focuses on the human element of housing. They emphasize community living over simple transactions. They specialize in managing mobile home parks and apartment communities that aim to foster a sense of belonging. Their approach is built around providing affordable, well-maintained spaces for families and retirees alike.
Unlike a traditional bank that only sees a loan amount, MH Communities sees a resident who needs a stable environment to thrive. They treat their properties as neighborhoods rather than just sets of assets on a spreadsheet.
This is an ideal choice for individuals looking for more than just a loan. They are looking for a place to plant roots. Their management style focuses on creating safe, inviting environments where residents can find connection and peace of mind in their everyday lives.
By managing the land and the community infrastructure, they provide a layer of predictability that is often missing in private lot rentals. If you are looking to move into a community with pre-established amenities like playgrounds, paved roads, and community centers, this is a primary resource for finding your next home.
Pros:
- Focus on community-centric living
- Professional management services
- Varied housing options from apartments to parks
Cons:
- Focus is on community management rather than direct lending
- Availability is regional to the Midwest
3. JetzLoan
When time is of the essence, JetzLoan steps into the ring with an emphasis on speed and simplicity. They connect borrowers with top lenders in a matter of minutes. This makes the process feel less like a mountain of paperwork and more like a quick digital transaction.
It is built for the modern, fast-paced world. Opportunities like a well-priced home might only stay on the market for a few days. In those moments, you cannot afford to wait weeks for a bank to call you back.
This service is perfect for someone needing a quick injection of cash. Perhaps you need to cover closing costs, a sudden repair, or a small gap in funding that would otherwise derail a larger purchase. While a traditional mortgage might take 30 to 45 days to close, JetzLoan targets a much tighter window.
With the ability to receive funds in as little as 24 hours, it removes the agonizing wait that often plagues traditional mortgage applications. This allows you to act with the confidence of a cash buyer in certain negotiations.
Pros:
- Extremely fast 24-hour funding
- No hard credit pull to check rates
- Simple, two-minute application process
Cons:
- Loan amounts capped at $50,000
- Primarily personal loans rather than specific home mortgages
4. Roadrunner Financial
Roadrunner Financial operates with a focus on flexibility and accessibility. They welcome a wide spectrum of credit scores. They aim to strip away the haggling and hassles often found at dealerships or large banks. Their process is designed to be quick, providing real-time decisions that don’t impact your credit score during the initial inquiry phase.
This is particularly helpful for those who are still testing their budget. You can see what you can afford before committing to a formal application. It takes the guesswork out of the early stages of shopping.
This lender is a strong fit for those who want to move quickly on a purchase and need personalized offers. Because their rates are valid for 30 days, it gives the consumer a window of time to make an informed decision without feeling immediate pressure.
If you are shopping for a manufactured home at a dealership and need an answer before you leave the lot, Roadrunner’s model is built to accommodate that urgency. They maintain a level of transparency in their rate offerings that makes the whole experience easier.
Pros:
- All credit scores are welcome
- No impact on credit score during prequalification
- Competitive rates valid for 30 days
Cons:
- Focus is primarily on powersports and vehicle types
- Decisioning is heavily tied to dealership environments
5. Yanmar
Yanmar represents a global presence with a diverse reach across many different international markets. Their operations span from Europe to Southeast Asia, reflecting a massive organizational footprint. They provide a structured, corporate approach to their various business interests and regional services.
When dealing with a brand of this magnitude, you are interacting with a highly standardized system of operations. This can bring a certain level of predictability to the table, even if the scale is vast.
While they operate on a massive scale, their presence is most felt in providing specialized equipment and regional business solutions. For a consumer looking for a highly structured international brand, Yanmar offers a level of professional consistency that is hard to find in smaller, local entities.
While they may not be the first name you think of when looking for a home loan, their influence on the global supply chain and industrial equipment sectors is significant. They represent the standard for large-scale corporate efficiency and reliability.
Pros:
- Extensive global presence and brand recognition
- Highly structured regional operations
- Broad international reach
Cons:
- Not a specialized manufactured home lender
- Extremely broad focus may lack personal touch
Understanding Loan Types: Chattel vs. Mortgage
One of the most critical distinctions in manufactured housing finance is the difference between a chattel loan and a traditional mortgage. If you are buying a home that is still in its original packaging or is not permanently attached to a foundation, you will likely be looking at a chattel loan. This is a loan secured by the home itself, similar to how an auto loan works.
Because the home is considered personal property rather than real estate, interest rates are typically higher. You might also see larger down payments. It is a vital distinction to understand before you sign anything.
In contrast, a traditional mortgage covers both the home and the land it sits on. This requires the home to be legally classified as real property. This usually means it is permanently affixed to a foundation and the title has been legally converted.
Understanding this distinction is vital because it impacts your long-term equity. A mortgage allows you to build equity in the land, which historically appreciates. A chattel loan is tied to an asset that may depreciate over time. Always confirm with your lender whether they are financing the structure, the land, or both.
Step-by-Step: Preparing for Your Application
To ensure a smooth approval process, follow these strategic steps to prepare your financial profile before engaging with lenders:
- Step 1: Audit Your Credit Report. Obtain a free copy of your credit report from all three major bureaus. Look for errors, such as incorrectly reported late payments or accounts that don’t belong to you. Disputing these errors now can save you significant interest over the life of your loan.
- Step 2: Calculate Your Debt-to-Income (DTI) Ratio. Lenders look closely at how much of your monthly gross income goes toward debt payments (car loans, student loans, credit cards). Aim to keep this ratio below 36% to qualify for the best rates.
- Step 3: Gather Documentation. Be ready to provide the last two years of W-2 forms, the last two months of bank statements, and your most recent pay stubs. If you are self-employed, you will likely need two years of tax returns to prove consistent income.
- Step 4: Verify the Home’s Compliance. Ensure the manufactured home meets HUD (Department of Housing and Urban Development) standards. Lenders will require a professional inspection to verify that the home is structurally sound and meets all local safety codes.
- Step 5: Shop Around with Soft Pulls. Use lenders like Roadrunner Financial or JetzLoan to check your eligibility without hurting your credit score. Comparing at least three different quotes is the only way to ensure you aren’t overpaying.
Avoiding common pitfalls starts with knowing your numbers before you walk into any meeting. Many buyers make the mistake of applying for multiple loans simultaneously, which can inadvertently damage their credit profile. It is always better to use “soft pull” tools that allow you to compare rates without any risk to your score.
Another trap is overlooking the fine print regarding the type of loan you are receiving. There is a massive difference between a chattel loan, which is secured by the mobile home itself, and a traditional mortgage, which covers both the home and the land. Make sure you understand exactly what you are paying for before signing any binding documents.
Finally, keep an eye on the total cost of ownership rather than just the monthly payment. A lower monthly payment might seem attractive, but a longer term can result in paying thousands more in interest over the life of the loan. Always run the math on the total interest to ensure your housing choice remains affordable in the long run.