Your cart is currently empty!
Category: Uncategorized
-
Top 6 Lenders for RV Loans for Bad Credit in 2026
Top 6 Lenders for RV Loans for Bad Credit in 2026
Last updated: 2026-10-16
Hitting the open road is a dream for many, but a bruised credit score can feel like a heavy anchor. If you find yourself staring at a beautiful motorhome while your credit report looks a bit ragged, securing the funds might feel out of reach. The gap between a “maybe” and a “yes” often comes down to how lenders view risk and how much cash you can put down upfront.
Finding the right lender involves more than just chasing the lowest interest rate. You need to weigh approval odds against down payment requirements and how fast the money actually moves. Whether you want a vintage Airstream or a modern diesel pusher, the financing options are vast. This breakdown looks at the top contenders to help you find the right fit for your specific situation.
- Alliant Credit Union
- FastLendGo
- RV Depot
- U.S. Bank
- My Financing USA
- Acorn Finance
How the Best RV Lenders Were Evaluated
Picking a winner in subprime financing is never a simple task. Our comparison focused on accessibility for people with non-traditional credit histories. We looked at lenders that specifically offer programs for individuals with scores in the 550 range or lower to ensure they actually serve that audience. It wasn’t enough to find lenders who say “yes”; we wanted those who offer reasonable terms that won’t trap you in a cycle of debt.
Flexibility matters just as much as the interest rate. We checked whether lenders allow private party sales or if they strictly require dealership transactions. If you find a gem on Facebook Marketplace or Craigslist, many traditional banks will refuse to fund the deal because they cannot verify the title or the vehicle’s condition through an official dealer network. Speed is also vital, as waiting weeks for an answer can mean losing a great deal from a private seller.
The total cost of ownership was our final metric. This includes the APR and the impact on your credit score during the application phase. A lender that requires a “hard pull” for every single inquiry can tank a low score before you even secure a vehicle. Conversely, a marketplace that uses a “soft pull” allows you to shop around without any risk to your rating.
Lender Name Credit Requirements Loan Minimum Key Feature Speed/Terms Alliant Credit Union see site see site Same-day approval see site FastLendGo Bad/Fair Credit $500 Personal loan options see site RV Depot All credit types see site In-house financing 6-month warranty U.S. Bank see site see site Online pre-approval see site My Financing USA 550+ Score $10,000 10-15% Down payment see site Acorn Finance Good & Bad Credit see site No credit impact check see site 1. Alliant Credit Union
Alliant Credit Union is a solid choice for anyone wanting to avoid the bureaucratic headache that often comes with big banks. Their rates typically beat the industry average, making them a refreshing alternative for members looking to upgrade their lifestyle without a massive price tag. As a credit union, they focus on member benefits rather than maximizing shareholder dividends, which often leads to more empathetic lending for those with less-than-perfect scores.
This lender works well for organized borrowers who need to move fast. They offer same-day approval in most cases, which is a lifesaver if you find a perfect used RV on a weekend and need to move before someone else snaps it up. To make this work, have your pay stubs, tax returns, and proof of residence ready to upload immediately.
Pros:
- Competitive rates that beat industry averages.
- Extremely fast approval process.
- Membership-based benefits.
Cons:
- Membership requirements may apply.
2. FastLendGo
If you need quick cash for smaller expenses or perhaps a down payment, FastLendGo is a versatile option. They specialize in personal financing solutions that help people who struggle to find traditional bank support locally. Since these personal loans are often unsecured, you aren’t tied to a specific VIN or title. You can use the cash for anything, from a motorhome down payment to a new generator or solar setup.
They cater to a wide spectrum of needs, offering anything from $500 loans to larger sums for high-income individuals. This flexibility helps if you are just trying to piece together the funds needed for a used camper or travel trailer. Using a FastLendGo loan to pay down high-interest credit card debt can actually improve your credit profile before you apply for a major vehicle loan later.
Pros:
- Wide range of loan amounts starting at $500.
- Options for various credit levels.
- Easy online comparison.
Cons:
- Personal loans may have different terms than secured RV loans.
3. RV Depot
RV Depot takes a hands-on approach through their in-house financing. They don’t care if your credit is perfect or a complete mess; they provide financing for all credit types. Because they handle the financing themselves, the communication between the seller and the lender is direct. You won’t have to act as a middleman passing paperwork back and forth between a bank and a dealership, which often leads to delays.
The real standout here is the peace of mind they offer. Beyond the loan, they include a 6-month warranty on their vehicles. This is a huge advantage for used buyers, as it mitigates the fear of a mechanical breakdown immediately after purchase. A broken water pump or an electrical issue in the first month can be a massive financial drain that eats into your travel budget.
Pros:
- In-house financing available for all credit types.
- Includes a 6-month warranty.
- Simplified buying process.
Cons:
- Limited to their specific inventory.
4. U.S. Bank
For those who prefer the stability of a massive institution, U.S. Bank offers a streamlined digital experience. Their pre-approval process lets you shop with confidence, knowing exactly what your monthly payment will look like before you step onto a lot. This tool provides a “shopping budget” you can hand to a dealer to signal that you are a serious buyer with verified funds.
This is an ideal choice for the cautious shopper who wants to do the heavy lifting from a smartphone. Knowing your borrowing power in advance prevents the embarrassment of falling in love with an RV only to realize you can’t afford it. This is especially important in a high-interest-rate environment where even a 1% difference in APR can result in thousands of dollars of difference over a five-year term.
Pros:
- Convenient online pre-approval.
- Established, reputable institution.
- Digital-first application process.
Cons:
- Stricter credit requirements than specialized subprime lenders.
5. My Financing USA
My Financing USA is a specialist that knows the RV world inside and out. They don’t just look at your credit score; they look at the vehicle itself. They offer everything from fifth-wheel loans to toy hauler and camper van financing. They understand that an RV is a lifestyle asset and a depreciating asset at the same time, so they tailor their underwriting accordingly.
To qualify, you generally need a credit score of at least 550 and a down payment between 10% and 15%. This makes them a great option for someone with a steady job and some savings who just needs a little extra help to get on the road. If you have $5,000 saved and are looking at a $30,000 trailer, My Financing USA is more likely to approve you than a standard bank demanding 30% down.
Pros:
- Specialized in many different types of RVs.
- National search for the best programs.
- Clear requirements for bad credit.
Cons:
- Requires a minimum 10-15% down payment.
6. Acorn Finance
Acorn Finance functions as a marketplace, connecting you with various lenders without the usual headache. They are unique because they offer a way to check personalized rates without any negative impact on your credit score. This “soft inquiry” method allows you to see a range of potential rates and terms from multiple lenders simultaneously, giving you the leverage to choose the best deal.
This is a fantastic tool if you are worried about your score dropping further. It allows you to shop for financing with total transparency and zero risk to your rating. If you need to renovate your current home to make it more accessible before you head out on your travels, or if you need a loan for a new campsite pad, Acorn Finance is a versatile tool for your financial toolkit.
Pros:
- No credit score impact when checking rates.
- Highly rated by actual users.
- Free to use for borrowers.
Cons:
- Acts as a middleman rather than a direct lender.
Common Pitfalls in RV Financing
Many first-time buyers make the mistake of focusing solely on the monthly payment. While you must ensure the cost fits your budget, a lower monthly payment often means a much longer term. For instance, a 10-year loan instead of a 5-year loan might feel comfortable today, but you will end up paying tens of thousands more in interest over the life of the loan. You also risk becoming “upside down” on the loan, where the amount you owe is higher than the actual resale value.
Another pitfall is neglecting the total cost of ownership beyond the loan itself. When calculating what you can afford, you must account for:
- Insurance: RV insurance is typically more expensive than standard auto insurance.
- Storage: If you don’t have a large driveway, monthly storage fees add up quickly.
- Maintenance: RVs are high-maintenance. Budget for annual inspections, tires, and plumbing repairs.
- Fuel and Campsites: Fuel consumption for a large motorhome is significant, and premium campsites can cost $50-$100 per night.
Preparing Your Application for Approval
If you know your credit isn’t in top shape, don’t walk into a lender’s office blindly. Being prepared can turn a rejection into an approval. Follow these steps to increase your odds:
- Review Your Report: Get a free copy of your credit report. Look for errors or outdated negative marks. Disputing an incorrect late payment can boost your score significantly in a single cycle.
- Gather Documentation: Lenders want to see stability. Have your last three months of pay stubs, your last two years of W-2s, and your most recent bank statements ready.
- Build a Down Payment: This is the single most effective way to offset a low credit score. A larger down payment reduces the lender’s risk, making them much more willing to approve a subprime borrower.
- Check Your Debt-to-Income Ratio (DTI): Lenders look at how much of your monthly income goes toward existing debt. If you can pay down a small credit card balance before applying, you might lower your DTI enough to qualify for better terms.
Navigating the road ahead requires more than just a map; it requires a solid financial foundation. When you are staring down a large debt, the temptation to sign anything just to get the keys is strong. Avoid the trap of only looking at the monthly payment. A lower payment often means a much longer term, which results in you paying much more in interest over time.
Always double-check the fine print regarding late fees and prepayment penalties. Some lenders will punish you for being responsible and paying the loan off early. Make sure your chosen lender rewards your progress rather than penalizing it, so your path to ownership is as smooth as possible.
-
Top 7 Lenders for Subprime Personal Loans in 2026
Top 7 Lenders for Subprime Personal Loans in 2026
Last updated: 2026-10-16
Trying to fix your credit can feel like wandering through a thick fog. When your score isn’t where it needs to be, finding a way out often feels impossible. Many people find themselves stuck in a loop, searching for a way to bridge the gap between their current bank balance and their long-term goals.
Finding a lender that looks past your credit score to the person underneath is a vital first step. You shouldn’t just grab the first interest rate you see in a headline. You have to weigh how fast you get the cash against what the loan will actually cost you in the end.
Speed matters when a car breaks down or a medical bill arrives unexpectedly. However, long-term affordability is what keeps your head above water when those monthly payments finally start rolling in. Because everyone’s financial life is different, a one-size-fits-all approach rarely works.
- JetzLoan
- Avant
- OneMain Financial
- OppLoans
- LightStream
- Hearth
- USPS Federal Credit Union
How These Lenders Were Evaluated
We focused on how easy it is for people with less-than-perfect credit to get a seat at the table. A huge part of this was looking for lenders that allow you to get a quote without a hard credit pull. This keeps your score from taking a hit while you are just window shopping.
We also poked and prodded how transparent these companies are about their fees. We looked at how quickly the money actually lands in your bank account and how much they are willing to lend. Nobody wants to find out about a hidden fee after the money is already spent.
Application simplicity was a major factor in our decision. If you are facing an emergency, waiting a week for funds is not an option. We checked to see if the application was a digital marathon or a quick sprint through a few simple questions to get you moving.
Lender Name Loan Amounts Funding Speed Credit Impact (Check) Starting APR / Terms JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull See site Avant $2,000 – $35,000 Fast decision See site See site OneMain Financial $1,500 – $30,000 As soon as 1 hour No credit score impact 11.99% APR / 24-60 months OppLoans See site Same-day funding available Does not affect FICO score See site LightStream See site Next day See site Low fixed rates (Excellent credit req.) Hearth See site See site See site See site USPS Federal Credit Union See site See site See site As low as 4.75% APR 1. JetzLoan
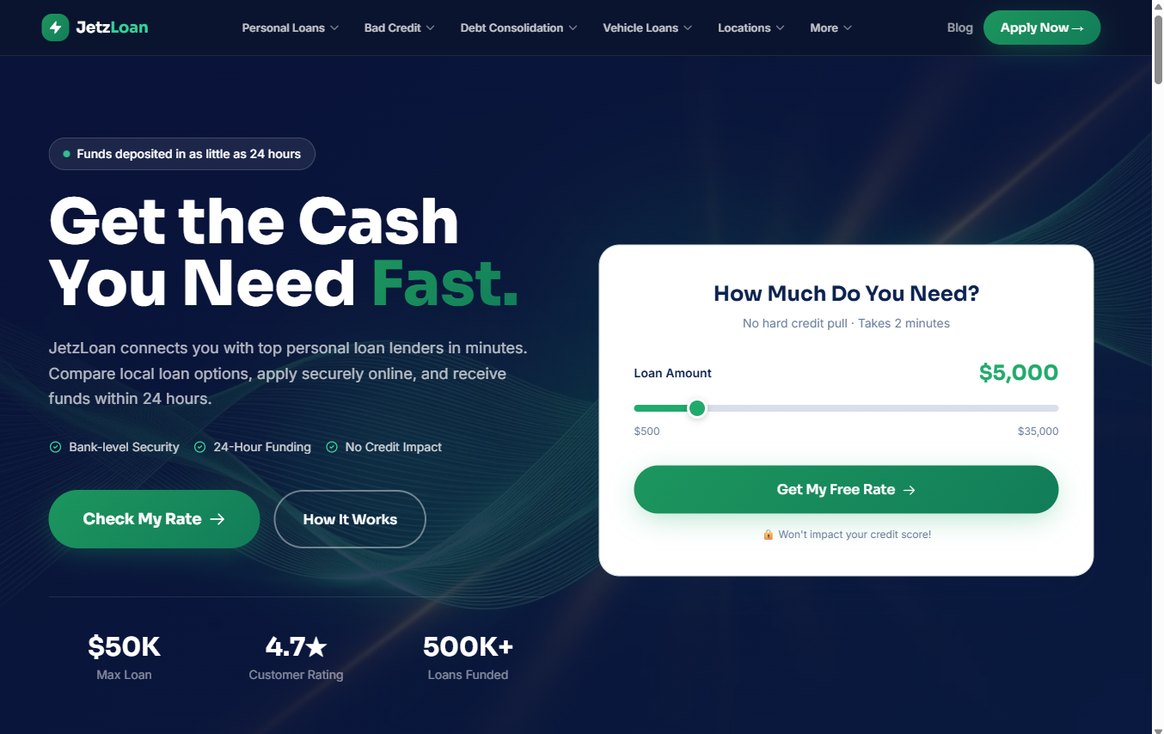
JetzLoan works by connecting borrowers with various top personal loan lenders in just a few minutes. This platform is built for speed. They aim to get funds deposited into accounts in as little as 24 hours, which is a lifesaver when things go wrong suddenly. It is useful for debt consolidation or vehicle loans without a long, drawn-out ordeal. (jetzloan.com)
The process is incredibly lightweight. You only need to fill out a simple form that takes less than two minutes. Since they offer a no-hard-credit-pull check, you can explore your options without worrying about damaging your score. It is a low-risk way to see what is actually possible for you.
Pros:
- No hard credit pull during the initial check.
- Fast 24-hour funding capability.
- High customer rating of 4.7 stars.
Cons:
- It is a connection service rather than a direct lender.
2. Avant
Avant targets people who need a clear path forward. They offer various tools designed to help users move financially, including personal loans and credit cards. This makes them a versatile choice for different milestones. They focus on providing options for people whose financial lives are in a state of transition.
The application for their personal loans is straightforward. You only need to go through three simple steps to reach a decision. Whether you need an emergency loan or cash for home improvements, Avant uses digital-first solutions to make the journey a bit easier.
Pros:
- Simple 3-step application process.
- Covers a wide range of needs like debt consolidation.
- Flexible product options including credit cards.
Cons:
- Specific loan amounts are restricted to a specific range.
3. OneMain Financial
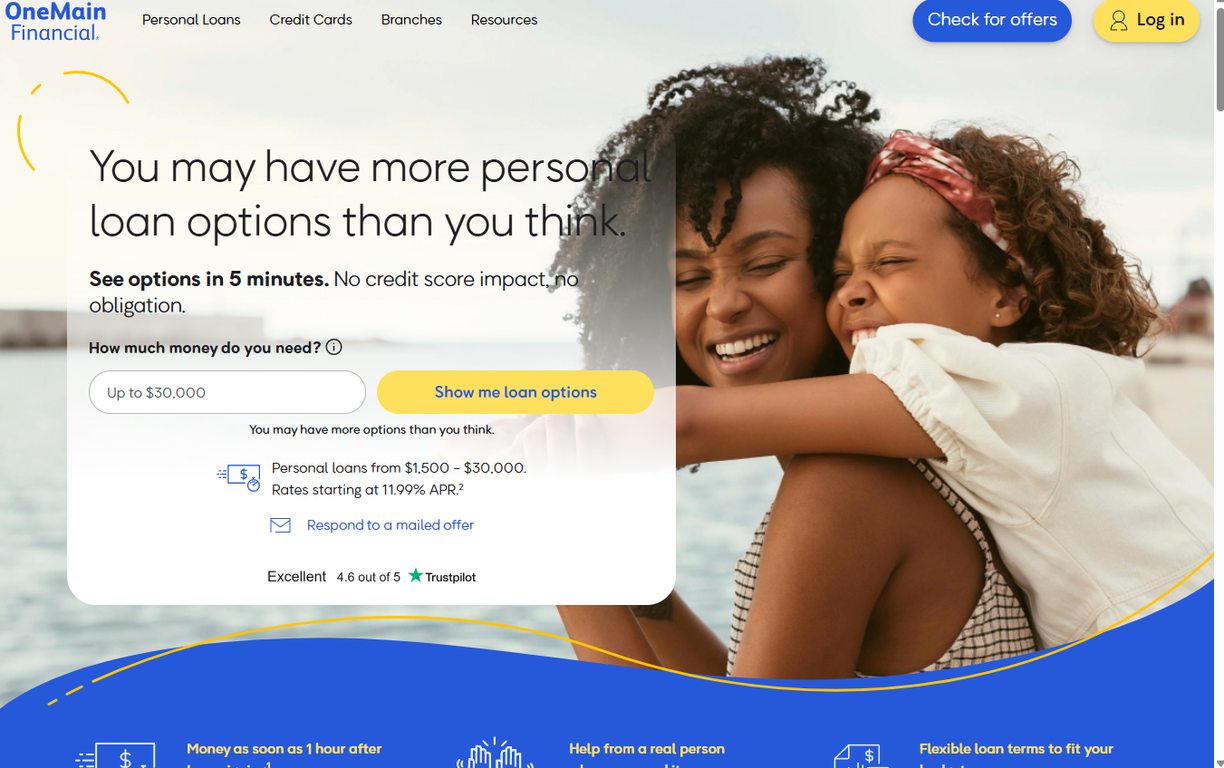
OneMain Financial is a great pick for those who prefer a mix of digital ease and talking to a real person. They have over 1,300 branches, so you can walk in and talk to someone if things get complicated. They offer personal loans from $1,500 up to $30,000, which covers most mid-sized expenses.
Speed is a big part of their appeal. Some users see money in their accounts as soon as one hour after signing. The terms are predictable, with fixed monthly payments and lengths between 24 and 60 months. This predictability helps anyone trying to stick to a strict monthly budget.
Pros:
- Extensive branch network for in-person support.
- Very fast funding possible within one hour.
- Fixed monthly payments for predictable budgeting.
Cons:
- Requires a formal signing process to unlock funds.
4. OppLoans
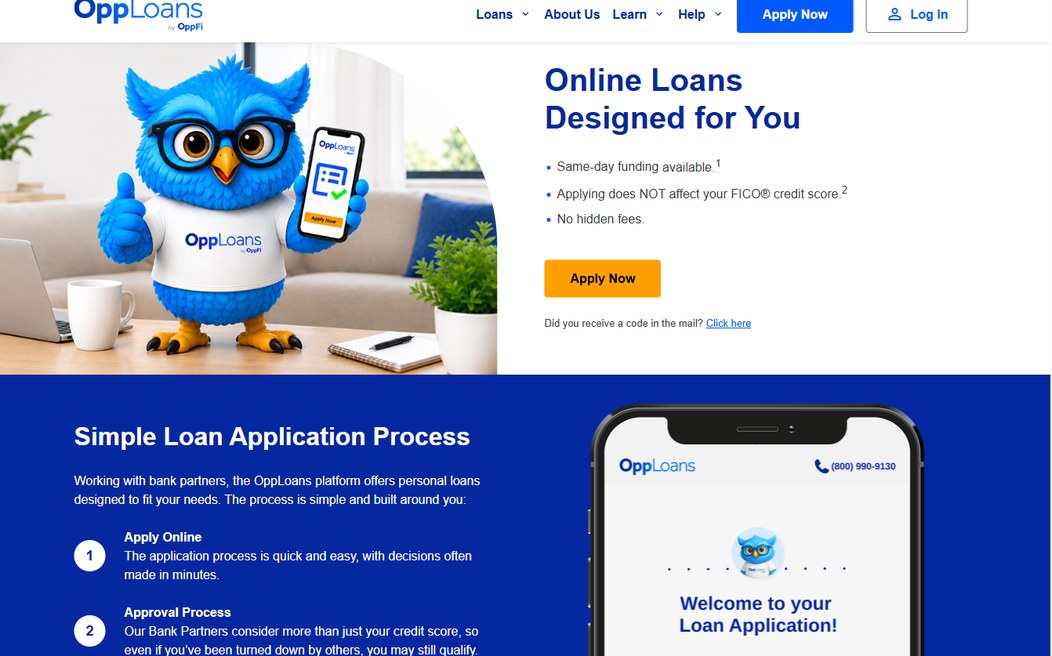
OppLoans specializes in helping people who might have been turned down by traditional banks. Their platform works with bank partners to look at more than just a single credit score. This makes them a strong candidate for anyone needing same-day funding to handle an urgent crisis.
The application is built around the user. They aim for decisions that arrive in just a few minutes. They also emphasize transparency by stating there are no hidden fees, which is a breath of fresh air in the subprime lending market. It is a streamlined option for quick, direct assistance.
Pros:
- Same-day funding is available for approved users.
- Decisions are often made within minutes.
- No hidden fees to worry about.
Cons:
- Approval is subject to bank partner criteria.
5. LightStream
LightStream is a specialized choice. People often favor them when they want to finance high-value items like boats or major home renovations. They run on a “Lending Uncomplicated” philosophy, focusing on a smooth digital experience. Many customers find they have the funds by the very next day.
While they are great for specific purposes, they aren’t a catch-all for everyone. They typically require excellent credit to get those low rates. However, if you have a solid history and need a large-scale loan, the efficiency is hard to beat.
Pros:
- Very fast funding, often by the next day.
- Excellent for specific purpose loans like boats.
- Highly rated customer experience for smooth processes.
Cons:
- Requires excellent credit for the best rates.
6. Hearth
Hearth operates more as a knowledge hub than a standard lender. Since 1995, they have been a staple for information on energy-saving equipment, like wood or pellet stoves. They focus heavily on promoting efficient and responsible uses of various fuels.
They might not be the first place you go for a quick cash loan for an emergency, but their forums are incredibly useful. If your financial needs involve home energy efficiency or specific equipment, the community advice found here is gold.
Pros:
- Decades of expertise in energy-related financing topics.
- Extensive community forums for peer advice.
- Focuses on responsible and safe fuel use.
Cons:
- Not a direct personal loan provider for general cash.
7. USPS Federal Credit Union
The USPS Federal Credit Union is a dedicated institution for postal employees. They offer a sense of community and specialized service that you just don’t find at big banks. Their loans support life’s milestones, from auto loans to flexible personal options.
They offer competitive rates, with some starting as low as 4.75% APR for certain products. For members, the value lies in their “People Helping People” philosophy. It creates a sense of security and shared purpose in every transaction you make.
Pros:
- Very competitive rates for members.
- Strong community focus on serving employees.
- Diverse range of products like HELOCs and credit cards.
Cons:
- Membership is restricted to specific employee groups.
Avoiding Common Pitfalls
Read the fine print on the total cost of your loan before you sign anything. A low monthly payment sounds great, but if it stretches over several years, you could end up paying double what you originally borrowed. Always calculate the total interest you will pay over the life of the loan.
Don’t rush into the first offer that lands in your mailbox. Even if you need the cash quickly, it is vital to compare rates and terms. Use the “no impact” checks offered by many lenders to shop around without fear. Taking a moment to compare can save you thousands of dollars.
-
The 5 Best Lenders for Bad Credit Loans in Ohio for 2026
The 5 Best Lenders for Bad Credit Loans in Ohio for 2026
Last updated: 2026-10-16
Trying to bridge a financial gap can feel like swimming against a heavy current. For many Ohioans, life happens fast. A sudden car repair, an unexpected medical bill, or a broken HVAC system in the middle of a freezing Midwestern winter can throw everything out of balance. Standard banks often slam the door shut when these crises hit because they rely on rigid, automated scoring models.
These systems typically ignore the context behind a temporary dip in credit. They don’t care if you had a medical emergency or a brief period of unemployment; they only see the number. If you are staring at an empty savings account, you need options that prioritize your current reality over your past mistakes. This guide looks at lenders that understand non-traditional credit profiles.
Whether you are living in Columbus, Cleveland, or Cincinnati, finding the right alternative lender is the first step toward regaining control. You want to avoid the usual red tape and find a way through the tight spots without making your situation worse in the long run.
- Bridge Credit Union
- FastLendGo
- Flexxbuy
- Acorn Finance
- GadCapital
Evaluating Financial Support Options Across Ohio
Picking a lender involves more than just finding the quickest cash injection. You have to look at the long-term cost and how transparent the company actually is. Speed is great, but predatory interest rates act like a heavy anchor on your financial future. A $500 loan that solves a problem today could end up costing you $1,500 over time if you aren’t careful.
The table below compares how these providers stack up against each other. We focused on loan amounts, how fast you get the money, and the credit requirements for each program. Use this as a starting point to see which structure fits your specific urgency and credit standing.
Lender Name Loan Amounts Funding Speed Credit Requirements Bridge Credit Union See site See site Low rate share secured loans available FastLendGo $500 – $5,000+ Fast access Bad, Fair, or Good Credit Flexxbuy Up to $100,000 Next business day Multi-lender matching Acorn Finance See site See site Good & Bad Credit GadCapital $100 – $5,000+ Instant No Credit Checks Top Rated Lenders for Ohio Residents
1. Bridge Credit Union
This institution serves the Central Ohio community, offering a more personal touch than the massive national banks. They provide low-rate share secured loans, which can be a lifesaver if your credit history isn’t quite perfect. These loans work by using your own savings as collateral to back the money you borrow.
For example, if you have $500 in a savings account but need a $1,000 loan, the lender uses that $500 as security. This lowers their risk and allows them to offer you a much lower interest rate than a standard, unsecured personal loan. It is a way to leverage what you do have to get what you need.
The process is designed to be straightforward. You can sign your loan documents online, which helps you get your funds much quicker. This is particularly useful for working professionals in the Columbus metro area who cannot take a half-day off to visit a physical branch during banking hours.
Pros:
- Offers share secured loans for those with imperfect credit.
- Digital signing makes the process very fast.
- Local focus provides a sense of community reliability.
Cons:
- Requires a share secured structure for certain low-rate options.
2. FastLendGo
If you are in a pinch and need to quickly compare options, this platform is a workhorse. They cater to a wide variety of needs, from small $500 loans to larger requests of $5,000 and beyond. The system is built for speed, aiming to connect your immediate need with various lending products.
They do not discriminate heavily against those with less-than-stellar credit scores. Whether your score is bad, fair, or good, they have a matching mechanism in place. It is an excellent tool for those needing specific financing for auto repairs, dental work, or roofing projects.
If you have a sudden $1,200 car repair bill that is preventing you from getting to work, FastLendGo can help you find a lender that looks at your income stability rather than just a FICO score. It is about finding a match that works for your specific situation.
Pros:
- Covers a wide range of specific needs like dental or auto repair.
- Accepts bad, fair, and good credit scores.
- Provides a fast way to compare local options.
Cons:
- The variety of options may lead to complex terms.
3. Flexxbuy
Flexxbuy operates differently because it acts as a multi-lender customer financing platform. Instead of being just one lender, it connects you with a network of over 35 different lenders. This can be a huge advantage when you need larger sums of money and want to avoid the hassle of multiple applications.
Instead of applying to 35 different banks individually—which would result in 35 “hard pulls” on your credit report—you submit one application and let the network do the work. This single application approach saves time and protects your credit score from unnecessary inquiries.
They specialize in high-ticket sales, making it possible to secure loans up to $100,000. If you are looking at a major purchase, such as solar panel installation or a luxury vehicle, they can get you a decision in seconds. Funds are often available as soon as the next business day.
Pros:
- Access to over 35 different lenders through one application.
- High loan limits up to $100,000.
- Extremely fast decision-making process.
Cons:
- Best suited for high-ticket items rather than small emergencies.
4. Acorn Finance
When home improvement is the reason for your debt, Acorn Finance is a specialized player. They focus on connecting borrowers with contractors through a financing platform. It is designed specifically to help with projects like pool installation, kitchen remodels, or replacing a furnace.
If you have a contractor’s quote in hand, Acorn can help you find the financing to make that project a reality without draining your entire emergency fund. They aim to make the renovation process as smooth as the construction itself.
They boast a high rating on Trustpilot, which speaks to their reputation in the contractor financing space. The platform allows you to check personalized rates without it hurting your credit score, utilizing “soft pulls” for the initial quote phase. This is vital for homeowners who want to compare options before committing.
Pros:
- No credit score impact when checking personalized rates.
- Specialized for home improvement and contractor financing.
- High user satisfaction ratings.
Cons:
- Limited to home improvement and contractor-related needs.
5. GadCapital
Sometimes, you don’t have time to wait for a credit check or a long approval process. GadCapital targets the most urgent situations with online payday loans. They offer a range of amounts, starting as low as $100 and going up to $5,000. These are for the “gap week” between paychecks.
This is a “no credit check” option designed for immediate action. If you are facing a sudden financial emergency where conventional banks will not help, this is a direct route to cash. It is built for those who need money right this second to cover groceries, utilities, or gas.
Because there is no credit check, the approval is based primarily on your ability to repay. This makes it highly accessible, but it also requires a very strict repayment plan to avoid high costs. It is a tool for survival, not for long-term financing.
Pros:
- No credit checks required for the application.
- Instant access to funds for emergencies.
- Very small loan amounts available for quick fixes.
Cons:
- Payday loan structures can be very expensive over time.
Common Pitfalls to Avoid When Borrowing
Before you sign any paperwork, take a deep breath and look at the fine print. It is easy to get caught up in the excitement of seeing a large sum of money available, but you must know exactly how you will pay it back. Always ask about the total cost of the loan, including all fees and interest rates.
Many borrowers only look at the monthly payment, but the “Total of Payments” is the number that actually determines the true cost. One common mistake is failing to distinguish between a secured and an unsecured loan. A secured loan uses something you own, like a car or a savings account, as collateral.
If you cannot pay, that asset is at risk. For example, if you use a vehicle title as collateral for a loan to cover medical bills and you default, the lender can repossess your car. Unsecured loans don’t require collateral, but they often come with much higher interest rates to offset the lender’s risk.
Another trap is the “interest rate trap,” where lenders offer 0% APR for the first few months. While this sounds appealing, if you cannot pay the full balance by the time the promotional period ends, you may be hit with “retroactive interest.” This means you are charged interest on the original full amount from day one.
Avoid the temptation to take out multiple loans at once to cover various debts. This is often a slippery slope that leads to a cycle of debt that is incredibly difficult to escape. Instead, try to consolidate your needs into one single, manageable payment plan whenever possible.
How to Prepare for a Successful Loan Application
Even when working with lenders that accept bad credit, being prepared can significantly increase your chances of approval. Taking twenty minutes to organize your documents can save you days of back-and-forth communication with a lender. It makes you look much more reliable.
First, gather your proof of income. Even if you are a freelancer or have non-traditional income, lenders want to see a consistent flow of cash. This can include bank statements from the last three months, recent pay stubs, or documentation of Social Security or disability payments. The more verifiable your income, the better.
Second, create a clear budget of exactly what you need. Rather than asking for “as much as possible,” identify the specific amount required for your emergency. If you need $1,250 for a transmission repair, do not ask for $2,000 just to have extra cash. Borrowing more than you strictly need increases your interest costs.
Finally, compare the “Annual Percentage Rate” (APR) rather than just the monthly interest rate. The APR includes not only the interest but also any origination fees, processing fees, or administrative costs. By comparing the APR, you are comparing the true cost of the money. Always look at the APR to find the most economical option.
-
The 5 Best Pool Financing Options Ranked for 2026
The 5 Best Pool Financing Options Ranked for 2026
Last updated: 2026-10-16
Dreaming of a backyard oasis sounds wonderful, but the actual construction process can quickly turn into a financial headache. Whether you want a saltwater pool or a heated spa, those upfront costs often feel like a mountain to climb. A standard in-ground pool installation typically runs anywhere from $40,000 to over $100,000 once you add excavation, filtration, decking, and landscaping. These big expenses require a smart financing plan so your summer retreat doesn’t become a permanent financial anchor.
Deciding on a lender depends on how fast you need the cash and where your credit score stands today. Some homeowners prioritize speed to keep contractors on schedule. Others hunt for the lowest interest rates to protect their long-term savings. If a contractor demands a 50% deposit before breaking ground, a slow bank loan might cost you your preferred installation window. On the other hand, a luxury pool with automated lighting might require a loan larger than most personal lenders allow.
- JetzLoan
- PaydayPact
- USDA Rural Development
- GoCredit
- Alliant Credit Union
How These Lenders Were Evaluated for Backyard Projects
We looked at how effectively each provider meets the specific needs of a home improvement project. This evaluation focused on funding speed, maximum loan limits, and how easy it is for different credit profiles to apply. We analyzed these providers by looking at the entire project lifecycle, from the first quote to the final inspection and the last payment.
Speed matters because pool installations are seasonal. A lender that takes weeks to approve a loan might cause you to miss the perfect summer window. In many areas, the construction season only lasts a few months of good weather. If you miss the April application window for a June installation, you might be waiting until next year. We looked for lenders offering “instant” or “next-day” funding to help beat those seasonal pressures. We also checked for transparency regarding credit impact, specifically looking for “soft” pulls for preliminary quotes.
Accessibility was another major part of this comparison. Since not every homeowner has a pristine credit history, we needed to identify which lenders allow for “soft” inquiries that won’t damage a score. This allows homeowners to shop around without fear of lowering their score during the research phase. We also considered loan purpose restrictions. While many personal loans are flexible, some lenders prefer home improvement use cases, which can sometimes lead to better terms.
Lender Name Max Loan Amount Funding Speed Credit Check Type JetzLoan $50,000 As little as 24 hours No hard credit pull PaydayPact See site See site See site USDA Rural Development See site See site See site GoCredit $4,000 Quick approval See site Alliant Credit Union See site See site See site Financing Strategies: Loans vs. Home Equity
Before picking a lender, you should understand which type of financing matches your property’s equity and your financial goals. Most homeowners choose between three main paths: Personal Loans, Home Equity Lines of Credit (HELOC), and Cash-Out Refinancing.
Personal loans, like those from JetzLoan, are unsecured, meaning the lender isn’t using your house as collateral. Because of this, interest rates are typically higher than equity-based loans, but the process is incredibly fast. You don’t need an appraisal or a mountain of paperwork. This makes them ideal for smaller additions like a hot tub or an above-ground pool. You can often have funds in your account before the contractor even shows up to survey the yard.
At the other end of the spectrum, a HELOC or a Home Equity Loan uses your home as collateral. If you are planning a massive renovation including a pool, an outdoor kitchen, and a new patio, a HELOC might be more cost-effective. Since the loan is secured by your property, interest rates are generally much lower and you can borrow larger sums. The downside is the complexity. You must go through a credit check, a home appraisal, and a rigorous underwriting process that can take 30 to 45 days.
Top Rated Pool Financing Picks
1. JetzLoan
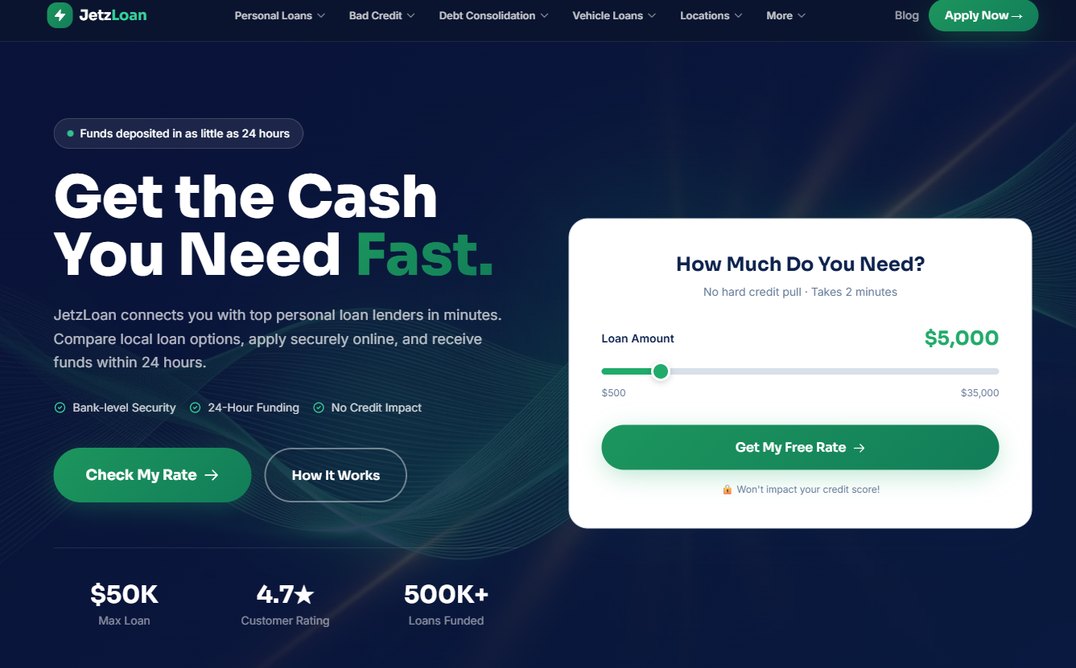
If you are staring at a hole in your backyard and need a contractor to start digging immediately, this is a heavyweight contender. JetzLoan specializes in connecting users with top personal loan lenders in a matter of minutes. This platform acts as a bridge between the consumer and a network of lenders, streamlining the comparison process so you don’t have to spend hours filling out individual applications.
The platform is built for speed with a simple two-minute application form. It is an ideal choice for someone who needs up to $50,000 and wants to avoid a “hard” credit pull during the initial rate check. This distinction is critical. A “hard” pull can shave a few points off your credit score, which could affect your ability to get a mortgage or an auto loan later this year. With JetzLoan, you can see your estimated rates and terms without that immediate penalty.
Pros:
- Funds can be deposited in as little as 24 hours.
- No hard credit pull to check your rate.
- High customer rating of 4.7 stars.
Cons:
- Max loan amount is capped at $50,000.
2. PaydayPact
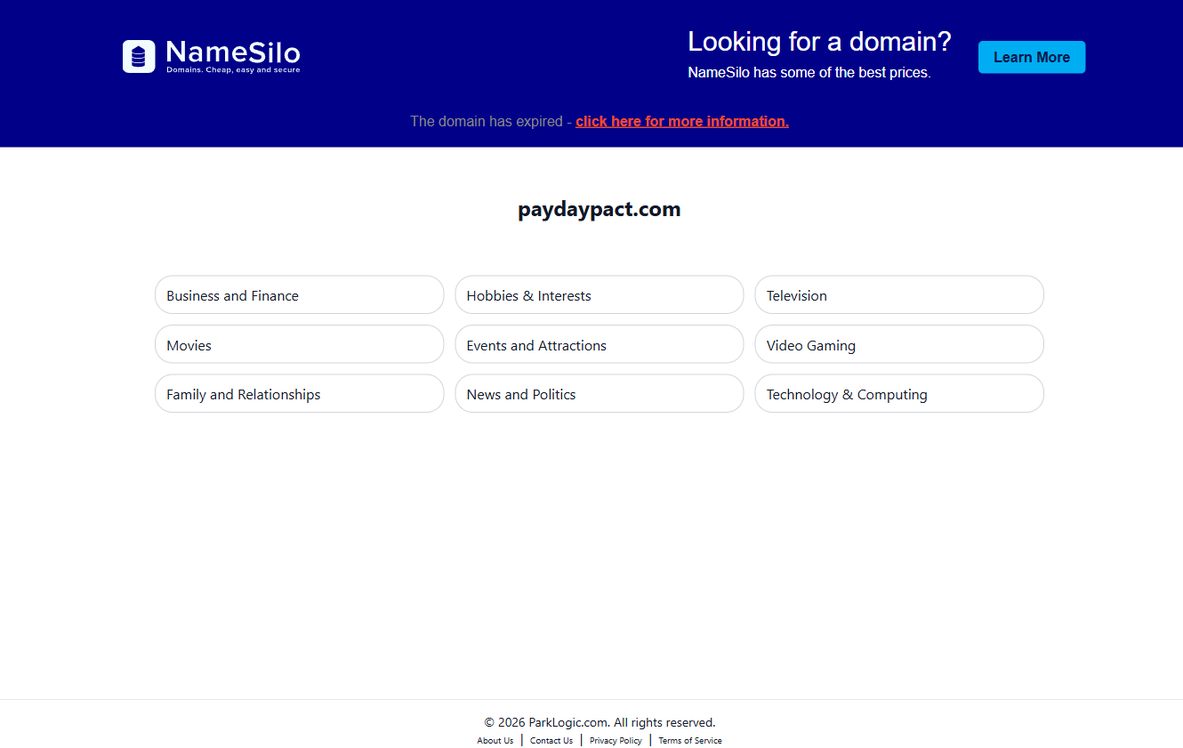
Finding the right financial partner can feel like searching for a needle in a haystack when you just want a simple service. PaydayPact currently appears to be a domain that has expired, making it unavailable for active loans. In the fast-moving world of fintech, websites and services frequently change ownership or close down, leaving behind “parked” domains that serve no active financial purpose.
Homeowners looking for immediate cash should be aware that this specific entity is not currently offering active financing products. It is a reminder to always double-check the status of a lender before committing any personal information. Always look for an active “Contact Us” page or a recent blog update to ensure a service is still operational before you start your application process.
Pros:
- None identified for active lending.
Cons:
- Domain has expired and service is unavailable.
- Cannot be used for current financing needs.
3. USDA Rural Development
For those living outside the bustling city limits, government-backed options provide a unique lifeline. USDA Rural Development offers programs that can assist with home repairs and various construction needs. These could potentially cover pool-related property improvements if they are deemed necessary for the property’s utility or safety. These programs are often designed to support low-to-moderate-income households in qualifying areas.
This is a great route for people living in qualifying rural areas who want to build, buy, or repair their homes. It is more of a long-term stability play rather than a quick cash injection for a weekend project. Because these funds are taxpayer-subsidized, the requirements for documentation—such as proof of income and residency—are much more stringent than a standard private loan. You will likely need to provide detailed plans of the work being done.
Pros:
- Official government-backed programs.
- Supports rural economies and community growth.
- Offers various loans and grants for home-related needs.
Cons:
- Eligibility is strictly limited to specific rural areas.
- The process can be more complex than private loans.
4. GoCredit
Sometimes, a pool project is just a small part of a larger financial rebuilding phase. GoCredit focuses on short-term installment loans designed to help users build their credit history while simultaneously establishing savings. This is a niche product that serves a dual purpose: providing immediate liquidity and improving your long-term financial health through consistent, on-time payments.
This is a solid option for someone who needs a smaller amount of cash, up to $4,000, to get a project started. For example, if you have already secured a larger loan but need an extra few thousand dollars to cover the unexpected cost of a premium salt-chlorination system, GoCredit can fill that gap. It is less about a massive renovation and more about steady, manageable financial growth.
Pros:
- Helps build credit history and savings.
- Quick approval process for smaller amounts.
- Available in several states like IL, MI, MO, and WI.
Cons:
- Lower loan limit of $4,000 may be insufficient for pools.
- Limited to specific geographic locations.
5. Alliant Credit Union
Credit unions often offer a more personal touch and better rates than traditional big-box banks. Because they are member-owned cooperatives, their primary motivation is often serving their members rather than maximizing shareholder profits. Alliant Credit Union provides a suite of banking services, including high-yield savings and checking accounts that can help you save for that big splash.
While they offer various loans, their strength lies in their high-rate savings accounts and certificates. If you have time to let your money grow, using their 12-month certificates could be a smart way to fund your dream backyard. If you know you won’t be building the pool for another 18 months, putting your renovation budget into a Certificate of Deposit (CD) can earn you interest, effectively making the bank help pay for part of your pool.
Pros:
- High-rate savings and certificate options.
- No monthly fees on certain checking accounts.
- Strong digital banking improvements.
Cons:
- Requires membership to access full benefits.
- May require more time to save compared to immediate loans.
Avoiding Common Pitfalls in Home Improvement Loans
The biggest mistake people make is ignoring the fine print on interest rates. It is easy to get caught up in the excitement of a new pool, but a high-interest rate can turn a summer luxury into a multi-year financial burden. Always ask for the Annual Percentage Rate (APR), which includes both the interest rate and any mandatory fees like origination fees. A loan with a lower interest rate might actually be more expensive if the upfront fees are significantly higher.
Another trap is failing to account for the “hidden” costs of pool ownership. Many homeowners borrow exactly what the contractor quotes, only to realize they are short once they consider:
- Increased electricity bills from the pump and heater.
- Chemical costs like chlorine and pH balancers.
- Professional maintenance services or high-end automated equipment.
- Insurance premiums (adding a pool can sometimes increase your homeowner’s insurance rate).
Always ensure that the lender you choose is legitimate and not a parked domain. As seen with some providers, a website that has expired can lead to a dead end when you are expecting a quick solution for your home. If a lender’s website looks outdated, lacks clear contact information, or has broken links, proceed with extreme caution. A legitimate lender will have clear, accessible customer service channels.
Finally, consider the impact on your credit score. If you are planning to buy a house in the next year, taking out a large personal loan for a pool might change your debt-to-income ratio significantly. Lenders looking to approve a mortgage will look at your total monthly debt obligations. Adding a $500/month pool loan payment could potentially decrease the amount of mortgage you qualify for, potentially delaying your ability to move into a larger home.
-
Top 7 Lenders for Uber Drivers Seeking Loans with Bad Credit in 2026
Top 7 Lenders for Uber Drivers Seeking Loans with Bad Credit in 2026
Last updated: 2026-10-16
Trying to manage money as a rideshare driver can feel like driving through a thick fog without any headlights. When an unexpected car repair or a medical bill pops up, the traditional banking system often turns its back on anyone with a less-than-perfect credit score. This struggle is the daily reality for many independent contractors on the road.
Unlike salaried employees who live for the predictability of a bi-weekly direct deposit, gig workers deal with constant volatility. You have to manage surge pricing, seasonal shifts in demand, and sudden maintenance costs that can wipe out a week’s earnings in a single afternoon. It is a constant balancing act of keeping the car running and the bank account full.
Finding reliable capital means looking past standard credit scores and focusing on actual earning potential. Traditional lenders often use FICO scores as the only way to judge trustworthiness. They ignore the fact that a driver might have high cash flow but a low score due to historical factors that have nothing to do with their current ability to pay their bills.
This list highlights the most effective options for drivers who need quick access to funds without the usual red tape. Your choice depends on the situation. You might need a small cushion for gas and groceries, or perhaps a larger loan to replace a transmission or invest in a more fuel-efficient vehicle.
- Ualett
- Earnin
- JetzLoan
- Dave
- BeneMoney
- Fence Outlet
- Max Cash
Evaluating Gig Economy Lending Options
The selection process for this ranking focused on speed and accessibility for people with variable incomes. Since Uber drivers do not have a traditional bi-weekly paycheck, we prioritized lenders that look at recent earnings rather than long-term credit history. In the rideshare world, liquidity is just as important as total income.
A driver who earns $1,500 a week but cannot access it until Friday is effectively broke for the first four days of the week. This gap can lead to high-interest predatory lending if you aren’t careful. Flexibility is the name of the game when you are working in the gig economy.
We looked for providers that offer rapid funding because a broken axle cannot wait for a three-day bank transfer. The comparison also checks how much each service provides and whether the application process triggers a hard credit inquiry. A hard inquiry can drop a score by several points, which might disqualify a driver from better interest rates later on.
Speed, transparency, and ease of use were the primary yardsticks we used to vet these services. We wanted to see which providers actually help drivers get back on the road without adding more stress to their lives.
Lender Name Max Loan/Advance Funding Speed Credit Impact Ualett See site Fast funding See site Earnin See site Up to 2 days early See site JetzLoan $50,000 As little as 24 hours No hard pull Dave $500 5 minutes or less No credit check BeneMoney See site Fast access No credit check Fence Outlet See site See site Max Cash $10,000+ In minutes See site 1. Ualett
Ualett positions itself as a financial partner designed for the ebb and flow of independent work. Instead of forcing drivers into a rigid, traditional banking box, it offers cash advances built around variable income. This makes it a strong contender for those whose weekly earnings fluctuate wildly.
If you have a high-earning weekend during a holiday surge but realize you need that money now to cover a sudden tire replacement, Ualett’s model recognizes that your income is already there, even if the platform hasn’t settled it yet. The platform focuses on providing simple solutions through a single app.
It is built for real life, aiming to help workers manage the ups and downs of the gig economy. This is ideal for drivers who need to bridge the gap between a heavy work week and a slow one. Rather than applying for a loan that requires months of documentation, Ualett looks at the data inherent in your work history to see your ability to repay.
Pros:- Designed for variable income patterns
- Flexible cash advances
- User-friendly mobile application
- Limited to specific gig worker profiles
2. Earnin
Earnin operates on a simple philosophy: why wait for money you have already earned? This service allows individuals to access their pay in real time through Live Pay. It is a lifeline for those who want to avoid the cycle of waiting for a weekly settlement to cover immediate needs.
If you’ve driven 40 hours this week and have accrued $600 in earnings, Earnin allows you to access a portion of that cash immediately. You don’t have to wait for the end-of-week payout from your rideshare app just to pay for something today.
Beyond simple cash access, the platform offers various financial health tools. Users can track credit scores, use savings jars to set aside small amounts for emergencies, and even access free career tools. It is a comprehensive ecosystem for anyone trying to move from surviving to thriving. By providing tools to save alongside tools to borrow, Earnin helps break the paycheck-to-paycheck cycle.
Pros:- Real-time pay access with Live Pay
- Includes credit monitoring and savings tools
- High user ratings on app stores
- Requires consistent work history to qualify
3. JetzLoan
When a driver needs a significant amount of capital, JetzLoan steps up to the plate. They connect users with top personal loan lenders in just a few minutes. It is a high-speed bridge for those needing everything from small amounts to much larger sums for vehicle investments.
If your car requires a major overhaul—such as a new transmission or an entire engine replacement—a $500 advance from an app won’t suffice. You need a substantial loan that can cover parts and labor. The service is notable for its speed, with funds often deposited in as little as 24 hours.
Because they offer a “no hard credit pull” option for initial rates, drivers can shop around without fear of damaging their already fragile credit scores. This is a critical feature for those working to rebuild their credit. You can see what rates you might qualify for without any penalty, allowing you to compare offers before committing to a formal application.
Pros:- No hard credit pull for rate checks
- Fast 24-hour funding capability
- High maximum loan limits up to $50,000
- May involve higher interest rates for bad credit
4. Dave
Dave is a popular choice for those who need a quick infusion of cash to cover the basics. With the ExtraCash feature, users can access up to $500 in five minutes or less. It is designed for those “in-between” moments, such as needing gas to complete a ride or groceries for the week.
If you find yourself $40 short at the pump and it’s preventing you from earning more, Dave provides a rapid response that traditional banks simply cannot match. The technology behind the app, CashAI, analyzes various data points including bank balance and irregular work patterns.
This means the app looks at your actual financial behavior rather than just a stale credit report. If you have been driving consistently and your bank account shows regular deposits from rideshare platforms, CashAI identifies that stability even if your credit score doesn’t reflect it. It is a modern solution for the modern, non-traditional worker.
Pros:- Extremely fast approval process
- No interest or late fees for ExtraCash
- No credit checks required
- Low maximum limit of $500
5. BeneMoney
BeneMoney operates a bit differently by acting as a financial safety net through an employer-sponsored model. It is not something a driver seeks out independently, but rather something provided as a benefit. This makes it a very stable and low-stress way to handle life’s surprises.
For drivers working through larger fleet management companies or delivery services that offer benefits packages, BeneMoney can be a vital resource. The service aims to reduce the massive stress that financial instability causes during the workday. When a driver isn’t worried about an unexpected medical co-pay, they can focus more effectively on the road.
By offering no-credit-check loans and free credit counseling, it helps build a more stable workforce. If your employer offers this, it is arguably the most secure way to manage short-term cash needs because it is integrated into your professional ecosystem.
Pros:- No credit checks required
- Includes free credit counseling
- Reduces workplace financial stress
- Only available through participating employers
6. Fence Outlet
While not a traditional lender for personal cash, Fence Outlet provides specific financing for home improvement materials. For drivers who might be working on a home-based business or simply want to upgrade their property, they offer specialized packages for DIY fencing projects.
This is particularly relevant for those who use their property as a secondary source of income, such as renting out space or running a small side business from their yard. They provide everything from wood to vinyl in convenient boxes designed for self-installation.
For those looking to invest in their property value through easy-to-use materials, this is a very specific but useful resource. Instead of taking out a general-purpose loan that might carry higher interest, using a specialized provider like Fence Outlet allows you to fund a specific home improvement project with tailored solutions.
Pros:- Specialized DIY fencing packages
- Available in various materials
- Local service availability
- Not a source of general liquid cash
7. Max Cash
Max Cash acts as a one-stop shop for a wide array of financial products. They offer everything from small cash advances to larger installment loans and even title loans. This variety makes them a versatile option for drivers with very different financial emergencies.
If you need a quick $200 for a registration fee, they have you covered; if you need $5,000 for a new set of tires and brakes, they can assist with that too. The platform is built for speed, promising relief in minutes. Whether you need a small $250 boost or a larger amount to cover a major car repair, they provide a personalized inquiry process.
This allows you to see the specific terms, interest rates, and repayment schedules that apply to your unique situation. It is a high-utility option for those who need specific types of credit and want to see multiple options in one place.
Pros:- Wide range of loan amounts
- Multiple product types available
- Quick personalized inquiries
- Title loans carry significant risks
The Risks of High-Interest Debt in the Gig Economy
While many of the options listed above are designed to be helpful, it is essential to understand the difference between “liquidity” and “debt.” For a rideshare driver, there is a fine line between using a cash advance to stay on the road and falling into a debt trap. Because gig income is non-guaranteed, a high-interest loan can quickly become unmanageable if you have a week of low demand.
When evaluating any loan, calculate your “break-even” point. If you borrow $500 to fix a tire, how many additional hours of driving will it take to pay back that $500 plus interest? If the answer is 20 hours of driving, it is likely a sound investment in your tool of the trade. However, if you are borrowing $500 for a non-essential purchase and it takes 20 hours of driving to repay it, you are essentially working for the lender.
Always ensure the loan is being used to generate more income or to prevent a greater loss. Don’t let your vehicle’s maintenance costs turn into a permanent debt cycle.
Building Long-Term Financial Resilience
The ultimate goal should not just be accessing quick cash, but moving toward a state where quick cash isn’t a necessity. Drivers can build resilience by implementing small, automated financial habits. Even saving just $5 per day through an app like Earnin can create a $150 monthly buffer.
While $150 may not cover a transmission replacement, it can cover a new set of windshield wipers or a sudden increase in fuel costs. Additionally, consider the “Sinking Fund” method for vehicle maintenance. Instead of viewing car repairs as a surprise, treat them as a monthly bill.
Calculate your average monthly maintenance cost (oil changes, tires, brakes) and set that amount aside in a separate account every single month. This transforms a “crisis” into a “planned expense,” allowing you to navigate the road with much more confidence and less financial fog.
Avoiding Financial Pitfalls
When you are staring at a mounting pile of bills, the temptation to grab the first cash offer is overwhelming. However, it is vital to understand the terms of any agreement. Always check if there are hidden fees or high interest rates that could trap you in a cycle of debt.
For example, some lenders may charge “origination fees” that are taken out of your loan before you even receive it. This means you get less than you asked for but still owe the full amount plus interest. Avoid the trap of taking out multiple high-interest loans at once. While a cash advance might solve a problem today, it can create a massive headache next month.
Always aim for the simplest solution that matches the size of your problem, and prioritize lenders that do not perform hard credit pulls. By being intentional with how you borrow, you can use these tools to fuel your career rather than let them become an anchor on your earnings.
-
The 7 Best Lenders for Bad Credit Loans in New Jersey for 2026
The 7 Best Lenders for Bad Credit Loans in New Jersey for 2026
Last updated: 2026-10-16
When a sudden car repair or a medical bill hits, hitting a financial brick wall feels all too real. Many New Jersey residents find themselves in this exact spot, staring at a mounting debt they didn’t see coming. You need a lender that looks past a single credit score to see if you actually have the means to pay them back.
Whether you are stuck with a broken transmission in Newark or facing a surprise dental bill in Jersey City, the stress of a crisis often makes it hard to do your homework. You might feel rushed to sign anything just to solve the immediate problem, but that impulse can lead to much bigger headaches down the road.
Sorting through the sea of lenders requires a sharp eye and a realistic mindset. Some companies offer cash in a heartbeat but charge a premium for the speed, while traditional banks offer more stability but move much slower. This list focuses on finding a middle ground for those with poor credit who want to stay financially healthy.
There is a massive difference between a high-interest installment loan and a structured medical payment plan. Choosing the wrong one can turn a temporary setback into a lifelong cycle of debt. Use this guide to weigh your options carefully before you sign any paperwork.
- Max Cash
- FastLendGo
- XCEL Federal Credit Union
- Fulton Bank
- Loanz
- Cherry
- CareCredit
Evaluating Financial Options Across New Jersey
Deciding which lender actually works for your specific situation requires looking at several different metrics. Most people in an emergency care about speed above all else. If your car is your only way to get to work in a commuter state like New Jersey, waiting three days for a loan might be impossible.
However, the total cost of the money you borrow is what keeps you afloat in the long run. You have to account for interest rates and those sneaky hidden fees. A quick loan is useless if the interest rates swallow your entire paycheck every month.
We also looked at how much flexibility these lenders offer when your credit history isn’t perfect. Some provide title loans if you have no collateral, while others specialize in medical financing. This covers everything from a tiny $250 cash advance to a massive $60,000 signature loan.
We focused on whether a lender cares more about your income or your credit score. Generally, your ability to pay—your actual income and employment—is a much better predictor of whether you will stay on track than a single number on a credit report.
Lender Name Loan Amounts Funding Speed Credit Requirements Max Cash $250 – $10,000+ Minutes Bad Credit Options FastLendGo Small Loans Available Quick Access Bad Credit/No Credit XCEL Federal Credit Union $500 – $60,000 See Site Secured/Unsecured Fulton Bank See Site See Site See Site Loanz $100 – $10,000 Quick/Convenient See Site Cherry See Site Instant Approval High Approval Rate CareCredit See Site Instant Decisions Subject to Credit 1. Max Cash
Max Cash acts like a one-stop shop for various financial needs. Their products range from small $250 advances to larger loans that go over $10,000. This makes them a solid choice if you need immediate relief from an unexpected expense. A $500 loan might fix a broken appliance, while the larger options help with car or home repairs.
The platform is built for speed. They target people who need installment or title loans in just a few minutes. Because they work with people who have bad credit, they offer a lifeline that big-box banks often won’t. Just keep in mind that being fast often means you will pay a higher interest rate.
Pros:
- Extremely fast processing for urgent needs.
- Wide variety of loan types including title loans.
- Accessible for those with bad credit.
Cons:
- Title loans require collateral, risking your vehicle.
2. FastLendGo
FastLendGo is a flexible option for personal financing. They work with all kinds of credit tiers, whether you have good, fair, or bad credit. It is a simple way to compare local options without driving from branch to branch. (fastlendgo.com)
This lender is great for specific life events like dental work or fixing your car. If you are searching for personal loans nearby, their online model simplifies that hunt. They aggregate different profiles to help match your credit score with a provider that actually wants your application.
Pros:
- Covers various life expenses like roof and dental repairs.
- Options for those with no credit history.
- Easy online comparison tool.
Cons:
- Focus is primarily on online comparisons rather than direct banking.
3. XCEL Federal Credit Union
If you want more traditional stability, XCEL Federal Credit Union offers secured and signature loans. Their loan amounts can reach up to $60,000, which provides a significant cushion for big life changes. You could use these funds for debt consolidation, home upgrades, or unexpected medical bills.
As a credit union, they feel a bit more community-focused than predatory lenders. Credit unions are owned by members rather than shareholders, which often leads to more personalized service. You can choose between secured and unsecured loans to find what fits your situation. Using a savings account as collateral can often unlock much lower rates.
Pros:
- High maximum loan amounts up to $60,000.
- Offers secured loan options for better rates.
- Member-focused service model.
Cons:
- Likely requires membership or specific eligibility.
4. Fulton Bank
Fulton Bank is a major name for New Jersey residents. They have the strength of a large institution but still maintain a local feel. This makes them a solid choice for long-term banking and managing more complex financial needs over several years.
They offer everything from personal to commercial banking. They might not be the fastest choice for a $200 emergency, but they are excellent for managing significant wealth or business investments. Their stability is a big plus if you want a lender that will still be around decades from now.
Pros:
- Highly secure and FDIC-insured.
- Wide range of banking services from personal to commercial.
- Strong presence in the New Jersey market.
Cons:
- May have stricter requirements than specialized bad credit lenders.
5. Loanz
Loanz focuses on helping you manage your future through specific loan solutions. With amounts between $100 and $10,000, they are great for smaller debt consolidation or upcoming costs like moving or weddings. This allows you to handle small problems before they turn into massive debts.
The main goal here is getting your life back under control. Their debt consolidation products help you manage multiple bills at once. Instead of tracking five different due dates, you can combine them into one monthly payment to simplify your budget and lower your interest stress.
Pros:
- Low entry point for small loans starting at $100.
- Specific products for debt consolidation.
- Convenient digital transactions.
Cons:
- Loan amounts are capped at a relatively modest $10,000.
6. Cherry
Cherry is a specialist in the healthcare and retail finance world. They have an impressive 90% approval rate and are used by thousands of providers. Their main goal is to let you get necessary services now and pay for them later, removing the immediate cost barrier.
The application process is incredibly fast, often taking only 35 seconds. This is a top choice for people who need dental work or home repairs immediately but want to spread out the costs. Cherry works directly through your service provider to make the process easy.
Pros:
- Extremely fast application process.
- High approval rate for consumers.
- Direct integration with many healthcare providers.
Cons:
- Limited to specific merchants and providers.
7. CareCredit
CareCredit is a credit card built specifically for health and wellness. It is accepted at over 285,000 locations, which makes it one of the most versatile tools for medical costs. You can use it for vision, dental, or even veterinary expenses.
You can check if you prequalify without hurting your credit score. This is vital if you are worried about your standing while you shop for medical options. Many plans offer “no interest if paid in full” deals, but be careful—missing a deadline can result in retroactive interest charges.
Pros:
- No impact on credit score during prequalification.
- Massive network of accepted locations.
- Flexible financing for health and wellness.
Cons:
- Subject to credit approval and specific terms.
Understanding the Differences Between Secured and Unsecured Loans
Before you apply for anything, you need to know if a loan is secured or unsecured. This choice changes your risk level completely. A secured loan is backed by an asset, like your car, your home, or a savings account. Because the lender can take that asset if you stop paying, they are usually more willing to work with lower credit scores.
Secured loans often come with lower interest rates, but the risk to you is much higher. If you miss payments on a title loan, you could lose your vehicle. It is a trade-off between a lower rate and the risk of losing your property.
An unsecured loan isn’t backed by any physical asset. Most personal loans and credit cards fall into this category. Since the lender can’t immediately take your car if you default, they charge higher interest rates and demand better credit scores. If you fail to pay, they can’t take your house instantly, but they can sue you or garnish your wages.
How to Prepare for a Loan Application
You can increase your chances of getting approved and getting a better rate by having a plan. Following these steps helps you avoid unnecessary hits to your credit score:
- Verify Your Documentation: Gather your recent pay stubs, bank statements, and ID before you start. If you are using an asset as collateral, have proof that you actually own it.
- Audit Your Debt-to-Income (DTI) Ratio: Lenders look at how much of your income goes to existing debt. If that number is too high, you might get denied. Try paying down small balances before you apply.
- Check for Errors in Your Credit Report: One wrong late payment can ruin your score. Use a free service to find and dispute mistakes before you go looking for money.
- Compare APRs, Not Just Interest Rates: The Annual Percentage Rate (APR) includes interest and mandatory fees. This is the real cost. A 10% rate with a $500 fee might be more expensive than a 12% rate with no fees.
- Use Prequalification Tools: Look for lenders that offer “soft pulls.” This lets you see your estimated rates without leaving a permanent mark on your credit report.
Avoiding Common Financial Pitfalls
Choosing a lender isn’t just about finding the first person to give you cash. You have to read the fine print. Many people take a high-interest loan just because they are in a rush. This can trap you in a cycle where the total interest you pay is actually higher than the money you originally borrowed.
Always look at the total cost of the loan, not just the monthly payment. A small monthly payment might hide a very long term that costs you thousands more in interest. A $5,000 loan with a $100 payment sounds great until you realize you’ll be paying it for seven years.
One mistake to avoid is applying for too many loans at once. Every application can trigger a “hard inquiry,” which lowers your score. If you apply for five loans in one week, banks will think you are desperate for cash. Use prequalification tools first to narrow your list before you make any official moves.
-
The 7 Best No Credit Check Home Improvement Loan Options for 2026
The 7 Best No Credit Check Home Improvement Loan Options for 2026
Last updated: 2026-10-16
Homeowners often find themselves in a tight spot when a sudden repair surfaces. A leaking roof or a broken fence doesn’t wait for a perfect credit score to fix itself. Finding a way to fund these urgent projects without the traditional hurdles of a hard credit inquiry can feel like searching for a needle in a haystack.
This list helps anyone looking to bypass the stress of a heavy credit pull. Whether you are tackling a massive renovation or just need a little extra cash for yard work, the right lender can make the difference between a completed project and an endless headache. Speed and transparency are the real winners here.
- JetzLoan
- LoanStart
- Jordan's
- Fence Outlet
- K and G Mowers
- SAIL Loans
- Hearth
How These Financing Options Were Evaluated for Home Projects
The selection process focused on accessibility and the impact on your financial profile. It is vital to distinguish between lenders that provide direct cash and those that offer specialized financing for specific goods. A hard credit pull can leave a dent in your score, so finding alternatives is key for many.
Every entry was scrutinized based on their stated loan amounts, the speed of funding, and whether a hard inquiry is required during the initial phase. We looked for providers that offer clear paths to getting money in hand quickly, ensuring that the “no credit check” promise actually delivers on its word.
Lender Name Max Loan Amount Funding Speed Credit Impact JetzLoan $50,000 As little as 24 hours No hard credit pull LoanStart $40,000 See site No impact on score Jordan’s See site See site See site Fence Outlet See site See site See site K and G Mowers See site See site No credit impact SAIL Loans $4,000 Quick approval Builds credit Hearth See site See site See site Top-Rated Home Improvement Financing Options
1. JetzLoan
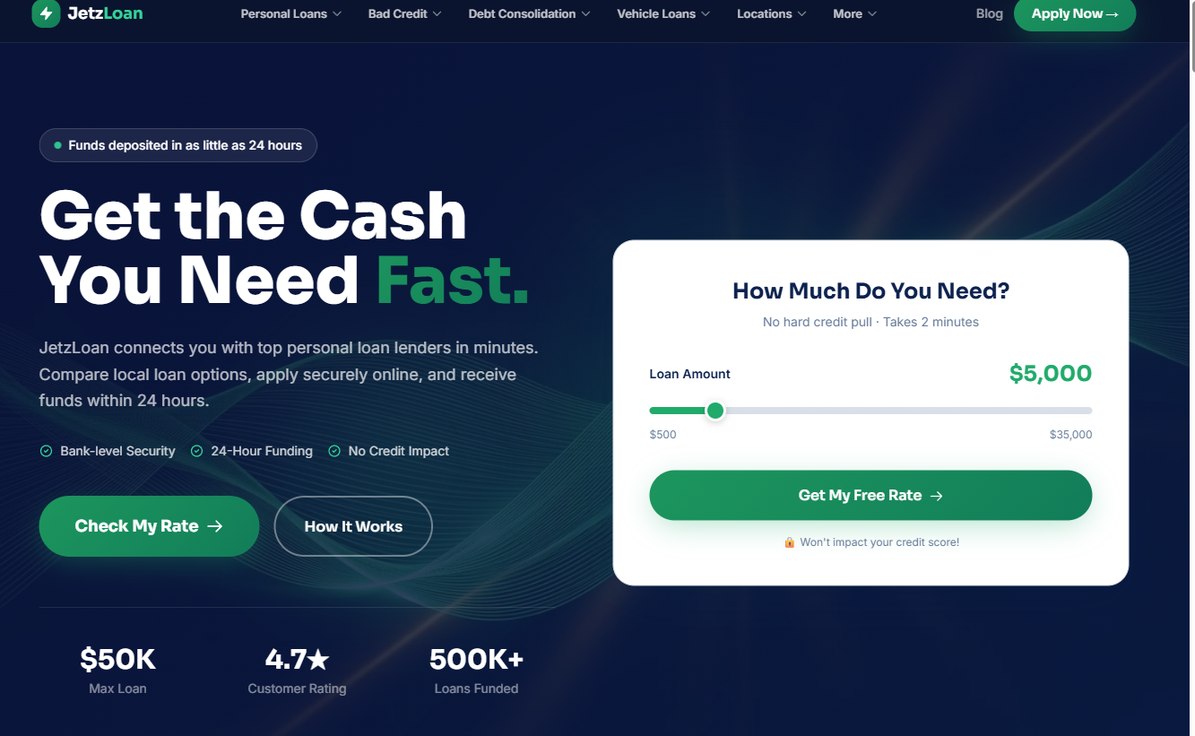
If you are staring at a massive renovation project that requires a significant chunk of cash, JetzLoan stands out. They offer a bridge between needing funds and actually having them in your bank account within a single day. This speed is a lifesaver when a contractor is standing on your porch demanding a deposit.
The platform is designed for efficiency, allowing you to fill out a simple form in under two minutes. It is a great fit for people who need to compare various local options without risking their credit score during the initial rate check process.
Pros:
- Funding can arrive in as little as 24 hours.
- Maximum loan amounts reach up to $50,000.
- Checking your rate does not impact your credit score.
Cons:
- The application process is very quick, which may lead to less detailed terms.
2. LoanStart
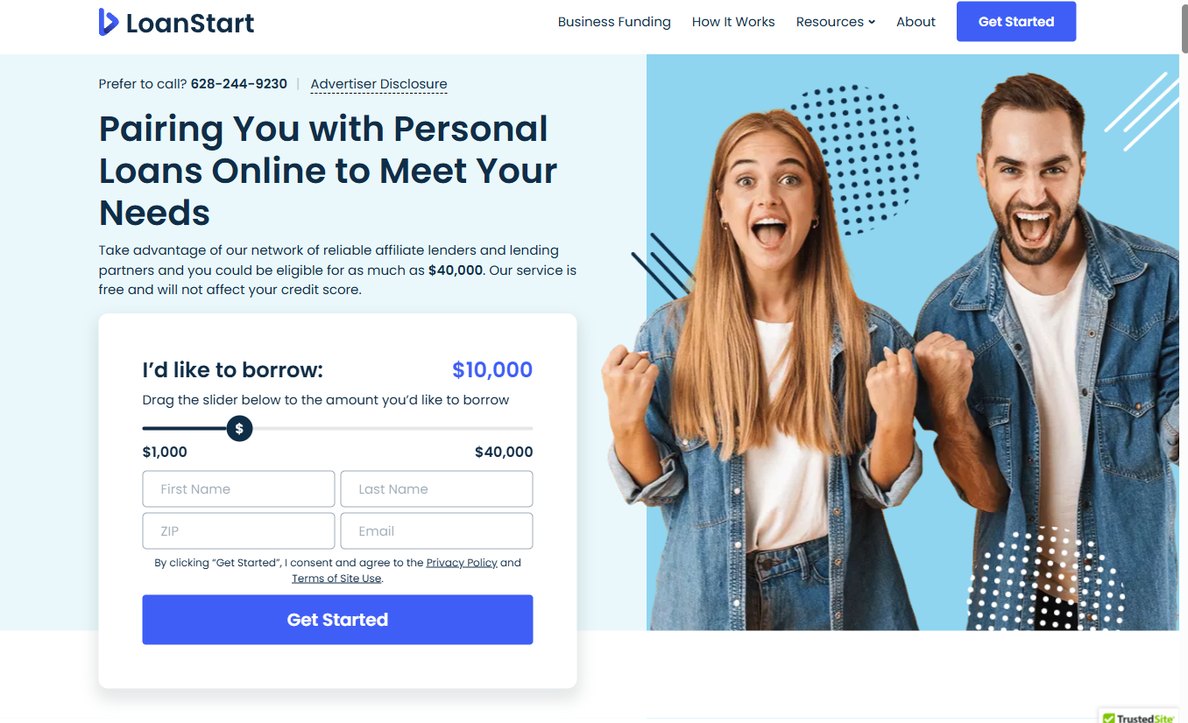
LoanStart operates as a helpful navigator through the complex world of personal loans. Rather than being a single lender, they act as a bridge to a network of reliable affiliate partners. This variety can be a blessing for those who have been rejected by traditional banks or credit unions in the past.
They specialize in matching people with loans for various reasons, including home improvements or debt consolidation. If you find yourself maxed out on credit cards, this service might help you find a more manageable installment loan structure.
Pros:
- Potential to borrow as much as $40,000.
- Service is free to use for the borrower.
- The service does not affect your credit score.
Cons:
- The final approval depends on the specific affiliate lender.
3. Jordan’s
Sometimes, home improvement isn’t about the structure itself, but the contents that make a house a home. Jordan’s focuses on the interior, offering financing for furniture and mattresses. This is ideal for those who are refreshing their living spaces without wanting to dip into their primary savings.
They offer specialized terms, such as up to 60 months of no interest for certain purchases. This makes it a strong choice for high-ticket items that you want to spread the cost of over a few years.
Pros:
- Flexible payment options like no-interest periods.
- White glove delivery options available for certain items.
- Focuses on high-quality home goods.
Cons:
- Financing is tied to specific furniture and mattress purchases.
4. Fence Outlet
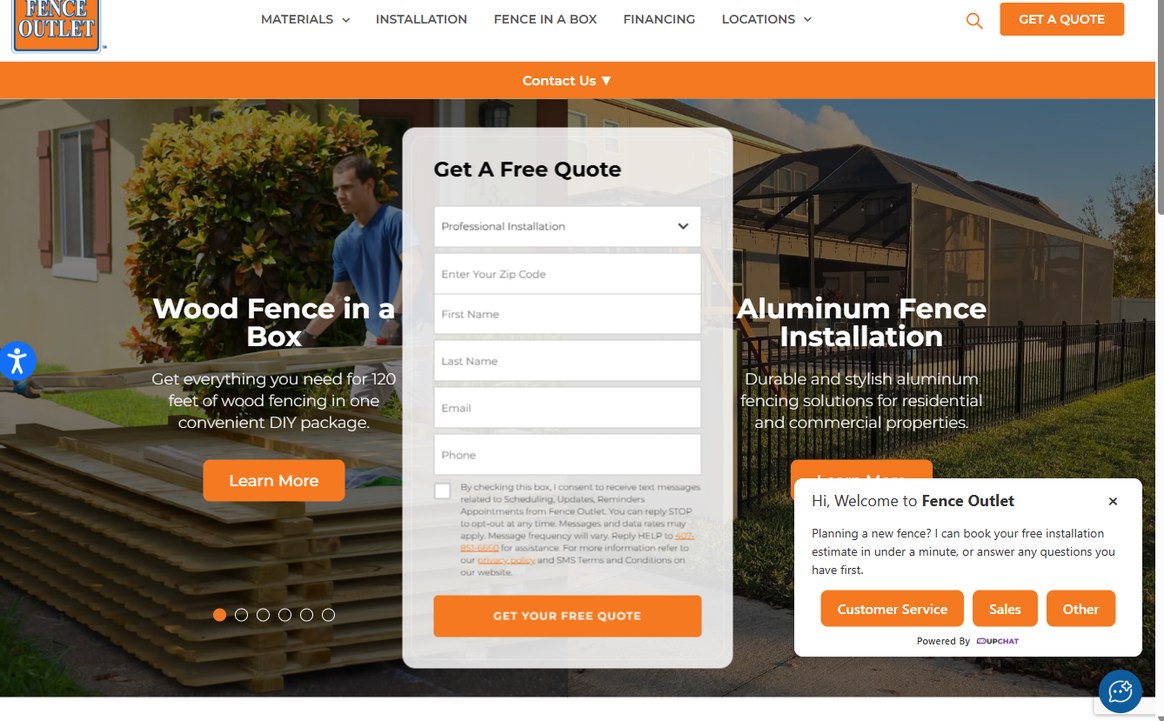
Fencing is a common project that many homeowners put off due to the upfront cost of materials and labor. Fence Outlet simplifies this by offering “in a box” solutions for both wood and vinyl. It is a specialized choice for the DIY enthusiast who wants to skip the middleman.
They provide complete packages that include everything needed for specific lengths, such as 120 feet of wood fencing. This removes the guesswork from your shopping list, making it much easier to budget for your backyard upgrades.
Pros:
- DIY kits are designed for easy self-installation.
- Specific packages for wood and vinyl options.
- Convenient for those wanting to avoid professional installation costs.
Cons:
- Not a general-purpose cash loan for all types of home repairs.
5. K and G Mowers
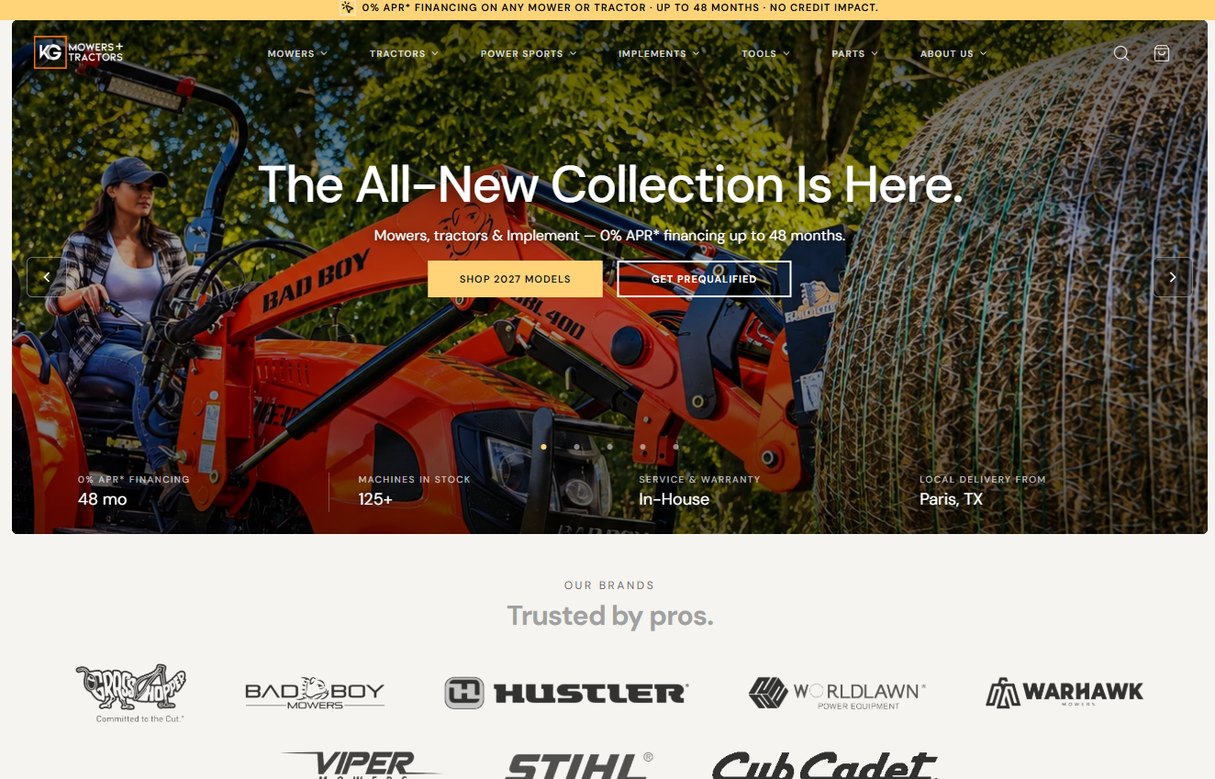
Landscaping and outdoor maintenance are essential parts of home upkeep. K and G Mowers provides specialized financing for heavy-duty equipment like tractors and mowers. If your yard work requires more than just a basic lawnmower, this is a solid path to getting the right tools.
They offer 0% APR financing for up to 48 months on certain models. This is a fantastic way to outfit your property with professional-grade machinery without a massive, immediate hit to your wallet.
Pros:
- 0% APR financing available for up to 48 months.
- No credit impact for prequalifying.
- Wide variety of brands and equipment in stock.
Cons:
- Financing is limited to specific machinery and equipment.
6. SAIL Loans
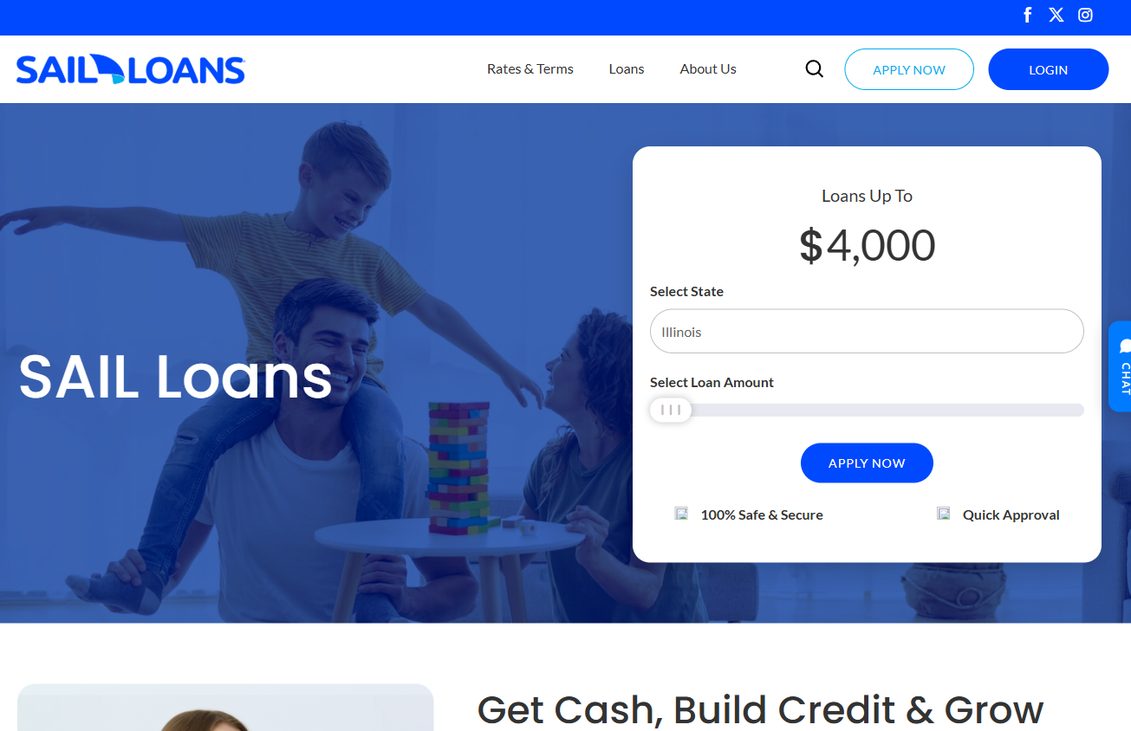
For those looking to improve their financial standing while simultaneously fixing up their home, SAIL Loans offers a unique path. They provide installment loans that are specifically designed to help users build credit history and savings at the same time.
With loan amounts up to $4,000, this is better suited for smaller, targeted home improvements. It is an excellent choice for someone who wants to prove their reliability to future lenders while getting the cash they need today.
Pros:
- Helps build credit history and savings simultaneously.
- Quick approval process for installment loans.
- Provides financial literacy tools and customer support.
Cons:
- Loan amounts are relatively low compared to other lenders.
7. Hearth
Hearth is a unique entry because it functions more as an information powerhouse for specific home heating needs. If your “improvement” project involves a wood stove, pellet stove, or a complex chimney repair, this is where the experts hang out.
While not a direct lender in the traditional sense, the community and resources available here are invaluable. It is the best place to research the efficient and safe use of fuels before you commit to a major installation.
Pros:
- Extensive forums for expert advice and discussion.
- Specialized focus on energy-saving and heating equipment.
- Valuable calculators and resource materials.
Cons:
- Not a direct source of cash for general home repairs.
How to Navigate Your Financing Options
Choosing the right way to fund your home project requires a bit of detective work. First, determine if you need liquid cash to pay a contractor or if you just need the materials. If you need cash, look toward JetzLoan or LoanStart. If you just need a new fence or a tractor, specialized retailers might be better.
Avoid the mistake of rushing into the first offer you see without checking the fine print. Even with “no credit check” options, there are interest rates and repayment terms that will affect your monthly budget. Always ensure the loan amount matches the actual cost of the project, including taxes and delivery fees.
Another common pitfall is ignoring the total cost of the loan. A low monthly payment might look attractive, but a longer term can result in paying much more over the life of the loan. Do the math before you sign anything to ensure your home improvement doesn’t become a long-term financial burden.
-
The 7 Best Lenders for Loans for Independent Contractors in 2026
The 7 Best Lenders for Loans for Independent Contractors in 2026
Last updated: 2026-10-16
Trying to secure financing as a 1099 worker often feels like walking a tightrope during a thunderstorm. Traditional banks usually demand decades of steady paychecks. However, the modern economy thrives on the hustle of freelancers and solo entrepreneurs. Finding a lender that actually speaks your language is the first step toward scaling your business or covering an unexpected gap.
Choosing a partner requires looking beyond just the interest rate. You have to consider how fast the cash hits your account. You should also ask whether the lender cares more about your personal credit score or your actual business revenue. This breakdown looks at the top contenders to help you find a match for your specific financial temperament and immediate needs.
- Swoop US
- Acorn Finance
- FastLendGo
- Giggle Finance
- Lendesca
- Greenbox Capital
- Discover
How These Lenders Were Evaluated
The selection process focused on the unique hurdles faced by non-traditional workers. We looked for lenders offering specialized products like invoice factoring, cash advances, and SBA-backed options. It is not just about the total amount of money available. Accessibility matters most for someone without a standard W-2 salary.
Speed of funding and credit flexibility were the primary metrics used for this comparison. Many contractors deal with seasonal fluctuations. A lender that can move in minutes is often worth more than a lower rate that takes months to process. Each entry was vetted for its ability to serve various credit profiles, from excellent to bad credit.
Lender Name Loan Amounts Funding Speed Credit Requirements Special Features Swoop US See site Minutes Varies Savings opportunities Acorn Finance See site See site Good & Bad Credit No credit score impact to check rates FastLendGo $500 – See site Quick access Bad to Great Credit Personal and specialized loans Giggle Finance Up to $15,000 Minutes Side hustles/1099s Repeat customers up to $20k Lendesca Up to $1,250,000 Weeks SBA/Freelance focus SBA expertise Greenbox Capital $3,000 – $500,000 As little as 1 day Low/Bad Credit Merchant Cash Advances Discover See site See site See site Credit card benefits Top Rated Funding Options for Freelancers
1. Swoop US
Swoop US connects your business needs with a wide variety of funding sources. Instead of just offering one type of loan, they provide a platform where you can find everything from equity finance to grants and commercial mortgages. It is a one-stop shop for those who need variety.
This platform is useful if you want to save on business expenses while searching for capital. By comparing multiple matches, you can find the most efficient way to fuel your growth. It is a smart choice for established businesses looking for more than just a simple cash injection.
Pros:
- Access to diverse funding types like grants and tax credits.
- Potential to find significant savings on business expenses.
- Fast matching process to get started quickly.
Cons:
- Higher interest rates may apply for those with bad credit.
- Borrowing amounts might be smaller for certain credit profiles.
2. Acorn Finance
Acorn Finance specializes in making the financing process easier for home improvement contractors. They understand that your customers often need financing for large projects like pool installations or kitchen remodels. You can offer professional financing options without the usual heavy lifting.
One of the most attractive features is the ability to check personalized rates without any impact on your credit score. This allows contractors to shop around without any fear of damaging their financial standing. It is a transparent way to offer value to your clients while ensuring they can afford your services.
Pros:
- Zero dealer fees for contractors.
- No credit score impact when checking rates.
- Works with both good and bad credit.
Cons:
- Focused primarily on the home improvement sector.
- Requires the customer to manage the financing process.
3. FastLendGo
If you find yourself in a situation where you need quick access to cash, FastLendGo offers a variety of personal financing solutions. They cater to a wide range of needs, from emergency auto repairs to dental financing or even motorcycle loans. It is a versatile option for personal needs.
The platform is designed to help you compare local personal loan options quickly. Whether you have great credit or are navigating the difficulties of bad credit, they have a product designed to meet you where you are. It is a straightforward approach to personal liquidity.
Pros:
- Wide variety of loan purposes, from auto to dental.
- Options available for various credit tiers.
- Simple online comparison process.
Cons:
- Primarily focused on personal rather than business-specific growth.
- Terms and rates are not explicitly listed upfront.
4. Giggle Finance
Giggle Finance is built specifically for the modern side-hustler and the 1099 worker. They recognize that the traditional banking model often leaves out the very people who drive the gig economy. Their mission is to provide fast, friendly funding for those who might be overlooked by big banks.
You can potentially secure up to $15,000 in just a few minutes. This is a lifesaver when a sudden business opportunity or expense arises. For repeat customers, that limit can even increase to $20,000. It is a streamlined solution for those who need speed above all else.
Pros:
- Extremely fast funding, sometimes in minutes.
- Specifically designed for 1099 and self-employed workers.
- Higher limits available for loyal, repeat customers.
Cons:
- Lower total loan amounts compared to traditional business loans.
- Fast speed often comes with higher interest costs.
5. Lendesca
Lendesca is a modern way to approach SBA loans, a process that is notoriously slow and bureaucratic. They have rebuilt the experience to help business owners move from application to funded in weeks rather than the months typically required. It is a high-level solution for serious growth.
They offer specialized products like freelance cash advances. These focus on your actual cash flow rather than just a corporate credit profile. With expertise in SBA loans, they are a powerhouse for those looking to secure significant capital through government-guaranteed channels.
Pros:
- Expertise in navigating the complex SBA loan process.
- Faster turnaround times than traditional SBA lenders.
- Offers freelance cash advances based on cash flow.
Cons:
- SBA loans generally require a higher credit score (around 680).
- The process is more complex than simple cash advances.
6. Greenbox Capital
Greenbox Capital is a powerhouse for small and mid-sized businesses that need working capital immediately. They offer alternative funding, such as Merchant Cash Advances. These can be repaid through a percentage of your daily or weekly sales. This aligns your repayments with your actual revenue.
They serve a massive range of industries across the United States, Canada, and Puerto Rico. With funding available in as little as one business day, they are the go-to for businesses that need to seize an immediate opportunity or cover a sudden inventory cost.
Pros:
- Extremely fast funding, sometimes in one business day.
- Large funding range from $3,000 up to $500,000.
- Flexible repayment through Merchant Cash Advances.
Cons:
- Merchant Cash Advances can be more expensive than traditional loans.
- Terms are tied to your sales volume, which can vary.
7. Discover
Discover is a titan in the consumer banking world. They offer a level of stability and nationwide acceptance that many niche lenders cannot match. Their credit cards are accepted by 99% of merchants. This makes them a reliable tool for day-to-day business expenses and personal needs alike.
They provide a variety of products, including personal loans and credit cards with attractive cashback incentives. It is a solid, dependable option for contractors who want a mainstream financial partner with high-quality customer service and security features.
Pros:
- Massive nationwide acceptance of their credit products.
- High level of security and financial insight tools.
- Strong cashback rewards on certain categories.
Cons:
- Less specialized for the unique needs of 1099 contractors.
- Standard credit requirements apply.
Navigating the Lending Landscape
When you are choosing a lender, avoid the trap of looking only at the monthly payment. A low monthly payment often masks a much higher total cost of borrowing over the life of the loan. Always ask for the total amount you will pay back by the end of the term to see the true cost of the capital.
Another common mistake is failing to match the loan type to your specific business cycle. If you have a seasonal business, a Merchant Cash Advance might feel easier because it scales with your sales. However, it could become incredibly expensive during your slow months. Always align your debt structure with the rhythm of your actual income.
-
The 7 Best Fence Financing Options for Homeowners in 2026
The 7 Best Fence Financing Options for Homeowners in 2026
Last updated: 2026-10-16
Securing your property line often feels like a heavy financial blow. Whether you are installing a high-end vinyl barrier for privacy or a simple chain-link fence to keep the dogs safe, the upfront price tag can sting. Many homeowners find themselves staring at expensive quotes, wondering how to bridge the gap between their current savings and that final, daunting bill.
Finding the right way to pay involves more than just scanning interest rates. You have to weigh how fast you can get the cash against the potential impact on your credit score. Some lenders offer money almost instantly, while others provide flexible, installment-based plans that help you manage a monthly budget without breaking the bank. Choosing the wrong path can leave you stuck with unexpected fees or long-term debt.
- JetzLoan
- Wisetack
- Alligator Fences
- Fence Outlet
- Affirm
- Klarna
- Cub Cadet
How We Evaluated the Top Fencing Lenders
To build this ranking, we looked closely at how different companies handle money. We checked out traditional personal loans, specialized “buy now, pay later” services, and the direct in-house financing offered by contractors. We wanted to see which options make the journey from the first application to the final fence post easiest for the homeowner.
Speed matters, especially if you are working against a tight construction schedule. We also looked for “hidden” costs, like whether a lender uses a soft credit pull during the initial phase. A lender that hits your credit score before you even know if you are approved is a major red flag for many modern consumers.
Lender Name Loan/Limit Range Funding Speed Credit Impact Special Feature JetzLoan Up to $50,000 As little as 24 hours No hard credit pull Fast disbursement Wisetack See site Under a minute See site Easy digital invoicing Alligator Fences See site See site See site In-home estimates Fence Outlet See site See site See site DIY kits available Affirm See site See site Check plans first No hidden fees Klarna See site See site See site Global availability Cub Cadet See site See site See site Equipment financing Top-Rated Financing Solutions for Your Fencing Project
1. JetzLoan
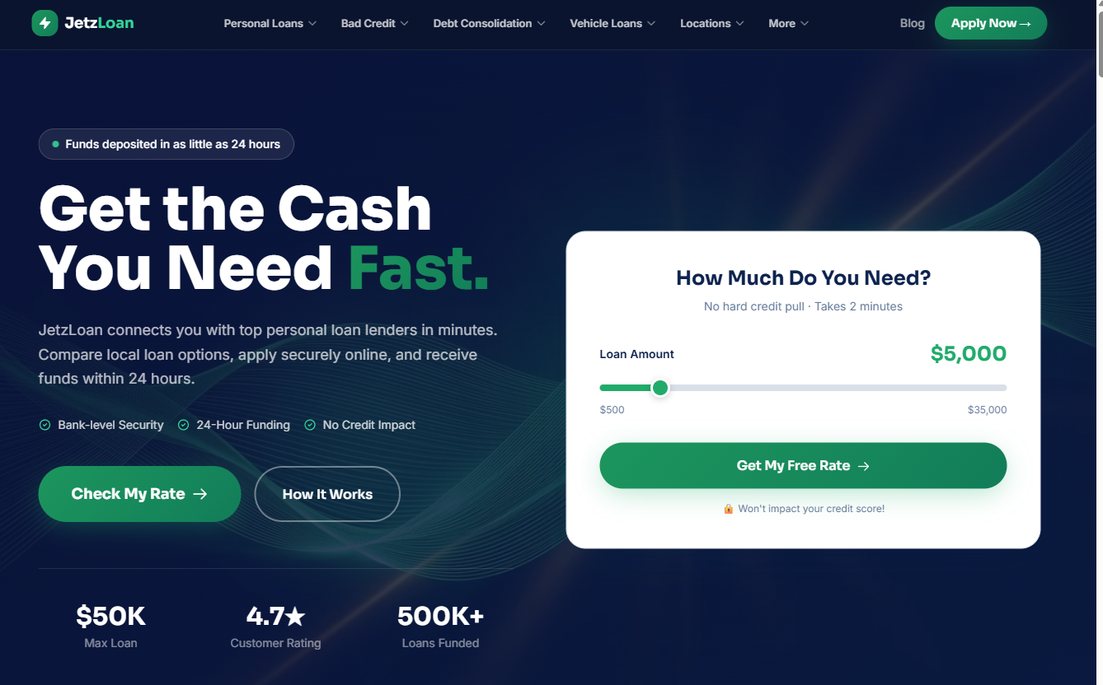
JetzLoan works well for people who need cash quickly to lock in a fencing contract. By connecting users with top personal loan lenders, the platform simplifies the search for better rates. It is a digital-first option built for the modern homeowner who wants things done efficiently. (jetzloan.com)
This option is a good fit if you need substantial amounts, as loans can reach up to $50,000. Since the application takes less than two minutes and uses a no-impact credit check, you can explore your options without worrying about a sudden drop in your credit score.
Pros:
- Rapid funding, often within 24 hours.
- No hard credit pull during the initial rate check.
- High user satisfaction with a 4.7-star rating.
Cons:
- Requires a simple form that still collects personal data.
2. Wisetack
Wisetack is a specialized tool that sits between the service professional and the customer. Instead of you chasing a bank, the financing is built into the merchant’s workflow. It is a smooth experience that aims to make paying for home services as easy as sending a text message.
If your professional uses Wisetack, you can see your payment options in under a minute. This eliminates the awkwardness of discussing large sums of money in person by providing clear, upfront terms that both the business and the homeowner can trust.
Pros:
- Extremely high customer satisfaction ratings.
- Simple, text-based or link-based application.
- Transparent upfront pricing.
Cons:
- Availability is dependent on your contractor using the service.
3. Alligator Fences
Alligator Fences takes a more traditional, local approach by combining high-quality vinyl products with professional installation. They focus on the actual product as much as the money, ensuring the materials can withstand harsh weather for years to come.
This is a great choice for homeowners in the Port St. Lucie area who want a “one-stop shop” experience. Rather than buying materials and a loan separately, you deal with a dedicated team that handles the estimate, the installation, and the financial arrangement all at once.
Pros:
- Comprehensive in-home estimates available.
- Guaranteed quality of vinyl materials.
- Reliable, dedicated installation team.
Cons:
- Geographically limited to specific service areas.
4. Fence Outlet
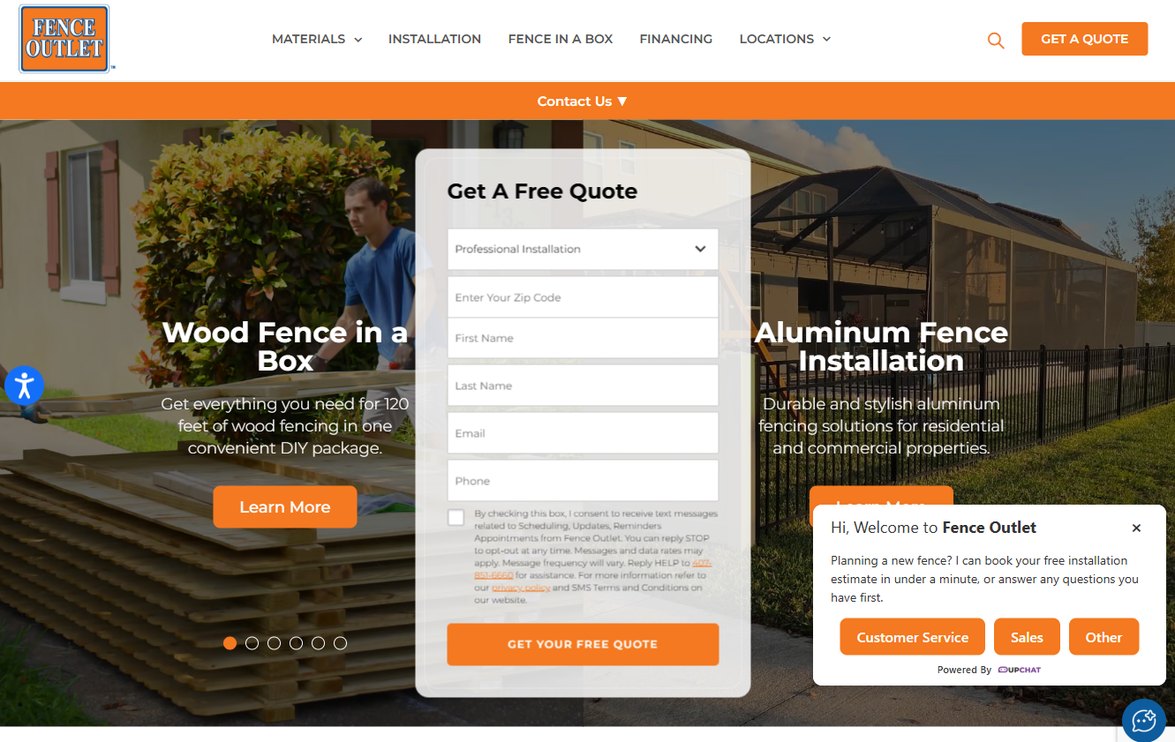
For the DIY enthusiast who wants to get their hands dirty, Fence Outlet offers a unique solution. They provide “Fence in a Box” packages for both wood and vinyl, making it easy to purchase every component needed for a standard 120-foot project in a single transaction.
This is perfect for the budget-conscious homeowner who has the tools and the time to do the work themselves. By providing materials in a convenient, pre-packaged format, they remove much of the guesswork and the need for constant trips to a hardware store.
Pros:
- Convenient DIY kits for wood and vinyl.
- Wide coverage across Central Florida.
- Streamlined material selection process.
Cons:
- Requires physical labor and installation skills from the user.
5. Affirm
Affirm has changed the “buy now, pay later” space by offering flexible, transparent payment plans. They focus on removing the “gotchas” often found in consumer credit, ensuring you see exactly what you will pay in interest upfront, if there is any at all.
This is a solid option if you are buying fencing materials through an online retailer that accepts Affirm. The ability to choose between interest-free plans or longer-term installments allows you to tailor your debt to your specific monthly cash flow.
Pros:
- No hidden fees or surprise costs.
- Highly transparent interest terms.
- Flexible payment schedules to fit your lifestyle.
Cons:
- Credit approval is subject to the retailer’s terms.
6. Klarna
Klarna is a global heavyweight in digital payments, offering a quick checkout experience for a massive variety of online merchants. Their platform is built for speed, making it a staple for modern online shopping all over the world.
If you find a fencing supplier or a hardware vendor that accepts Klarna, you can finish your purchase in seconds. It is a secure way to split a large purchase into manageable chunks without needing to go through a traditional bank loan.
Pros:
- Extensive international availability.
- Extremely easy-to-use mobile app.
- Secure and widely accepted payment solution.
Cons:
- Often limited to specific online retail partners.
7. Cub Cadet
While not a fencing company, Cub Cadet is a major player for those who need to maintain their yard once the fence is up. They specialize in high-end mowing and outdoor equipment, offering financing that makes heavy-duty machinery more accessible.
This is a strategic pick for the homeowner who is upgrading their entire outdoor setup. If your fencing project happens at the same time you need a new zero-turn mower or snow blower, their financing can help you bundle those investments into one manageable plan.
Pros:
- Specialized in high-quality outdoor equipment.
- Flexible financing for large machinery purchases.
- Wide range of commercial and residential models.
Cons:
- Not a direct provider of fencing materials or labor.
How to Navigate Your Financing Decision
Before you sign any paperwork, take a moment to breathe and look at the big picture. A common mistake is focusing only on the monthly payment while ignoring the total cost of the loan. A lower monthly payment often means a longer term, which can result in paying significantly more in interest over time.
Always check whether the lender uses a soft or hard credit pull. A soft pull is a “look but don’t touch” method that won’t hurt your score, making it ideal for shopping around. A hard pull, however, is a formal application that can cause a temporary dip in your credit rating. Knowing the difference can save you significant stress during the planning phase.
Another pitfall is failing to account for installation costs in your initial loan request. It is a headache to realize halfway through a project that you have enough for the wood but not enough for the nails, screws, or the professional labor. Always aim to borrow slightly more than the material cost to cover the full scope of the job.
-
The Best Lenders for Plumbing Financing and Repair Projects in 2026
The Best Lenders for Plumbing Financing and Repair Projects in 2026
Last updated: 2026-10-16
Trying to find a way to pay for a sudden pipe burst or a long-overdue bathroom remodel often feels like wandering through a dark maze. When a small leak turns into a full-blown flood, the last thing a homeowner wants to worry about is a depleted bank account. A burst pipe does more than just ruin your floorboards. It threatens the very structure of your home and the safety of everything you own.
The immediate stress of a water emergency is a heavy burden. It gets much worse when the question of how to pay for it enters the conversation. This ranking is for professionals and homeowners who need clarity on funding essential plumbing work. Choosing a lender involves more than just glancing at a single number. You have to weigh speed against credit flexibility and how easy the application process actually is.
Whether you are looking to finance a $15,000 sewer line replacement or a $500 emergency faucet repair, the way you borrow will dictate your long-term financial health. We have looked at several options to help you decide.
- Hearth
- FastLendGo
- Balance Credit
- PaydayPact
- LightStream
- Cub Cadet
Evaluating the Top Financial Solutions for Plumbing Repairs
We examined several specific metrics to see which lenders actually deliver when the water starts rising. The focus stayed on how quickly a person can access funds and what kind of credit profile is needed for approval. We looked past the marketing fluff to understand the practical utility of each option during a real crisis.
Speed is often the most critical factor when a basement is flooding or a heating system fails. In a plumbing emergency, every hour counts. A slow approval process might mean you have to delay a critical repair. This leads to secondary damage like mold growth or wood rot. Because of this, the ability to secure quick approval and rapid disbursement was a primary benchmark for this comparison.
We also analyzed the barrier to entry for each lender. Some lenders prioritize speed through automated underwriting, which usually requires a pristine credit score. Others prioritize inclusivity, working with subprime borrowers who might be in a bind but have a less-than-perfect credit history. Knowing where you sit on the credit spectrum is the first step in selecting the right tool for the job.
Lender Name Max Loan Amount Speed of Funding Credit Requirements Hearth see site see site see site FastLendGo see site see site Bad Credit Options Balance Credit $4,000 Next Business Day Less-than-perfect Credit PaydayPact see site see site see site LightStream see site Next Day (some) Excellent Credit Required Cub Cadet see site see site see site Top-Rated Financing Options for Plumbing and Home Repairs
1. Hearth
Hearth works as a platform designed to help home improvement professionals manage their business more effectively. It provides tools to create digital contracts and offer financing options directly to customers right on the job site. This is a B2B2C model. It sits between the contractor and the homeowner to make transactions smoother.
This service is particularly useful for plumbing contractors who want to increase sales by making large projects more affordable. A contractor offering a $10,000 water heater replacement might find that customers are hesitant to pay everything upfront. By integrating financing into the invoicing process, pros can offer monthly payment plans. This helps them close more jobs and improve cash flow. For the homeowner, the plumber becomes the single point of contact for financing.
Pros:- Seamless digital contract creation and invoicing.
- Helps increase project sizes and close rates.
- Designed specifically for home improvement professionals.
- Primarily focused on the contractor’s workflow rather than direct consumer loans.
2. FastLendGo
FastLendGo is a versatile partner for those who need quick access to cash for various needs. Their platform allows users to compare local personal loan options. This is a lifesaver when an unexpected plumbing emergency strikes. Instead of applying to one bank and waiting, you can view a marketplace of options tailored to your specific financial situation. (fastlendgo.com)
They cater to a wide demographic, offering solutions for people with bad credit or those who are first-time borrowers. This is vital because many people facing plumbing emergencies are also facing other financial pressures. Whether the need is for auto repairs or home-related expenses, they aim to provide a faster way to borrow. This comparison model can save hours of manual research during a high-stress situation.
Pros:- Options available for bad credit and high-income individuals.
- Easy to compare multiple local loan options.
- Covers a variety of loan types including emergency needs.
- The variety of options can be overwhelming for someone in a rush.
3. Balance Credit
Balance Credit focuses on providing quick cash advances when financial freedom is needed most. They offer a simple online application process that takes only a few minutes. This makes it ideal for urgent repairs like a burst pipe or a failed sump pump. Their streamlined digital intake is designed to minimize friction and get you an answer almost immediately.
One of their standout features is the ability to review applications even if a person has less-than-perfect credit. If approved, funds can be deposited into an account as soon as the next business day. This style of funding is perfect for the $500 to $3,000 range. These are the types of expenses that can be wiped out by a credit card but are best handled by a dedicated, short-term loan with predictable terms.
Pros:- Fast funding, potentially by the next business day.
- No penalties for paying off loans early.
- No impact on traditional credit scores during the application.
- The $4,000 limit may be insufficient for major structural plumbing overhauls.
4. PaydayPact
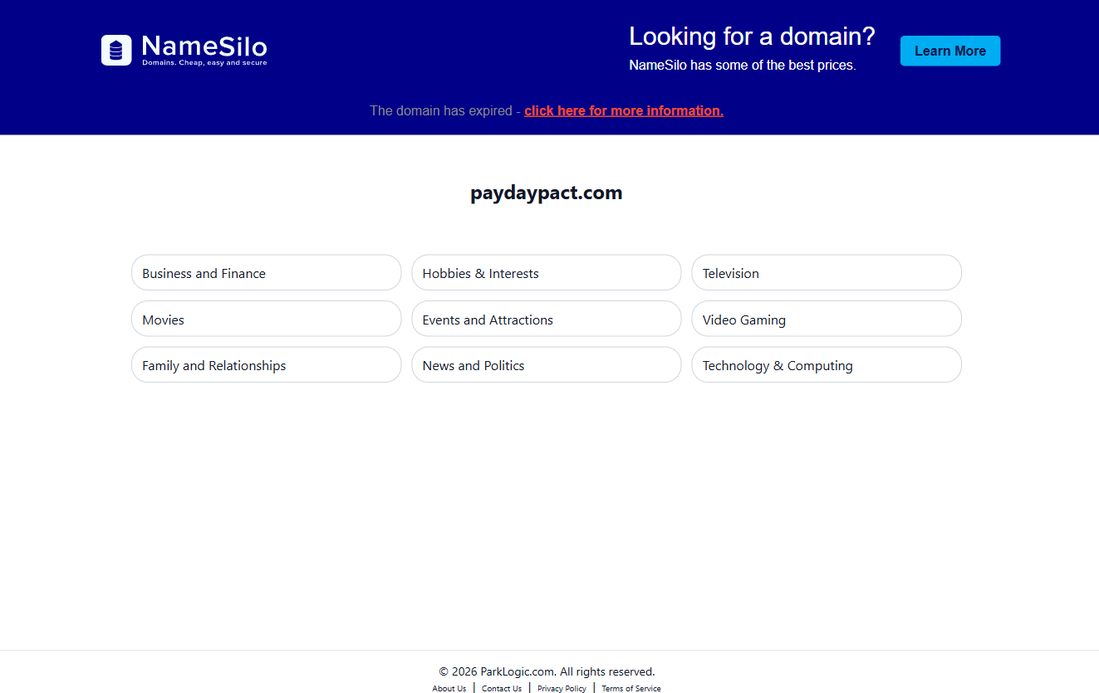
PaydayPact is a specialized entity within the personal finance space. While service availability can vary, the platform is part of a larger ecosystem of financial and personal interest resources. It acts less like a direct lender and more like a navigational aid within the complex world of consumer credit.
Users looking for specific niche financial advice or redirected services might find their way here. It is a specialized option for those navigating the broader landscape of personal finance and debt management. If you are unsure whether you need a personal loan, a line of credit, or a specialized home improvement loan, this platform can help you find the right direction.
Pros:- Part of a wide network of financial and personal interest content.
- Potential for finding specific niche financial guidance.
- Limited direct information regarding specific plumbing repair loan terms.
5. LightStream
LightStream, a division of Truist, provides straightforward lending for a massive variety of purposes. Their rates are fixed and can be quite competitive, especially for those who utilize AutoPay to secure a discount. Unlike many “emergency” lenders that rely on high interest rates to offset risk, LightStream focuses on high-quality borrowers who can benefit from low-cost capital.
This is a premier choice for homeowners with excellent credit who are planning significant renovations. If you are planning a kitchen remodel that involves moving gas lines or replacing all the plumbing under a new island, LightStream provides the substantial capital needed for high-ticket projects. They offer a smooth experience. Some customers report receiving funds as quickly as the next day, making it a top-tier choice for planned expenditures.
Pros:- Competitive fixed rates from 9.99% to 24.94% APR with AutoPay.
- Highly rated customer service and smooth application process.
- Flexible use for various home improvement projects.
- Requires excellent credit to access the lowest interest rates.
6. Cub Cadet
Cub Cadet is primarily recognized as a manufacturer of high-quality outdoor power equipment. Their focus lies in providing zero-turn mowers, riding mowers, and snow blowers for residential and commercial use. They are a powerhouse in the landscaping and property maintenance sector.
While they offer financing options, these are typically tied to the purchase of their specific machinery. This makes them a specialized choice for those looking to maintain their property rather than for fixing indoor plumbing. If your home repair needs include upgrading your outdoor maintenance tools to prevent yard drainage issues, their financing might be relevant.
Pros:- High-quality, durable commercial and residential equipment.
- Advanced technology like Synchro-Steer for steep inclines.
- Specific financing options tailored to equipment purchases.
- Not a general-purpose lender for household plumbing repairs.
Understanding the Difference Between Emergency and Planned Financing
Homeowners often fail to distinguish between the two primary types of plumbing-related financial needs. Understanding this distinction can save you thousands of dollars in interest and fees.
1. Emergency Financing: The “Reactive” Approach
An emergency is a burst pipe, a failed water heater in winter, or a sewage backup. In these scenarios, your priority is speed. You need a lender that offers instant decisions and rapid disbursement. You might sacrifice a bit on the interest rate to ensure the plumber can start working immediately. In this case, options like Balance Credit or FastLendGo are more appropriate because they prioritize the immediate availability of cash over the lowest possible APR.
2. Planned Financing: The “Proactive” Approach
A planned renovation is a bathroom remodel, a new deck, or a complete repiping of an older home. You have the luxury of time. You can spend two weeks shopping for the best APR and comparing monthly payments. In this scenario, LightStream or Hearth (through your contractor) are much better options. You want a fixed-rate loan with a long term that minimizes your monthly payment, allowing you to fund a massive project without straining your budget.
How to Prepare for a Loan Application
Regardless of which lender you choose, being prepared can significantly speed up the approval process and help you secure better terms. Most lenders will require several key pieces of information. Having these ready in a folder can shave hours off the process.
Document Type Why You Need It Example Proof of Income To verify your ability to repay the loan Recent pay stubs or W-2s Proof of Residency To verify your identity and location Utility bill or lease agreement Identification To comply with “Know Your Customer” laws Driver’s license or Passport Bank Statements To verify cash flow and existing debt Last 2-3 months of statements Navigating Your Financing Decisions
Before signing any agreement, it is vital to understand the total cost of the loan. Many people focus only on the monthly payment and forget to look at the total interest paid over the life of the loan. A $1,000 loan with a $50 monthly payment sounds affordable, but if the term is 36 months, you are paying back $1,800. Always calculate the “Total Cost of Credit” to see the true impact on your wallet.
Avoid the mistake of rushing into a high-interest agreement just because the approval is instant. While an emergency plumbing leak is stressful, a long-term debt trap can cause even more significant financial distress in the months to follow. If you can wait 48 hours to find a better rate, it is almost always worth it.
Always compare the APR between different lenders. A lender that offers “no credit check” options might seem attractive in a crisis, but the cost of that convenience is often reflected in much higher interest rates. APR (Annual Percentage Rate) is the most important number because it includes both the interest rate and any mandatory fees, giving you a complete picture of what the loan actually costs you per year.